
 Reviewed by Evelyn Waugh
Should You Use a Credit Card for Everyday Purchases?
Reviewed by Evelyn Waugh
Quick Answer
- You can use a credit card for everyday purchases to build credit and to earn rewards for the spending you already do.
- Remember that you should only use a credit card for purchases you can afford to pay back.
- Always make on-time payments to avoid damaging your credit and incurring fees.
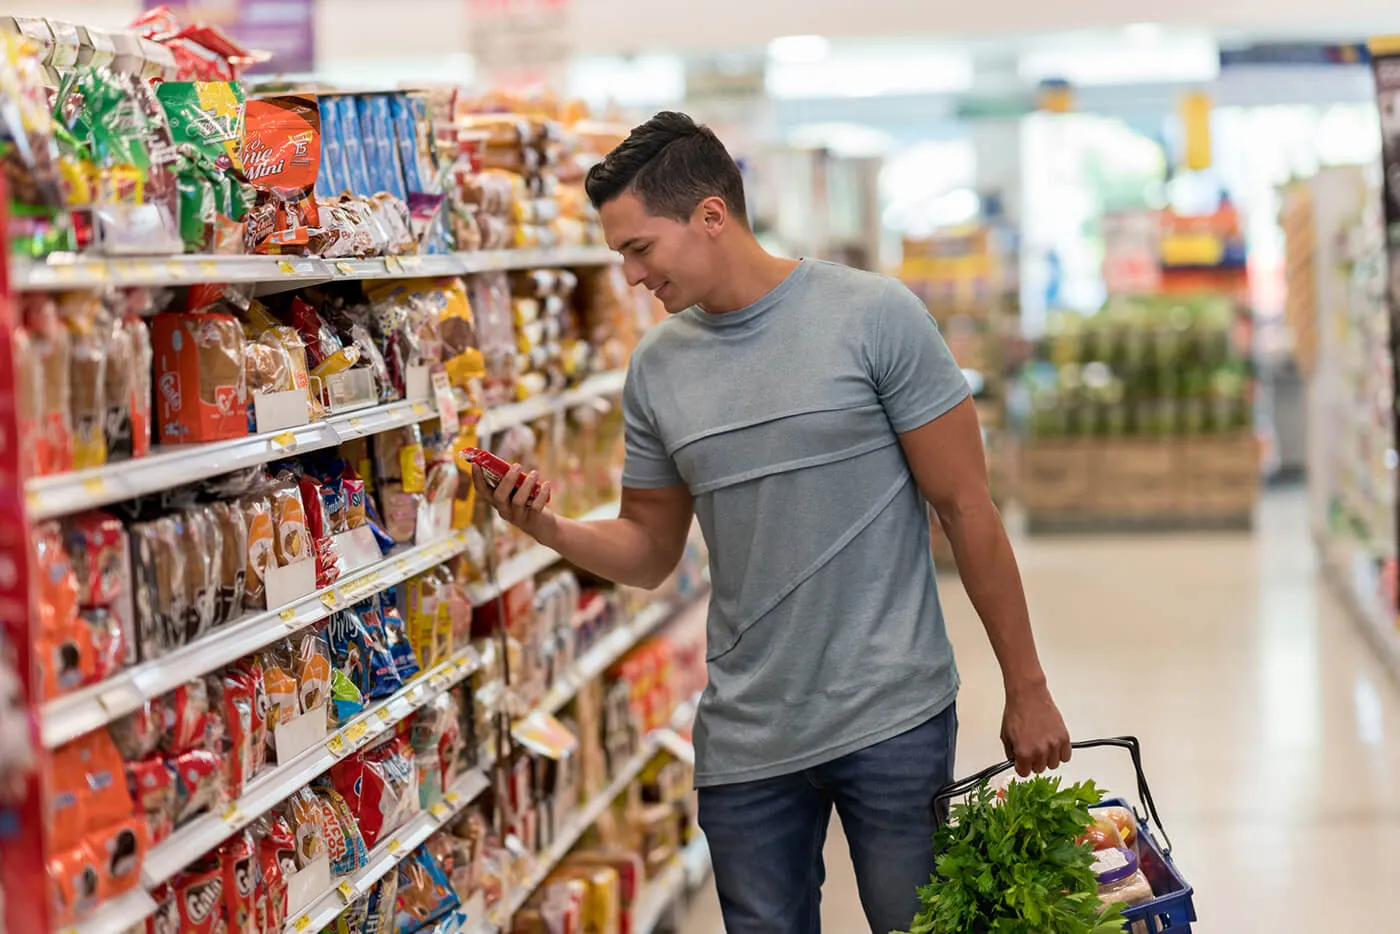
If you currently have a credit card that just sits in your wallet, reserved for occasional large purchases or a financial pinch, you may be missing out on some excellent benefits. Using credit cards for everyday spending can help you build credit, earn rewards and give you additional protections that you'll miss out on if you pay with cash or a debit card.
But to enjoy the benefits without taking on debt or hurting your score, you'll need to practice good credit habits and be strategic in how you spend. Here's what you need to know.
Benefits of Using Credit Cards for Everyday Purchases
Using your credit card for daily spending rather than just occasional purchases often comes with several major benefits.
Keep in mind, though, you should use your credit card for purchases you already would have made otherwise, and never spend solely in pursuit of rewards or other benefits. Use your credit card as you would a debit card or cash, on purchases such as groceries, gasoline and utility bills.
Here are some of the perks of using credit cards for everyday purchases:
1. Build Your Credit
You may already use a debit card for everyday purchases since it pulls funds directly from money you have in your checking account, but this activity isn't recorded on your credit report. If you want to build your credit, one of the easiest ways to do so is to use a credit card regularly and responsibly pay off as much as you can every month.
Your credit card account activity, such as balance changes and repayments, appear on your credit report and help you establish a credit history lenders can look at to assess your creditworthiness. If you keep your balance reasonably low and make on-time payments every month, you'll contribute to the positive growth of your credit history and scores.
2. Strategically Earn Rewards
One of the best arguments for using credit cards for everyday purchases is the potential to earn rewards in the form of cash back or points you can redeem for things like travel or hotel stays. If you use a credit card for day-to-day spending rather than a debit card, then pay it off at the end of each month before interest kicks in, your rewards earning potential increases drastically.
Keep in mind that some rewards cards have permanent or rotating bonus categories that allow you to earn a higher rewards rate on certain types of purchases (such as travel or dining). If you use your card on these purchases, you can maximize your credit card rewards.
Best rewards cards of 2026
Compare cards from our partners that earn points, cash back or miles on everyday spending.
Offers from our partners
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$75*
Citi® / AAdvantage® Globe™ Mastercard®
Ongoing APR:19.49% - 29.49% (Variable)
Rewards:
1x - 6x (Miles per dollar)
Earn 6 AAdvantage® miles for every $1 spent on eligible hotels booked through aadvantagehotels.com. Earn 3 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Earn 2 AAdvantage® miles for every $1 spent at restaurants, including takeout and delivery. Earn 1 AAdvantage® miles for every $1 spent on all other purchases.
Annual Fee:$350
AT&T Points Plus® Card from Citi
Intro bonus:
$200
Earn a $200 statement credit after you spend $1,000 on purchases in the first 3 months of account opening.
Ongoing APR:19.49% - 27.49% (Variable)
Rewards:
1x - 3x (Points per dollar)
Earn 3 ThankYou® Points for every $1 spent at gas and EV charging stations. Earn 2 ThankYou® Points for every $1 spent at grocery stores and 2 ThankYou® Points for every $1 spent on AT&T products and services. Earn 1 ThankYou® Point for every $1 spent on all other purchases.
Annual Fee:$0
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$39*
Hilton Honors American Express Card
Intro bonus:
70,000 Points
Earn 70,000 Bonus Points plus a Free Night Reward after you spend $2,000 in purchases on the card in the first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.49%-28.49% Variable
Rewards:
3x - 7x (Points per dollar)
Earn 7X Hilton Honors Bonus Points for each dollar of eligible purchases charged on your Card directly with a hotel or resort within the Hilton portfolio. Earn 5X Hilton Honors Bonus Points for each dollar of eligible purchases on your Card: at U.S. restaurants, at U.S. supermarkets, at U.S. gas stations. Earn 3X Hilton Honors Bonus Points for all other eligible purchases on your Card.
Annual Fee:$0
Credit One Bank® Premier American Express® Unlimited Rewards Card
Ongoing APR:29.74% Variable
Rewards:
1% (cash back)
Earn unlimited 1% cash back rewards on all purchases, terms apply
Annual Fee:$0
Hilton Honors American Express Aspire Card
Intro bonus:
200,000 Points
Best Points Offer Yet! Earn 200,000 Hilton Honors Bonus Points with the Hilton Honors American Express Aspire Card after you spend $6,000 in purchases on the Card within your first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.49%-28.49% Variable
Rewards:
3x - 14x (Points per dollar)
Earn 14X Hilton Honors Bonus Points when you make eligible purchases on your Card directly with hotels and resorts within the Hilton portfolio. Card Members can earn 7X Points on purchases of Flights booked directly with airlines or flights booked through American Express Travel, Car rentals purchased directly from select car rental companies, and purchases at U.S. Restaurants. Card Members can earn 3X Points on all other eligible purchases.
Annual Fee:$550
Avant® Cashback Rewards Mastercard®
Ongoing APR:29.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$0*
See all our best rewards credit cards for 2026.
3. Take Advantage of Generous Consumer Protections
Credit cards offer several security features. Whereas with debit cards you may be fully liable for fraudulent purchases, credit cards offer limited or zero liability. That means you aren't on the hook for fraudulent purchases made without your knowledge or consent.
Many credit cards also offer extended warranties or purchase protection on items you buy with the card, in addition to price protection, which gives you a refund if the price of something you purchase with the card drops after you buy it.
4. Easily Track Your Spending
Credit cards send you monthly statements that show all of your monthly transactions, which can make it easier to track spending than if you use cash. Most also have online apps that make it simple to keep tabs on your spending. While debit cards have this functionality too, this feature of credit cards can help you make sure you only spend within your means.
5. Finance Large Purchases
Using a credit card to finance a big purchase can help you spread out payments. It's an especially solid idea when used to take advantage of credit card perks such as an introductory bonus, or when used in tandem with an promotional interest rate so that you don't accrue any interest on your balance while you pay it off.
How Using Your Credit Card Every Day Can Impact Credit Scores
Using your credit card for your everyday spending has plenty of benefits—but you should always carefully monitor your spending and use your credit strategically to avoid taking on debt and hurting your credit.
Here's how using a credit card for everyday purchases can impact your credit score, positively or negatively:
Ways Credit Card Use Can Increase Your Credit Score
- Building up your payment history: A history of making credit payments on time is the largest factor that determines your credit score. Setting up autopay for at least the minimum payment can help you build your score, while also avoiding any late fees. Paying off your balance in full every month will prevent you from accruing credit card debt.
- Maintaining low credit utilization: Maintaining a low credit utilization rate is beneficial to your credit scores. To help keep your credit scores in tip-top shape, pay off your balance every month or keep your balance low to maintain a credit utilization ratio under 30% (the lower, the better). This means if you have a card with a $10,000 credit limit, try to keep your balance below $3,300.
Ways Credit Card Use Can Decrease Your Credit Score
- Making a late payment: Your payment history is the single most impactful factor in determining your credit score. Making a 30-day late payment can result in a negative mark on your credit report and a reduction in your credit score.
- Carrying a high balance: Any credit card you're issued will be assigned a credit limit. A credit card balance that's close to its limit increases your credit utilization ratio, which lenders and credit scorers see as a red flag.
Tips for Using Your Credit Card Responsibly
If you've only ever used credit cards occasionally, it can be an adjustment to switch to using it in place of a debit card for everyday purchases. Follow these tips to get the most out of your credit card and avoid any credit mistakes:
- Keep your balance low. Aim to keep your credit utilization ratio at or below 30%, and never max out your card.
- Don't buy things you can't afford. If you decide to use your credit card for everyday purchases, it's crucial you avoid overspending and make sure to only use it for things you would otherwise be comfortable buying with your debit card. Make sure you can pay off what you're putting on the card on time each month, especially if you want to avoid making interest payments.
- Make on-time payments. Late and missed payments harm your credit, whereas a history of on-time repayment helps build positive credit. If you're likely to forget to pay your bill, set up calendar reminders or automatic payments for at least the minimum payment amount.
Find the Right Credit Card for Your Wallet
Using your credit card for everyday purchases can unlock a host of benefits. To ensure you get the benefits without taking on debt or hurting your score, practice good credit habits.
Using a credit card for the spending you already do is an especially good move when paired with a rewards card that rewards spending in the categories you spend the most in. To find the best rewards card for you, try Experian's card comparison platform. You'll get customized credit card offers based on your current scores that won't impact your credit.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author

Emily Starbuck Gerson
Emily Starbuck Gerson is a freelance writer who specializes in personal finance, small business, LGBTQ and travel topics. She’s been a journalist for over a decade and has worked as a staff writer at CreditCards.com and NerdWallet. Emily’s work has appeared in CNBC, MarketWatch, Business Insider, USA Today, The Christian Science Monitor and the Chicago Tribute, among other websites and publications.
Read more from Emily Starbuck