By Ben Luthi
 Edited by Michelle TipswordBy Ben LuthiEdited by Michelle Tipsword

A CVV is a three- or four-digit code printed on your credit card that helps verify you have the physical card when you make online or phone purchases, adding a layer of protection against fraud.
When you buy something online or over the phone, you're often asked to enter a short security code along with your card number and expiration date. That code is your CVV, and it plays a key role in protecting you from fraud. Here's what the CVV on your credit card does, where to find it and how to keep it safe.
A CVV is a three- or four-digit security code printed on your credit card that helps verify you have the physical card in your possession. CVV stands for card verification value, and it's designed to add a layer of protection against fraud when your card isn't physically present at checkout.
Different card networks use different names for this code, but they all serve the same purpose. Depending on the type of card you have, it may also be referred to as a CVV2, CVC2, card security code (CSC) or card identification number (CID). Regardless of the name, merchants use it to confirm a purchase is likely being made by the legitimate cardholder.
Learn more: Pros and Cons of Virtual Credit Cards
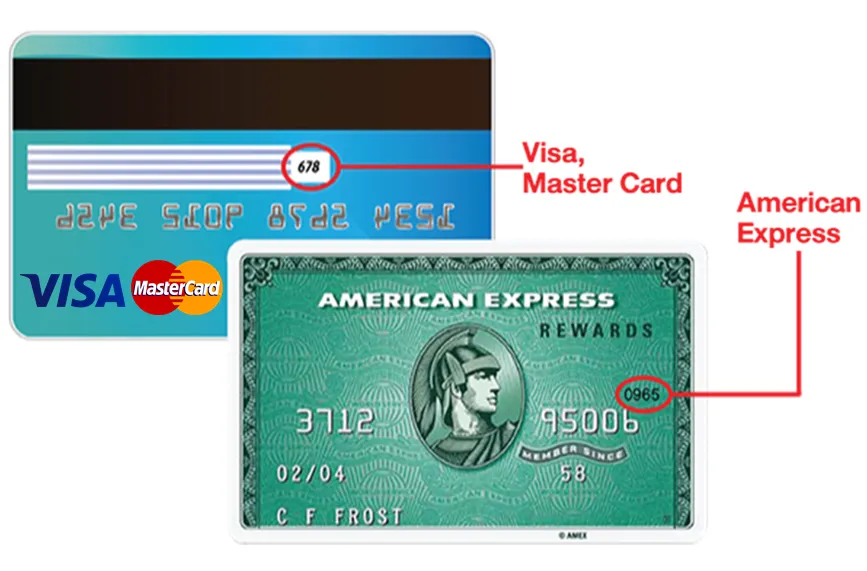
The location of your CVV depends on which card network issued your card. For Visa, Mastercard and Discover, the three-digit code is printed on the back of the card, typically to the right of where the signature panel is or was.
For American Express cards, the four-digit CID is printed on the front of the card, above and to the right of the card number.
The main purpose of a CVV is to prove you have the physical card during transactions where a merchant can't see or swipe it. These are known as card-not-present transactions, and they're one of the most common targets for fraud.
You'll typically be asked to enter your CVV in the following situations:
You generally won't need your CVV for in-person transactions. When you tap, insert or swipe your card at a payment terminal, the terminal reads the chip or magnetic stripe to verify the card, so the CVV isn't required.
CVVs add an extra layer of defense against identity theft and unauthorized transactions. Under the Payment Card Industry Data Security Standard (PCI DSS), merchants and service providers are prohibited from storing your CVV after a transaction is authorized, even if you give them permission.
So even if a thief hacks into a merchant's database and steals stored card numbers and expiration dates, they shouldn't walk away with your CVV. Without it, many online and phone merchants will reject a transaction, which limits what a thief can do with the stolen information.
That said, the CVV isn't a silver bullet. Thieves can still get your full card information through the following:
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
Citi Strata Premier® Card
Ongoing APR:19.74% - 27.74% (Variable)
Annual Fee:$95
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Annual Fee:$75 first year; then $99/year
First Progress Prestige Secured Mastercard® Cash Back Rewards
Ongoing APR:13.49% Variable
Annual Fee:$49
Credit One Bank® Platinum Rewards Visa® Card
Ongoing APR:29.74% Variable
Annual Fee:$39
Hilton Honors American Express Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$0
Delta SkyMiles® Reserve American Express Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$650
Delta SkyMiles® Blue American Express Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$0
Ollo Everyday Rewards
Ongoing APR:23.99%-29.99% Variable
Annual Fee:$0
See all our best credit cards for 2026.
It's safe to share your CVV with a legitimate merchant during a purchase, but only then. The CVV exists to be used at checkout, so entering it on a trusted retailer's secure website or giving it to a reputable company over the phone is generally fine.
But, you should never provide it in response to an unsolicited email, text or phone call, even if the sender claims to be from your bank or a company you use. This is also true for websites you land on by clicking a link in a suspicious message or anyone offering to "verify" your account or confirm a suspicious charge.
Be aware: Your card issuer will never call or email you out of the blue and ask for your CVV. If someone does, assume it's a scam.
Learn more: The Latest Scams You Need to Be Aware Of
A CVV is just one layer of protection. The following habits can help keep your full card information out of the wrong hands:
Tip: Many card issuers offer a virtual card number feature, which lets you generate a temporary card number and CVV for online shopping. If the number is stolen, the thief can't use it elsewhere or for long.
A CVV is a simple but effective tool that helps keep your credit card secure during online and phone purchases. Still, no single security feature can stop every threat, so it's smart to back it up with good habits like monitoring your accounts, avoiding suspicious links and shopping only on trusted sites.
You can also keep a closer eye on your personal and financial information with free credit monitoring from Experian. You'll get alerts about key changes to your Experian credit report, so you can act quickly if something looks off.
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
Ben Luthi
Ben Luthi has worked in financial planning, banking and auto finance, and writes about all aspects of money. His work has appeared in Time, Success, USA Today, Credit Karma, NerdWallet, Wirecutter and more.
Read more from Ben