
 By John Egan
Should You Accept an In-Flight Credit Card Offer?
By John Egan
Quick Answer
Experts generally recommend against accepting in-flight credit card offers handed out by flight attendants. Why? As you’re sitting on a plane, you may be unable to adequately judge how this offer compares with other credit card offers, so you could miss out on some perks or end up paying more in interest and fees.
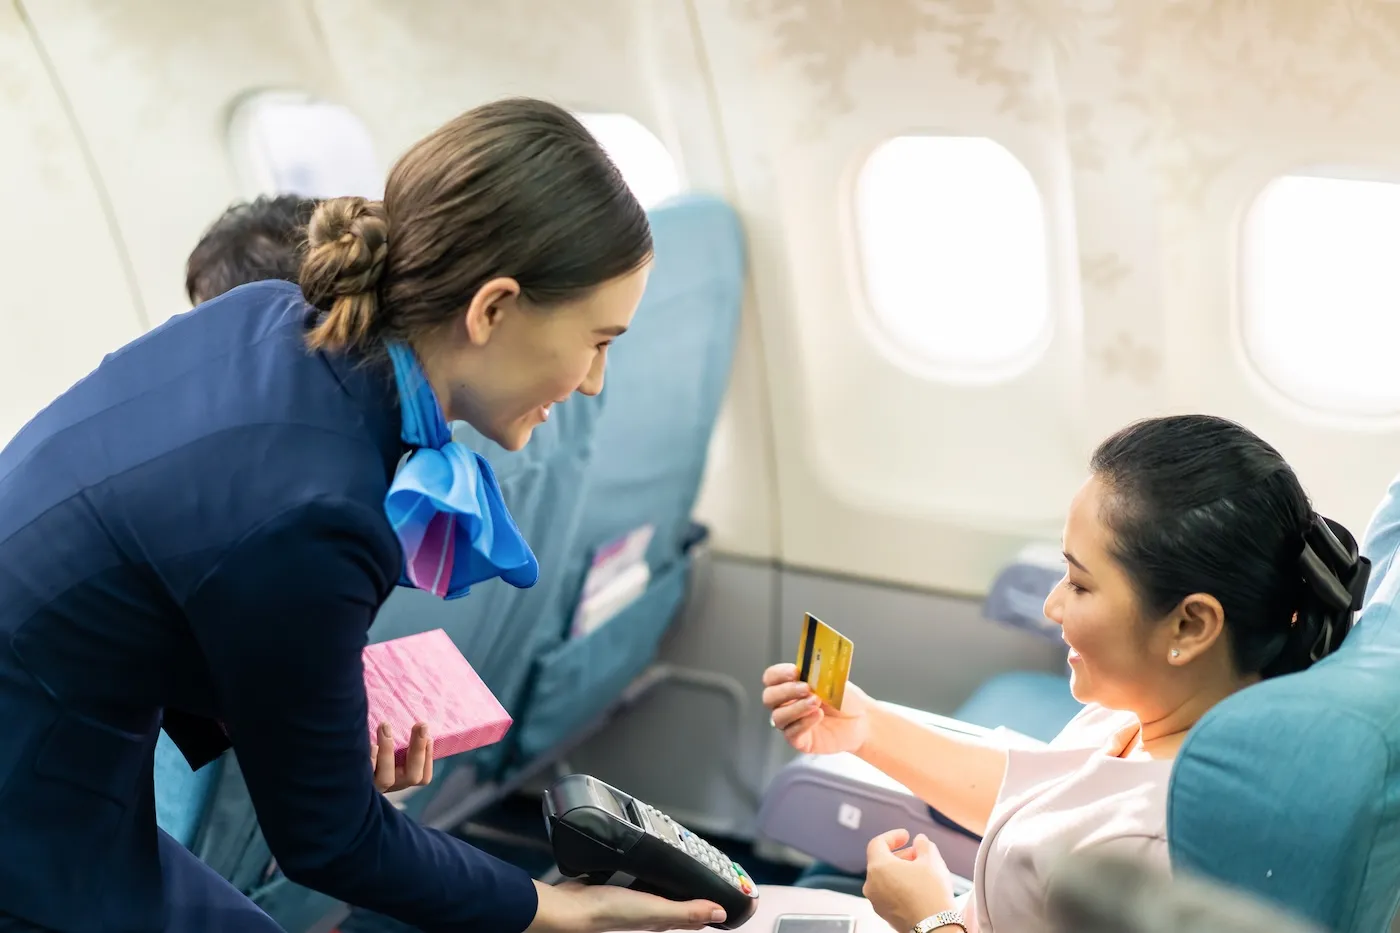
If you've been aboard a flight recently, you may have spotted a flight attendant strolling down the aisle clutching glossy brochures that market an airline-branded credit card. Meanwhile, a voice over the PA system goes over the offer's highlights. As an enticement, the in-flight offer might, for example, supply 65,000 frequent flier miles as a welcome bonus as opposed to the usual 60,000 miles.
Sounds like quite a deal, right? It could be. But before you grab one of these in-flight offers and fill out a credit card application, think twice about whether the bonus is worth it—and whether you need another credit card.
How Do In-Flight Credit Card Offers Work?
In-flight offers for co-branded credit cards—provided in this case through a partnership between an airline and a card issuer—might come with perks that you may not find with on-the-ground offers. For instance, the card offer might include the waiver of an annual fee.
What do the airlines gain from these offers?
"Airlines primarily benefit from increased brand loyalty and higher revenue from increased ticket sales, but the arrangement between the airline and the credit issuer can give the airline a larger target audience for marketing," says Bruce McClary, senior vice president of membership and communications at the National Foundation for Credit Counseling.
Best travel cards of 2026
Compare cards from our partners that earn valuable points or miles and unlock travel perks on flights and hotel stays.
Offers from our partners
American Express Platinum Card®
Intro bonus:
As High As 175,000 points. Find Out Your Offer.
You may be eligible for as high as 175,000 Membership Rewards® Points after spending $12,000 in eligible purchases on your new Card in your first 6 months of Membership. Welcome offers vary and you may not be eligible for an offer.
Ongoing APR:See Pay Over Time APR
Rewards:
1x - 5x (Points per dollar)
Get more for your travels with 5X Membership Rewards® points on all flights and prepaid hotel bookings through American Express Travel®, including Fine Hotels + Resorts® and The Hotel Collection bookings. You earn 5X points on flights purchased directly from airlines or through American Express Travel® on up to $500,000 on these purchases per calendar year.
Annual Fee:$895
American Airlines AAdvantage® MileUp® Card
Intro APR:0% for 15 months on Balance Transfers
Ongoing APR:19.74% - 29.74% (Variable)
Rewards:
2x (Miles per dollar)
Earn 2 AAdvantage® miles for each $1 spent at grocery stores, including grocery delivery services. Earn 2 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Save 25% on inflight food and beverage purchases when you use your card on American Airlines flights
Annual Fee:$0
Hilton Honors American Express Card
Intro bonus:
70,000 Points
Earn 70,000 Bonus Points plus a Free Night Reward after you spend $2,000 in purchases on the card in the first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.74%-28.74% Variable
Rewards:
3x - 7x (Points per dollar)
Earn 7X Hilton Honors Bonus Points for each dollar of eligible purchases charged on your Card directly with a hotel or resort within the Hilton portfolio. Earn 5X Hilton Honors Bonus Points for each dollar of eligible purchases on your Card: at U.S. restaurants, at U.S. supermarkets, at U.S. gas stations. Earn 3X Hilton Honors Bonus Points for all other eligible purchases on your Card.
Annual Fee:$0
Delta SkyMiles® Reserve American Express Card
Intro bonus:
Earn 2 Delta Comfort Flight Certificates + 50K Miles
Earn two domestic Delta Comfort Flight Certificates + 50,000 Bonus Miles after $10,000 in purchases on your new Card in your first 6 months. A 21+ day advance purchase required. Taxes and fees up to $80 per person apply. Terms and other restrictions apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 3x (Miles per dollar)
Earn 3X Miles on Delta purchases and earn 1X Miles on all other eligible purchases.
Annual Fee:$650
Delta SkyMiles® Gold American Express Card
Intro bonus:
As High As 80K Miles + $250 Statement Credit
You may be eligible for as high as 80,000 Bonus Miles and a $250 Statement Credit after you spend $3,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 2x (Miles per dollar)
When you use your Delta SkyMiles® Gold American Express Card, you can earn: 2X miles on Delta Purchases, 2X miles at restaurants, 2X miles at U.S. supermarkets, 1X miles on all other eligible purchases. Every mile you earn brings you closer to the places you want to go. Turn them into your next trip, use them for seat upgrades, and more.
Annual Fee:$0 introductory annual fee for the first year, then $150.
Delta SkyMiles® Platinum American Express Card
Intro bonus:
As High As 90K Miles + $300 Statement Credit
You may be eligible for as high as 90,000 Bonus Miles and a $300 Statement Credit after you spend $4,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 3x (Miles per dollar)
Earn 3X Miles on Delta purchases and purchases made directly with hotels. Earn 2X Miles at restaurants worldwide including takeout and delivery in the U.S., and at U.S. supermarkets. Earn 1X Miles on all other eligible purchases.
Annual Fee:$350
Hilton Honors American Express Surpass® Card
Intro bonus:
130,000 Points
Earn 130,000 Bonus Points plus a Free Night Reward after you spend $3,000 in purchases on the Hilton Honors American Express Surpass® Card in the first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.74%-28.74% Variable
Rewards:
3x - 12x (Points per dollar)
Earn 12X Hilton Honors Bonus Points for each dollar of eligible purchases charged on your Card directly with a hotel or resort within the Hilton portfolio. Earn 6X Hilton Honors Bonus Points for each dollar of eligible purchases on your Card at U.S. restaurants, at U.S. supermarkets, and at U.S. gas stations. Earn 4X Hilton Honors Bonus Points for each dollar of U.S. Online Retail purchases. Earn 3X Hilton Honors Bonus Points for all other eligible purchases on your Card.
Annual Fee:$150
Marriott Bonvoy Bevy® American Express® Card
Intro bonus:
85,000 Bonus Points
Earn 85,000 Marriott Bonvoy® bonus points after you use your new Card to make $5,000 in purchases within the first 6 months of Card Membership.
Ongoing APR:19.74%-28.74% Variable
Rewards:
2x - 6x (Points per dollar)
Earn 6X Marriott Bonvoy® points for each dollar of eligible purchases at hotels participating in Marriott Bonvoy®. Earn 4X points at restaurants worldwide and U.S. Supermarkets (on up to $15,000 in combined purchases at restaurants and U.S. supermarkets per calendar year, then 2X points). Earn 2X points on all other eligible purchases.
Annual Fee:$250
See all our best travel credit cards for 2026.
Is Applying for In-Flight Credit Cards a Good Idea?
Whether one of these offers is a good idea for you depends on your own situation. What might be an attractive offer for you might be a bad idea for the passenger seated next to you, and vice versa.
Let's say you have just a couple of travel rewards cards and the in-flight offer would sweeten the deal for a card affiliated with an airline that you fly frequently. In this case, it might be wise to snag the offer. But if you've already got several travel rewards credit cards, does the prospect of scoring some extra miles make it worthwhile to take advantage of the offer? Perhaps not.
The airline-branded cards being pitched in the air by flight attendants might be the same as airline-branded cards you'd consider when you're on the ground. The only difference may be a more generous welcome bonus. In-flight offers might feature an appealing bonus—such as extra frequent flier miles—to help reel you in as an applicant.
"On some flights, you'll hear flight attendants talk about a special welcome offer only available for the new customers who apply during the flight, but the card itself is one that you can apply for at any time," says Madison Blancaflor of The Points Guy travel and credit cards website.
"What kind of welcome offer you get in the air will vary. Sometimes, it's actually the same welcome offer you'd receive by applying through the card issuer's website," adds Blancaflor. "Sometimes, it's a better offer—either increased miles or a waived annual fee for the first year, for example. But occasionally, the offer in the air can actually be a worse offer than what you can get by applying online."
Generally, a special offer pitched by a flight attendant refers to a welcome offer for new cardholders, according to Blancaflor. However, many cards, especially travel credit cards like co-branded airline cards, extend welcome offers to new customers regardless of whether you apply in the air or on the ground.
"For new customers who spend a certain amount on the new card within a certain timeframe, you can get a large deposit of miles," she says. "Welcome offers are a great way to quickly earn enough points or miles to cover the cost of your next flight."
Blancaflor notes that a passenger may be required to complete an application on the plane to qualify for a welcome bonus. For each submitted application, a flight attendant might receive a bonus of roughly $25 to $90, she says.
When Should You Accept or Reject an In-Flight Credit Card Offer?
No matter whether an in-flight credit card offer sounds fantastic or iffy, Blancaflor cautions against impulsively completing an application while you're in the air.
When You May Want to Accept an In-Flight Credit Card Offer
In some instances, an in-flight credit card offer might be worthwhile.
"The best time to apply for an in-flight offer is when you've already been considering applying for the specific card offered on the flight, have researched the card's benefits to know it'll be a good fit for your spending habits and travel goals, and have an idea of what the typical welcome offer is for the card," Blancaflor says. "If you've done all of that research and a card offer in flight is better than the one offered online, it can make a lot of sense to apply while in the air to take advantage [of it]."
When You May Want to Reject an In-Flight Credit Card Offer
It might not make sense to accept an offer, though, if you've never heard about a card that's being marketed by a flight attendant, Blancaflor says. Instead of hurriedly completing an application, take time to research the card, compare it to other cards and consider how attractive the welcome offer is.
"Just because it's an exclusive in-flight offer doesn't mean it's necessarily a better offer than what you can get online," she says.
Blancaflor points out that while no flight attendant would intentionally mislead a passenger or misrepresent a credit card offer, some flight attendants do mix up details when they're explaining an offer. For example, a flight attendant might misstate the terms of an offer while reciting a sales script from memory or reading a prewritten script.
"Regardless of where you see or hear a credit card offer—during your flight, at the check-out counter of your favorite store, online—always read the terms and conditions on the application itself," she says. "What a flight attendant says during a flight about a credit card offer isn't legally binding, but those terms and conditions will be the most accurate reflection of what you'll get from a specific credit card offer."
Things to Consider When Weighing an In-Flight Credit Card Offer
Before submitting an application tied to an in-flight credit card offer, ask yourself these questions:
- How do the card's perks compare with those from cards you already have or other cards might consider? Are the perks for the card being marketed aboard the plane so compelling that you can't pass up the offer? Or do you already have attractive card perks or can find cards with perks that beat those from the card being pitched in the air?
- Will you qualify for the offer? The card being offered by a flight attendant might come with a strict credit score requirement. If you apply for the card but your credit score isn't high enough to be approved, the hard inquiry that the card issuer makes when reviewing your credit report might cause a small, temporary dip in your credit score.
- Do you really need another credit card? There's no set number of cards that anyone should have, but you don't want to have so many cards that your balances cause financial strain.
- Can you afford to take on more debt? Lenders typically look for a debt-to-income ratio below 43%. So if your ratio surpasses that figure, you might not want to apply for the in-flight offer.
- Are you a regular customer of the airline? Or are you an infrequent flier? It might be smarter to accept the in-flight offer if the card would give you miles or other perks for one of your go-to airlines.
- What is the annual percentage rate (APR)? How does it stack up against other credit cards? As of November 2023, the average interest rate for credit cards stood at 22.75%, according to the Federal Reserve.
- Does the card charge an annual fee or other pesky fees? If so, you might want to look for a card with no fees or at least fewer fees.
Other Ways to Save on Travel Costs
If you're hunting for ways to save on travel costs, other ways to achieve this may include:
- Applying for another travel rewards card: A card being offered aboard a plane might deliver fewer rewards than a card you might find on your own.
- Setting aside travel funds in a high-yield savings account: In this case, you can avoid accepting an in-flight credit card offer—and avoid potential card fees and interest charges.
- Signing up for newsletters that promote travel deals: Popular travel newsletters include Dollar Flight Club, The Navigator and Going.
- Booking flights in advance rather than at the last minute: Flights tend to be more expensive the closer you get to takeoff.
- Using rideshare services or public transit instead of renting a car: Some credit cards provide transportation perks, although perhaps not the card being pitched aboard your flight.
- Looking at driving rather than flying to your destination: It's typically cheaper to drive if you're taking a shorter trip.
- Heading to destinations during lower-cost seasons instead of higher-cost seasons: For instance, it might cost less to head to Cancun, Mexico, in the summer or fall than during the busier spring break and winter travel periods.
The Bottom Line
Credit card offers pitched by flight attendants might seem appealing as you're soaring above the clouds. But don't let these offers cloud your judgment. You may be better off rejecting these offers and, once you've safely landed, comparing credit card interest rates and other factors before applying for a new card. If you plan to get a new credit card, be sure to check your free credit report from Experian before submitting an application.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author
John Egan
John Egan is a freelance writer, editor and content marketing strategist in Austin, Texas. His work has been published by outlets such as CreditCards.com, Bankrate, Credit Karma, LendingTree, PolicyGenius, HuffPost, National Real Estate Investor and Urban Land.
Read more from John