 By Ismat Mangla
Why Getting a New Credit Card Is a Good Idea
By Ismat Mangla
If you've had the same credit cards in your wallet for a while, it might be a good time to ask yourself whether you should get a new credit card. A new credit card can potentially unlock access to a number of benefits and savings you're not taking advantage of—and it can even improve your credit scores. Worried that getting a new card will hurt your already exceptional credit score? Think again. Below, we'll explain why getting a new credit card could be your next smart financial move.
You Can Increase Your Credit Card Rewards Earnings
If you haven't gotten a new rewards card in a while, it's worth taking another look at what's out there. The credit card landscape has become increasingly competitive in recent years, with issuers adding all sorts of intro bonuses and perks to sweeten the pot. Many travel rewards cards now offer benefits like fee credits for trusted traveler programs. Intro bonuses are impressively high, and there are a number of new cards that let you maximize your rewards earnings based on how you spend.
Best rewards cards of 2026
Compare cards from our partners that earn points, cash back or miles on everyday spending.
Offers from our partners
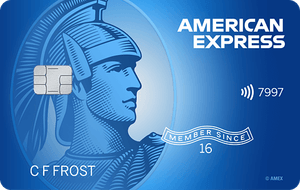
Blue Cash Everyday® Card from American Express
Intro bonus:
As High As $200 Cash Back. Find Out Your Offer.
You may be eligible for as high as $200 cash back after spending $2,000 in purchases on your new Card in the first 6 months. Welcome offers vary and you may not be eligible for an offer. Cash back is received as Reward Dollars, redeemable for statement credit or at Amazon.com checkout. Terms Apply.
Intro APR:0% on Purchases and Balance Transfers for 15 months
Ongoing APR:19.74%-28.74% Variable
Rewards:
1% - 3% (cash back)
Earn 3% cash back at U.S. supermarkets, 3% cash back on U.S. online retail purchases, 3% cash back at U.S. gas stations, on eligible purchases for each category on up to $6,000 per year in purchases (then 1%). Cash back is received in the form of Reward Dollars that can be redeemed as a statement credit and at Amazon.com checkout.
Annual Fee:$0
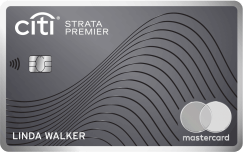
Citi Strata Premier® Card
Intro bonus:
60,000 Points
Earn 60,000 bonus ThankYou® Points after spending $4,000 in the first 3 months of account opening, redeemable for $600 in gift cards or travel rewards at thankyou.com.
Ongoing APR:19.74% - 27.74% (Variable)
Rewards:
1x - 10x (Points per dollar)
Earn 10 Points per $1 spent on Hotels, Car Rentals, and Attractions booked on CitiTravel.com. Earn 3 Points per $1 on Air Travel and Other Hotel Purchases, at Restaurants, Supermarkets, Gas and EV Charging Stations. Earn 1 Point per $1 spent on all other purchases.
Annual Fee:$95
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$0*
Citi® / AAdvantage® Platinum Select® World Elite Mastercard®
Ongoing APR:19.74% - 29.74% (Variable)
Rewards:
2x (Miles per dollar)
Earn 2 AAdvantage® miles for every $1 spent at gas stations and restaurants, and on eligible American Airlines purchases. Earn 1 Loyalty Point for every 1 eligible AAdvantage® mile earned from purchases.
Annual Fee:$99, waived for first 12 months
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$75*
Hilton Honors American Express Card
Intro bonus:
70,000 Points
Earn 70,000 Bonus Points plus a Free Night Reward after you spend $2,000 in purchases on the card in the first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.74%-28.74% Variable
Rewards:
3x - 7x (Points per dollar)
Earn 7X Hilton Honors Bonus Points for each dollar of eligible purchases charged on your Card directly with a hotel or resort within the Hilton portfolio. Earn 5X Hilton Honors Bonus Points for each dollar of eligible purchases on your Card: at U.S. restaurants, at U.S. supermarkets, at U.S. gas stations. Earn 3X Hilton Honors Bonus Points for all other eligible purchases on your Card.
Annual Fee:$0
Avant® Cashback Rewards Mastercard®
Ongoing APR:29.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$0*
Bank of America® Customized Cash Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.74% - 27.74% Variable
Rewards:
1% - 6% (cash back)
Earn 6% cash back for the first year in the category of your choice. You’ll automatically earn 2% cash back at grocery stores and wholesale clubs, and unlimited 1% cash back on all other purchases. After the first year from account opening, you’ll earn 3% cash back on purchases in your choice category. Earn 6% and 2% cash back on the first $2,500 in combined purchases each quarter in the choice category, and at grocery stores and wholesale clubs, then earn unlimited 1% thereafter. After the 3% first-year bonus offer ends, you will earn 3% and 2% cash back on these purchases up to the quarterly maximum.
Annual Fee:$0
See all our best rewards credit cards for 2026.
You Can Save Money on Qualifying Interest
If you typically carry a balance on your credit cards, it's smart to shop for the card with the lowest interest rate possible. Your credit scores may have improved since the last time you applied for a card, which means you probably qualify for cards at lower rates now. Or you may be able to take advantage of a promotional rate that can save you money as you pay down your debt.
For example, a number of cards currently offer generous introductory 0% annual percentage rate (APR) financing. That means you can put your spending on one of these cards and pay off the debt during a promotional financing period without paying any interest.
Find some of the best low interest credit cards for your needs.
Unsure how to determine whether you qualify for a credit card for your needs? Sign up for Experian's card comparison tool for free. It can pair you with the credit cards you qualify for based on your FICO® ScoreΘ. Once you are matched with cards, you can compare them by features and card type.
You Can Improve Your Credit Scores
One of the common myths associated with opening a new credit card is that it will hurt your credit score. In fact, opening a new card—whether your credit score is already excellent or needs a little work—can actually help your credit in the long run. That's because a new line of credit can actually improve your credit utilization ratio, or the amount of credit you use in relation to the amount of credit you have available to you. This is one of the most important factors in calculating your credit scores.
Your credit utilization ratio is calculated by adding all your credit card balances at any given time and dividing that by your total credit limit. For example, if you typically have total balances of about $2,000 each month, and your total credit limit across all your cards is $10,000, your utilization ratio is 20%. But if you add another card to your wallet (increasing your total credit limit) but keep your spending the same, your utilization ratio will decrease.
Experts suggest keeping your utilization ratio below 30% and, for the best scores, below 6%.
You can get your FICO® Score from Experian to see where your utilization ratio currently stands.
Now, if you're concerned that a hard inquiry on your credit report will drag your credit scores down, take comfort. Typically, a hard inquiry for a new credit card only sets your score back a few points for a short period of time, generally less than 12 months. Your score rebounds from a hard inquiry pretty quickly. As long as you're not applying for multiple new lines of credit at once and paying your bills on time, your credit scores are safe.
What's more, a diversity of different types of credit on your credit report is also a good thing. Credit mix is one of the factors that go into determining your credit scores, and if you can demonstrate that you can handle a variety of accounts, your scores will benefit.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author
Ismat Mangla
Ismat Sarah Mangla is a veteran journalist with a background in writing about money and religion, though not necessarily at the same time. Her writing has appeared in Time, Fortune, Money, CNNMoney, Quartz, MarketWatch, Al Jazeera America, International Business Times, USA Today, The Washington Post, The Detroit Free Press and Michigan Alumnus magazine.
Read more from Ismat