
Should I Only Use a Credit Card for Bills and Recurring Transactions?
The average American has three credit cards, and plastic is the payment method of choice for many consumers. Over a quarter (29%) of those surveyed by the Pew Research Center in 2018 said they make no cash purchases at all over the course of a typical week. Using credit cards for everyday spending is certainly convenient—and doing so could help you build your credit. But are there downsides?
You may worry using a credit card to make day-to-day purchases with a variety of merchants could leave you open to credit and identity theft. Instead, you might use your debit card for these transactions, reserving your credit cards for regular monthly bills and subscriptions with companies you trust. However, reaching for your debit card for day-to-day spending isn't necessarily safer. There are actually fewer safeguards in place when it comes to consumer protections. What's more, you could be missing out on lucrative rewards if you only use your credit card for a few transactions a month.
There are pros and cons to using credit to cover daily spending. Understanding them can help you determine which payment method is the best fit for you.
Benefits of Using Credit Cards for Recurring Transactions
There are many reasons why using credit cards for recurring monthly expenses can be a smart financial move—not the least of which is that handling payments for things like your cellphone and video streaming accounts with a credit card you have set to autopay helps make sure you never miss a payment. Here are some additional perks.
You're Keeping That Card Open and Active
When you stop using a credit card for an extended period, you run the risk of that card being canceled by the lender. This is because credit card issuers may close accounts that have been inactive for a long time. While most issuers do not disclose their exact policies, it stands to reason that there isn't much incentive for them to keep dormant fee-free accounts open for the long haul. (Be sure to check your cards' terms and conditions regarding their inactivity policies.)
Closing an inactive account might come as a benefit to a card issuer, but it has the potential to bring down your credit scores. For starters, your available credit will decrease. So if you're carrying balances on other accounts, your credit utilization rate will go up. This, in turn, can drag down your score. Closed accounts also decrease the average age of your credit history, which makes up 15% of your FICO® ScoreΘ. Accounts closed in good standing stay on your credit report for 10 years after they're closed, so this is a smaller worry, but it could eventually cause you some strife if it's an old account with a spotless payment history.
You're Staying Ahead of Scammers
Credit cards come with some degree of built-in fraud protection. Thanks to the Fair Credit Billing Act, cardholders can't be held liable for more than $50 of unauthorized charges. Most credit card issuers take this to the next level and waive cardholder liability altogether. This could be a huge relief if your account number is ever compromised. In this way, using credit cards can provide additional peace of mind.
Debit cards are a different story. If a fraudster racks up transactions with your card, that money will come directly out of your bank account—and you could end up waiting days for your bank to reimburse you. Moreover, you might ultimately be on the hook for more than $50 in charges.
The Perks of Using Credit Cards for Everyday Spending
Using credit cards for recurring transactions comes with quite a few perks. The same can also be said for using a credit card to cover everyday spending that goes beyond your monthly bills. Opting for a debit card or cash means missing out on potential points, rewards and other perks.
Whether you're spending on groceries, gas, eating out or staying at a hotel, there are plenty of rewards cards that let you earn while you do your regular shopping. On top of that, you could land a lucrative sign-up bonus in the process. Rewards cards are ideal for eligible consumers who don't carry a balance from month to month. If you do, high interest rates could negate the benefits. You'll also want to compare any annual fees to see if they're worth it.
Further, it's not uncommon for credit cards to offer additional consumer protections such as extended warranties on goods you buy, increased fraud protection (more on that later) and purchase protection.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
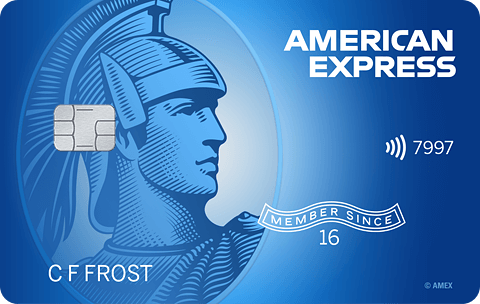
Blue Cash Everyday® Card from American Express
Intro APR:0% on Purchases and Balance Transfers for 15 months
Ongoing APR:19.49%-28.49% Variable
Annual Fee:$0
The opensky® Secured Visa® Credit Card
Ongoing APR:23.89% Variable
Annual Fee:$35
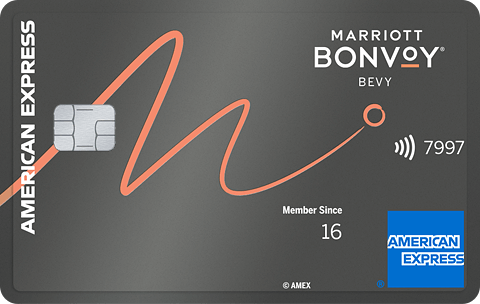
Marriott Bonvoy Bevy® American Express® Card
Ongoing APR:19.49%-28.49% Variable
Annual Fee:$250
Ollo Everyday Rewards
Ongoing APR:23.99%-29.99% Variable
Annual Fee:$0
Avant® Cashback Rewards Mastercard® - $500 Credit Limit
Ongoing APR:35.99%*
Annual Fee:$125 first year; then $125.04/year ($10.42/mo)
Bank of America® Travel Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.49% - 27.49% Variable
Annual Fee:$0
Bank of America® Premium Rewards® credit card
Ongoing APR:19.49% - 27.49% Variable
Annual Fee:$95
Bank of America® Unlimited Cash Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.49% - 27.49% Variable
Annual Fee:$0
See all our best credit cards for 2026.
The Downside of Using Credit Cards for Daily Expenses
Swiping your credit card to cover daily expenses is only a good idea if you're properly budgeting to ensure your debt doesn't get out of hand. Things can get complicated if you're blindly using credit cards to cover transactions without keeping a close eye on your balances. Credit card spending comes with benefits, sure, but doing so irresponsibly could trap you in a cycle of debt that's hard to escape from. Instead, it's best to charge purchases you plan on paying off in full each month. If something comes up that throws off your budget, aim to keep your balance at or below 30% of your credit limit. Doing so can help protect your FICO® Score from taking a hit.
The Bottom Line
Whether you're using credit cards for recurring transactions, everyday spending or both, keeping your private information safe is always a top priority. An Experian Premium membership allows for comprehensive identity theft protection that includes dark web surveillance, fraud resolution and more. Free credit monitoring is another simple, hands-off way to detect potential fraud sooner and stop it in its tracks.
If you're looking for a credit card to use, Experian's card comparison tool can link you up with excellent credit cards matched to your profile.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author

Marianne Hayes
Marianne Hayes is a longtime freelance writer who's been covering personal finance for nearly a decade. She specializes in everything from debt management and budgeting to investing and saving. Marianne has written for CNBC, Redbook, Cosmopolitan, Good Housekeeping and more.
Read more from Marianne