
Are Virtual Credit Cards Safe?

Quick Answer
Virtual credit cards can make online shopping more secure. They allow you to use your credit card without exposing your account number, which provides an extra barrier between you and cyber criminals.
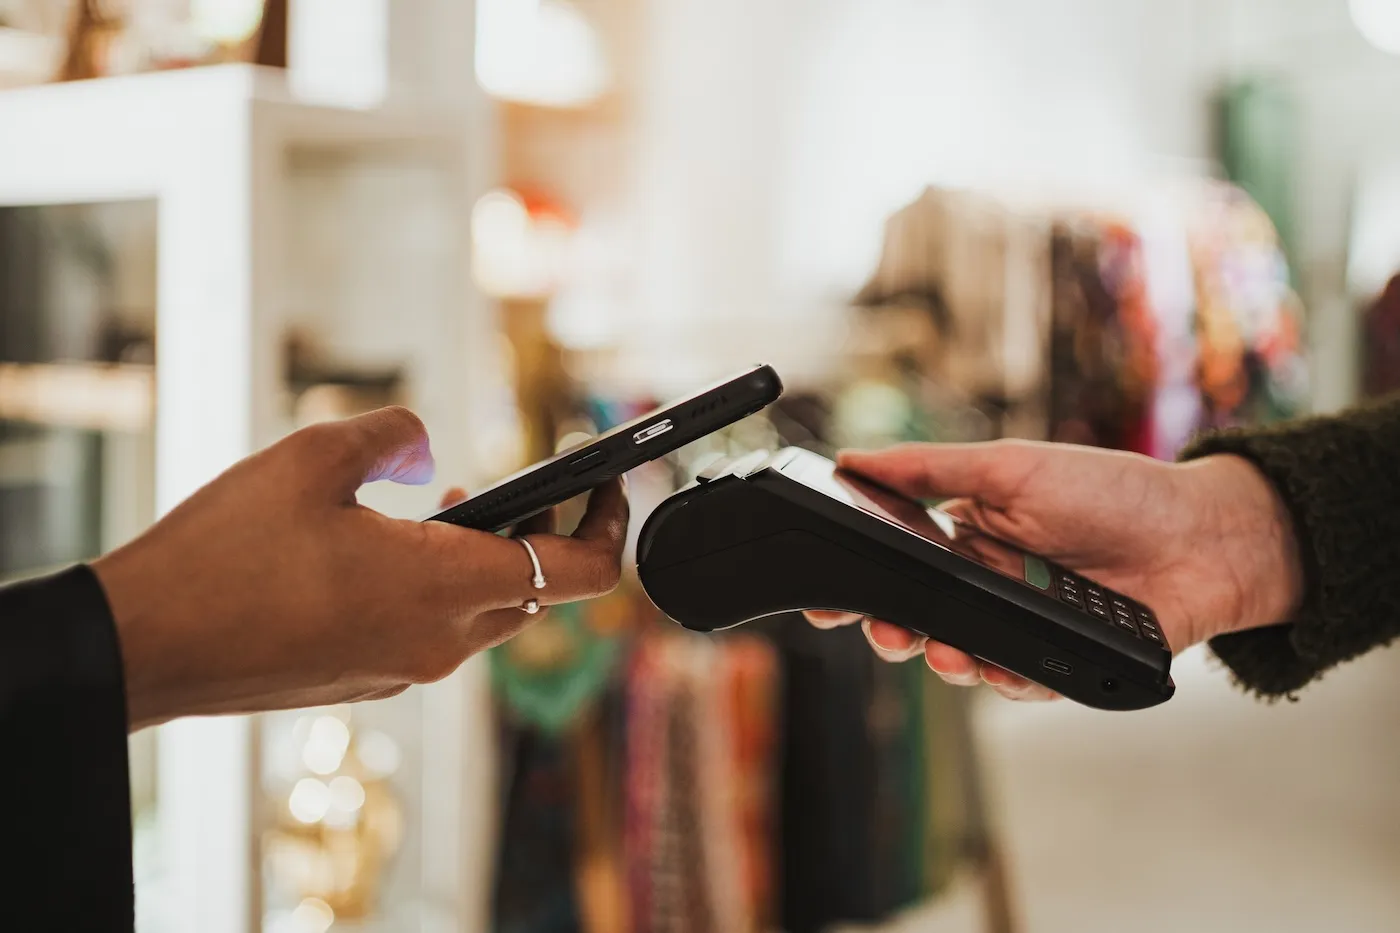
Online shopping is convenient, but it can also put your personal information at risk—especially if a retail site experiences a data breach. Virtual credit cards can make online shopping more secure. It's considered a safe payment option that puts an additional barrier between your credit card number and identity thieves.
What Is a Virtual Credit Card?
A virtual credit card is a temporary generated number that's linked to your regular credit card. You can use it to make purchases online without having to enter the number printed on your credit card. The transaction will go through normally, and your credit card will be charged, but your real card number will never be never exposed.
The way a virtual credit card number works can vary from one credit card company to the next:
- Some virtual credit cards can only be used at specific online stores.
- Others can be used at any online retailer that accepts your regular credit card.
- You may be issued a virtual credit card number that can only be used one time.
How to Get a Virtual Credit Card
Check with your credit card company to see if they issue virtual credit card numbers. If so, they can likely link one to your existing account. They might do this through an internet browser extension that automatically generates a virtual number at checkout. Alternatively, you might be able to log in to your online account and generate virtual credit card numbers as needed.
Keep in mind that not all accounts are eligible for virtual numbers. If you already have credit cards, you can contact your issuers to see if the feature is available for your accounts. Also check to see if your credit cards are compatible with digital wallets, which can make in-person and online transactions more secure.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
Credit One Bank® American Express® for Rebuilding Credit
Ongoing APR:29.74% Variable
Annual Fee:$75 First year. $99 thereafter, billed monthly at $8.25
American Express® Gold Card
Ongoing APR:See Pay Over Time APR
Annual Fee:$325
AT&T Points Plus® Card from Citi
Ongoing APR:19.74% - 27.74% (Variable)
Annual Fee:$0
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Annual Fee:$75 first year; then $99/year
Hilton Honors American Express Surpass® Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$150
Marriott Bonvoy Bevy® American Express® Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$250
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Annual Fee:$75*
Bank of America® Customized Cash Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.74% - 27.74% Variable
Annual Fee:$0
See all our best credit cards for 2026.
Do Virtual Credit Cards Help Keep Your Information Safe?
Virtual credit card numbers can help keep your information safe by protecting your account information from fraudsters—and making it harder for them to access your account. If a virtual card number gets in the wrong hands, it'll be worthless if it's already been used and deactivated.
Even if someone makes unauthorized charges, you won't have to go through the hassle of replacing your credit card and updating your payment information with accounts or merchants that have your card on file. All you have to do is report the unapproved transactions to your credit card company. You'll never be responsible for more than $50 in fraudulent credit card charges, thanks to the Fair Credit Billing Act. Your liability may be less than that, depending on your credit card issuer.
Pros and Cons of Virtual Credit Cards
Pros
- You'll have added security when shopping online. This can help protect your personal information.
- It's easier to combat unauthorized charges. If your regular credit card number is stolen, it could result in a much larger financial headache.
- Creating a virtual credit card number is relatively easy. Apps and built-in web extensions can make it automatic.
Cons
- Not all credit cards are eligible for virtual numbers. You may have to contact your issuer to see if it's an option for any of your existing credit cards.
- Virtual credit card numbers can have limited usefulness. They are generally limited to online or phone transactions, not in-person purchases. Digital wallets can be used in person, however.
- Getting a refund might be more complicated. If you're seeking a refund on a purchase you made with a virtual credit card number that has since expired, you may have to settle for store credit.
Additional Ways to Protect Your Information When Shopping Online
Here are some other ways to keep your information safe when shopping online:
- Don't shop on public Wi-Fi networks. These unsecured networks make it easier for fraudsters to tap into your personal information. Do your online shopping at home, or use a virtual private network (VPN) connection in public places.
- Pay with your credit card. Debit cards tend to offer fewer fraud protections. If there are unauthorized charges, you may not be reimbursed for 100% of your losses.
- Only shop with secure websites: Be sure the website starts with "https" (not "http"). That indicates that you're using a secure connection. You can also look for a lock icon in your web browser that signals you're using a secure website.
The Bottom Line
Virtual credit cards are designed for online shopping and provide an extra layer of security—making it harder for cyber attackers to gain access to your personal information. You can contact your credit card issuers to see if it's an option for any of your accounts.
Virtual credit cards are designed to prevent fraud, which can help protect your credit health. Free credit monitoring with Experian has the same end goal. You'll get an alert whenever something new appears on your credit report. That could give you a heads up if you've been the victim of identity theft.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author

Marianne Hayes
Marianne Hayes is a longtime freelance writer who's been covering personal finance for nearly a decade. She specializes in everything from debt management and budgeting to investing and saving. Marianne has written for CNBC, Redbook, Cosmopolitan, Good Housekeeping and more.
Read more from Marianne