
 By Tim Maxwell
What’s the Minimum Age for an Authorized User?
By Tim Maxwell
Quick Answer
Authorized users can be added to an account at various ages, depending on the credit card company. The minimum age for authorized users ranges from 13 to 18, and some issuers don’t specify any age requirement.
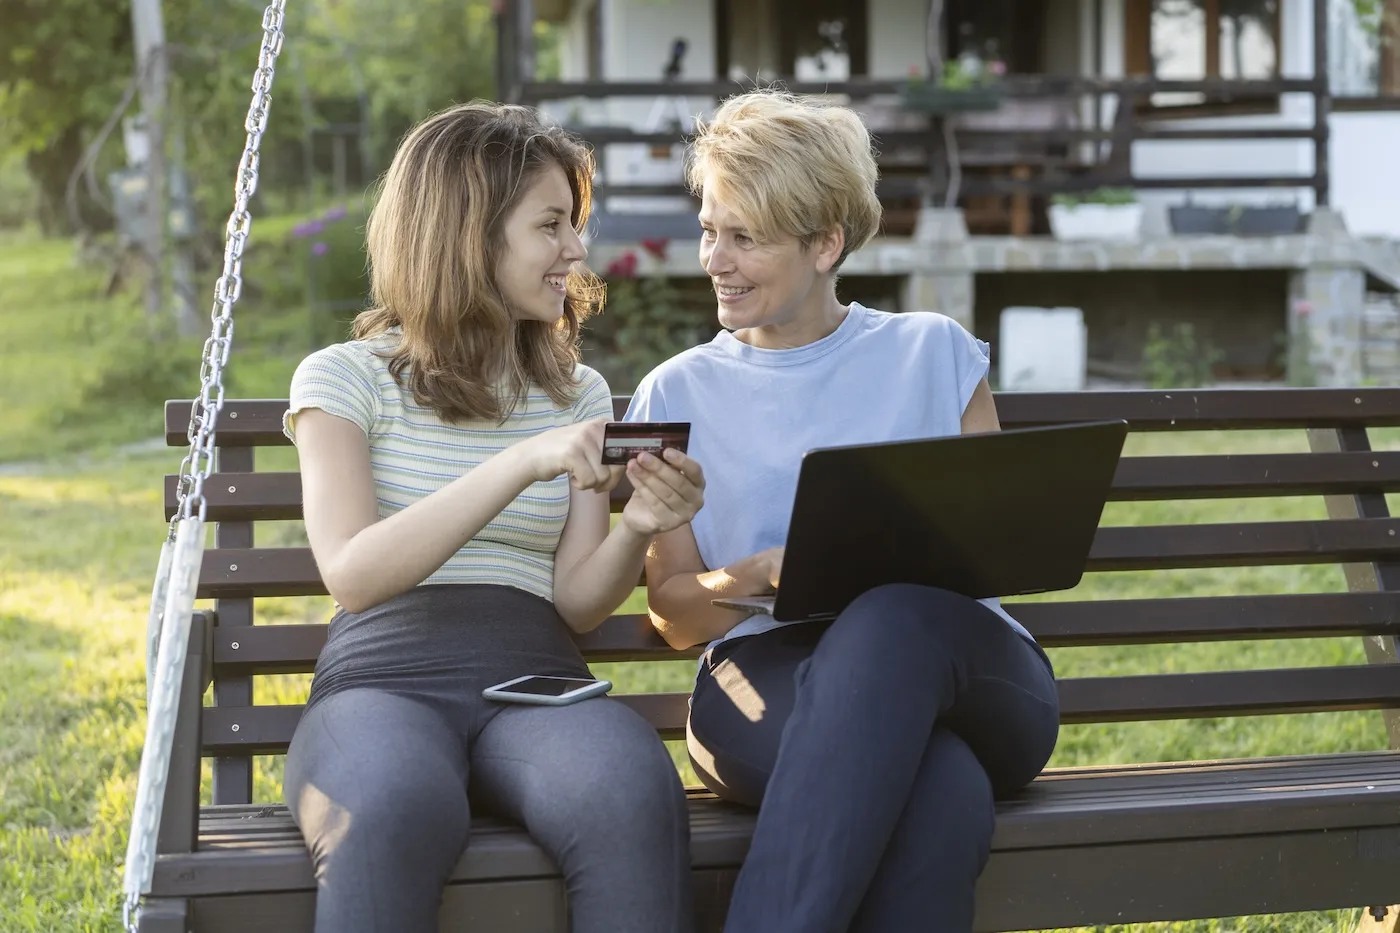
Teaching your children smart money skills to prepare them for the decisions they'll make as adults is one of the greatest gifts you can give them. From budgeting and saving to investing and understanding debt, these lessons can equip your young adult with the essential knowledge they need to navigate their finances in the future.
Along those lines, you might want to teach your child how to handle credit responsibly by adding them as an authorized user on your credit card. But be aware, card issuers may require authorized users to meet an age requirement. The minimum age to be a credit card authorized user varies from 13 to 18, and some issuers have no minimum age requirement.
Minimum Age to Be a Credit Card Authorized User
While you must be 18 years or older to get a credit card of your own, your child may meet a card issuer's minimum age requirement to become an authorized user much earlier. If you want to add an authorized user to your credit card, consider these minimum age requirements from some of the most popular credit card companies:
| Credit Card Issuer | Minimum Authorized User Age |
|---|---|
| American Express | 13 |
| Bank of America | Not specified |
| Capital One | Not specified |
| Chase | Not specified |
| Citi | Not specified |
| Discover | 15 |
| U.S. Bank | 13 |
| Wells Fargo | 18 |
As you can see, credit card authorized users generally must be at least 13, but some issuers have different age requirements, and many don't specify any age requirements.
Often, young authorized users are family members or trusted friends looking to build their credit, as the credit card's history is added to their credit report. Some parents add a teenage child as an authorized user to help them build credit before turning 18 and potentially living on their own.
How Much Does It Cost to Add an Authorized User?
In many cases, there's no cost to add an authorized user to your credit card, particularly if your card has no annual fee. However, many premium cards charge a fee to add an authorized user, which could be $75 or more. Before proceeding, contact your card issuer or refer to your card member agreement to confirm any authorized user fees.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
Wells Fargo Reflect® Card
Intro APR:0% intro APR for 21 months from account opening on purchases and qualifying balance transfers
Ongoing APR:17.49%, 23.99%, or 28.24% Variable APR
Rewards:
N/A
Annual Fee:$0
American Airlines AAdvantage® MileUp® Card
Intro APR:0% for 15 months on Balance Transfers
Ongoing APR:19.49% - 29.49% (Variable)
Rewards:
2x (Miles per dollar)
Earn 2 AAdvantage® miles for each $1 spent at grocery stores, including grocery delivery services. Earn 2 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Save 25% on inflight food and beverage purchases when you use your card on American Airlines flights
Annual Fee:$0
Citi Strata Premier® Card
Intro bonus:
60,000 Points
Earn 60,000 bonus ThankYou® Points after spending $4,000 in the first 3 months of account opening, redeemable for $600 in gift cards or travel rewards at thankyou.com.
Ongoing APR:19.49% - 27.49% (Variable)
Rewards:
1x - 10x (Points per dollar)
Earn 10 Points per $1 spent on Hotels, Car Rentals, and Attractions booked on CitiTravel.com. Earn 3 Points per $1 on Air Travel and Other Hotel Purchases, at Restaurants, Supermarkets, Gas and EV Charging Stations. Earn 1 Point per $1 spent on all other purchases.
Annual Fee:$95
Citi® / AAdvantage® Globe™ Mastercard®
Ongoing APR:19.49% - 29.49% (Variable)
Rewards:
1x - 6x (Miles per dollar)
Earn 6 AAdvantage® miles for every $1 spent on eligible hotels booked through aadvantagehotels.com. Earn 3 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Earn 2 AAdvantage® miles for every $1 spent at restaurants, including takeout and delivery. Earn 1 AAdvantage® miles for every $1 spent on all other purchases.
Annual Fee:$350
Credit One Bank® Platinum Rewards Visa® Card
Ongoing APR:29.74% Variable
Rewards:
1% (cash back)
Earn 1% cash back rewards on eligible gas, grocery purchases and mobile phone service, internet, cable and satellite TV services, terms apply
Annual Fee:$39
Hilton Honors American Express Surpass® Card
Intro bonus:
130,000 Points
Earn 130,000 Bonus Points plus a Free Night Reward after you spend $3,000 in purchases on the Hilton Honors American Express Surpass® Card in the first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.49%-28.49% Variable
Rewards:
3x - 12x (Points per dollar)
Earn 12X Hilton Honors Bonus Points for each dollar of eligible purchases charged on your Card directly with a hotel or resort within the Hilton portfolio. Earn 6X Hilton Honors Bonus Points for each dollar of eligible purchases on your Card at U.S. restaurants, at U.S. supermarkets, and at U.S. gas stations. Earn 4X Hilton Honors Bonus Points for each dollar of U.S. Online Retail purchases. Earn 3X Hilton Honors Bonus Points for all other eligible purchases on your Card.
Annual Fee:$150
Avant® Cashback Rewards Mastercard®
Ongoing APR:29.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$0*
Bank of America® Premium Rewards® credit card
Intro bonus:
60,000 Points
Receive 60,000 online bonus points - a $600 value - after you make at least $4,000 in purchases in the first 90 days of account opening.
Ongoing APR:19.49% - 27.49% Variable
Rewards:
1.5x - 2x (Points per dollar)
2 points for every $1 spent on travel and dining purchases, 1.5 points for every $1 spent on all other purchases
Annual Fee:$95
See all our best credit cards for 2026.
Should You Add Your Child as an Authorized User?
Managing a credit card is a serious responsibility, so exercise caution when considering adding your child as an authorized user. Use your best judgment and only consider adding a young authorized user when you're certain they can handle the responsibility. Remember, you'll be ultimately responsible for paying the bill: Authorized users are not responsible for payment, regardless of how much they charge on the card.
If you're considering this path, it's best to do so as part of your child's broader financial education when they understand the importance of savings and avoiding unnecessary debt. For this reason, it's probably best not to add a young child as an authorized user, even if you don't give them access to the card. A young person's teenage and college years may be a more appropriate time to develop financial skills, including managing credit.
Benefits of Adding Your Child as an Authorized User
Still, there are benefits of adding your kid as an authorized user, such as:
- Learning responsible money habits: Authorized users can charge purchases to your credit card (if you allow it). Under your supervision, your young cardholder can learn how to pay off charges on time each month without incurring interest.
- Establishing credit: As long as you've managed your credit card account responsibly, adding your child as a user can help them establish credit. Your full account history is added to their credit reports when they're included on your account, or at age 18 with some card issuers.
- Earning rewards: If you have a rewards credit card, any eligible purchases your child makes on the credit card will earn rewards. While these may be small purchases, any rewards you earn add up over time. This perk could be valuable if you need to meet a spending requirement for a welcome bonus or more points for a discounted trip.
- Accessing emergency funds: A credit card can come in handy in emergencies, especially for older children. If your teen's car unexpectedly breaks down, for instance, their credit card could pay for repairs to get the car back on the road.
Giving a credit card to a child may seem risky, but you can take steps to limit your risk. For example, your card issuer may allow you to set a limit as low as $200 for authorized users to reduce the potential for high spending. That way, your child can learn how to build and manage credit responsibly before venturing out on their own.
Set a Positive Credit Example for Your Child
Adding your child as an authorized user on your credit card may help them build their credit, but it could be adversely affected if you carry a high balance and thus have a high credit utilization ratio. As such, lead by example and make sure your account and your credit are in good shape. Show your child how paying the account balance in full and on time each month helps avoid interest charges while building a positive credit history.
It's also a good habit to monitor your credit regularly to stay on top of it and track your efforts to improve your credit score. Following these practices may help you strengthen your financial health while teaching your child responsible credit habits.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author
Tim Maxwell
Tim Maxwell is a former television news journalist turned personal finance writer and credit card expert with over two decades of media experience. His work has been published in Bankrate, Fox Business, Washington Post, USA Today, The Balance, MarketWatch and others. He is also the founder of the personal finance website Incomist.
Read more from Tim