
 By John Egan
What Is an EMV Chip?
By John Egan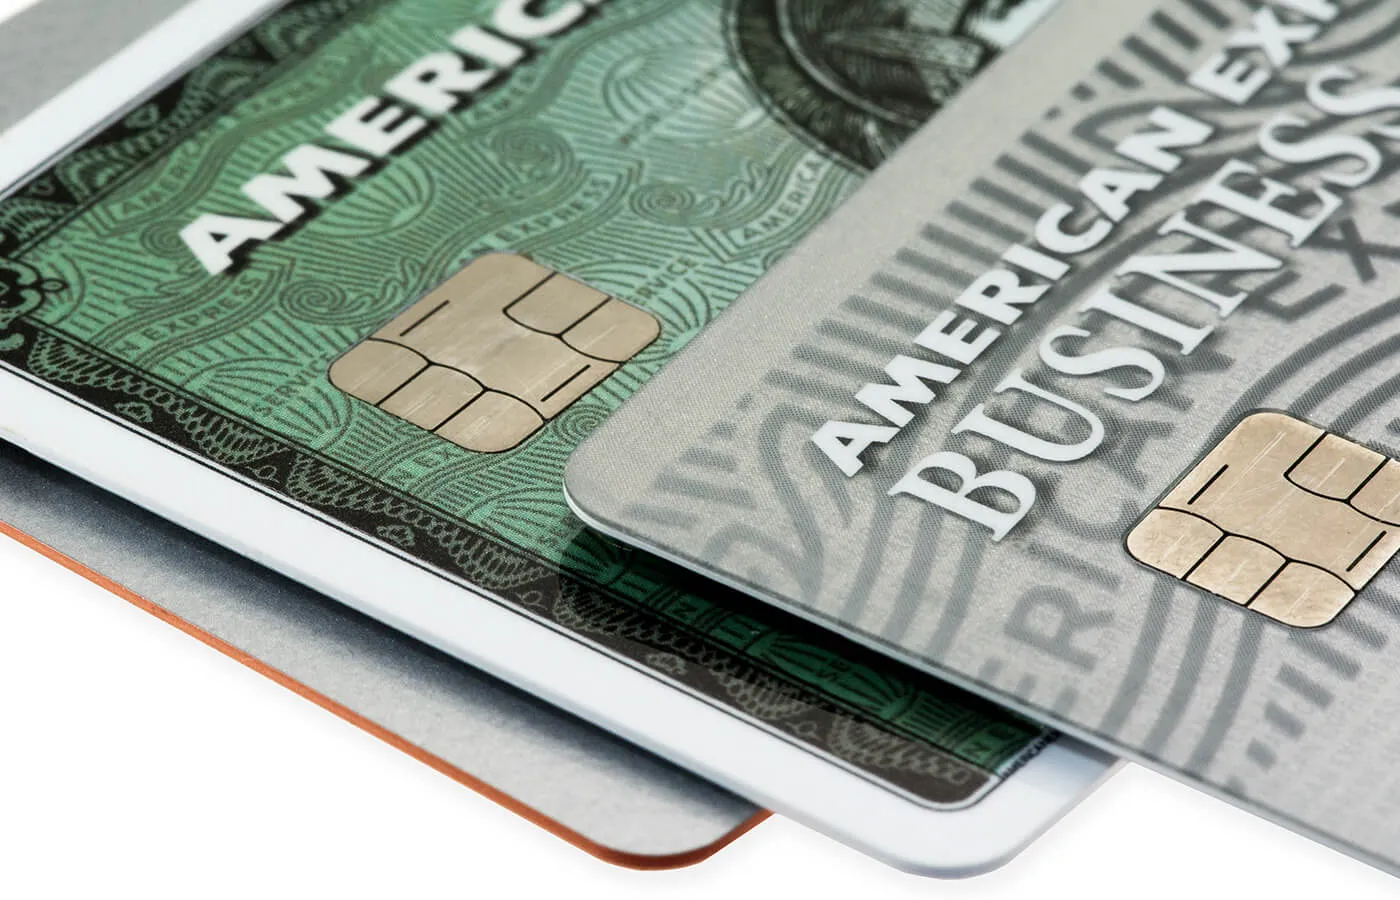
If you have a credit, debit or prepaid card, there's a good chance it has an EMV chip. EMV chips are the small, square computer chips that appear on debit, credit and prepaid cards to help safeguard them against fraud. EMV (which stands for Europay, Mastercard and Visa) chips create a one-of-a-kind code for each credit transaction.
The use of EMV chips is on the rise, with the technology showing up on close to 11 billion cards worldwide as of early 2021. Here's what you need to know about how EMV chips work and how to avoid scams that use them.
How EMV Chip Cards Work
EMV chips transmit data just as magnetic strips on cards transmit data. However, payment terminals don't read EMV chips the same way they read magnetic strips.
A card with an EMV chip typically must be inserted into the slot of a payment terminal, which then reads the chip's data and verifies the card as authentic. You then must wait for the purchase to be authorized. This process is known as "dipping."
By contrast, making a purchase by sliding a card with a magnetic strip through a card reader is called "swiping." The magnetic strip also transmits data that enables authorization of a purchase and verification of a card. A swiped transaction may be a bit quicker than a dipped transaction, but it's not quite as secure.
One key difference between an EMV card and a magnetic strip card is that the EMV card produces a unique code for each transaction but the magnetic strip does not. As such, it's harder for fraudsters to steal data to produce counterfeit cards. That's why merchants and card issuers prefer EMV transactions, even though they are more complicated than magnetic strip transactions.
Most cards in the U.S. depend on chip-and-signature capabilities. In this type of transaction, a cardholder must provide a signature to complete a transaction. Outside the U.S., chip-and-PIN transactions are more common. In these transactions, a cardholder enters a four-digit PIN to validate a payment. Chip-and-PIN transactions are considered more secure than chip-and-signature transactions.
Another way to use an EMV card is as a contactless payment method. If the card has this capability, you can tap it on a payment terminal or wave it near the terminal to complete the transaction. A contactless transaction doesn't require a PIN.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
Wells Fargo Reflect® Card
Intro APR:0% intro APR for 21 months from account opening on purchases and qualifying balance transfers
Ongoing APR:17.74%, 24.24%, or 28.49% Variable APR
Rewards:
N/A
Annual Fee:$0
Opensky® Secured Visa® Credit Builder
Ongoing APR:24.14% Variable
Rewards:
10% (cash back)
Earn up to 10% cash back on purchases made with your opensky Secured Visa Credit Card at 40,000+ retailers. Visit opensky Rewards in the opensky app for participating retailers. Learn more at openskycc.com. See Rewards Terms and Conditions for more information.
Annual Fee:$35
Citi Strata Premier® Card
Intro bonus:
60,000 Points
Earn 60,000 bonus ThankYou® Points after spending $4,000 in the first 3 months of account opening, redeemable for $600 in gift cards or travel rewards at thankyou.com.
Ongoing APR:19.74% - 27.74% (Variable)
Rewards:
1x - 10x (Points per dollar)
Earn 10 Points per $1 spent on Hotels, Car Rentals, and Attractions booked on CitiTravel.com. Earn 3 Points per $1 on Air Travel and Other Hotel Purchases, at Restaurants, Supermarkets, Gas and EV Charging Stations. Earn 1 Point per $1 spent on all other purchases.
Annual Fee:$95
Costco Anywhere Visa® Card by Citi
Ongoing APR:18.99% - 26.99% (Variable)
Rewards:
1% - 5% (cash back)
Earn 5% cash back rewards on gas at Costco and earn 4% cash back on other eligible gas and electric vehicle (EV) charging purchases for the first $7,000 combined spend per year, and then 1% thereafter. 3% cash back on restaurants and eligible travel purchases and eligible travel, including Costco Travel. 2% cash back on all other purchases from Costco and Costco.com. 1% cash back on all other purchases.
Annual Fee:$0
Citi® / AAdvantage® Globe™ Mastercard®
Ongoing APR:19.74% - 29.74% (Variable)
Rewards:
1x - 6x (Miles per dollar)
Earn 6 AAdvantage® miles for every $1 spent on eligible hotels booked through aadvantagehotels.com. Earn 3 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Earn 2 AAdvantage® miles for every $1 spent at restaurants, including takeout and delivery. Earn 1 AAdvantage® miles for every $1 spent on all other purchases.
Annual Fee:$350
Delta SkyMiles® Reserve American Express Card
Intro bonus:
Earn 2 Delta Comfort Flight Certificates + 50K Miles
Earn two domestic Delta Comfort Flight Certificates + 50,000 Bonus Miles after $10,000 in purchases on your new Card in your first 6 months. A 21+ day advance purchase required. Taxes and fees up to $80 per person apply. Terms and other restrictions apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 3x (Miles per dollar)
Earn 3X Miles on Delta purchases and earn 1X Miles on all other eligible purchases.
Annual Fee:$650
Citi Simplicity® Card
Intro APR:0% intro APR for 18 months from account opening on purchases and qualifying balance transfers
Ongoing APR:17.74% - 28.49% (Variable)
Rewards:
N/A
Annual Fee:$0
BankAmericard® secured credit card
Ongoing APR:26.24% Variable
Rewards:
N/A
Annual Fee:$0
See all our best credit cards for 2026.
What if a Merchant Doesn't Accept EMV Cards?
EMV chip cards still come with magnetic strips, so you should be able to use an EMV card even if a merchant doesn't have the equipment required for EMV transactions.
You also may be able to use a digital wallet. Some apps store credit card information electronically, letting you pull up a digital card on a smartphone and tap the phone on a payment terminal to complete a transaction.
Watch Out for EMV Chip Scams
While EMV chip cards have helped slash payment fraud, they haven't stopped crooks from committing card-related crimes. Today, thieves are targeting EMV cards through a scam known as "card shimming."
Employing this technique, a scammer inserts a thin device called a shim into a card reader that accepts EMV cards. This device copies and stores data from your card. A scammer can't produce another chip card with this information—however, they can produce a magnetic strip card with the data stolen from the EMV card.
To avoid being victimized by an EMV chip scam, take advantage of mobile payment apps or contactless tap-and-go functions when you're making a transaction.
The Bottom Line
To head off problems that may arise when credit card information or other personal information is compromised, enroll in free credit monitoring from Experian to help you quickly detect potential fraud. If you suspect you've been the victim of an EMV chip scam, contact your card issuer right away to report it. Checking your free Experian credit report can also alert you to suspicious activity related to your credit.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author
John Egan
John Egan is a freelance writer, editor and content marketing strategist in Austin, Texas. His work has been published by outlets such as CreditCards.com, Bankrate, Credit Karma, LendingTree, PolicyGenius, HuffPost, National Real Estate Investor and Urban Land.
Read more from John