Report
Published February 22, 2022
Commercial Commercial Insights Credit & Economic TrendsThe fourth quarter of 2021 enhanced the pressure felt by small businesses as the largest wave of COVID-19 hit the US. In addition to the effects of pandemic outbreak of labor and consumer engagement, an inflationary surge, largest increase since 1982, coupled with pandemic-related supply-and-demand imbalances, weighed heavily on US small businesses along with a notable impact to consumer sentiment.
Although workers were getting raises in the currently tight job market, rapid price increases are eroding consumers' earning power. Average wage earnings went up by 4.0% in Q4 '21 vs. the previous year, yet a 7.5% increase in inflation results in a net decline in real earnings. Workers' money is not going as far as it used to. Rising wages, however, put pressure on businesses' payrolls who may be forced to pass those costs to consumers.
Complete the form to access the report
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Thank you for your interest
Your free Experian resource is now available. Enjoy!
 Report
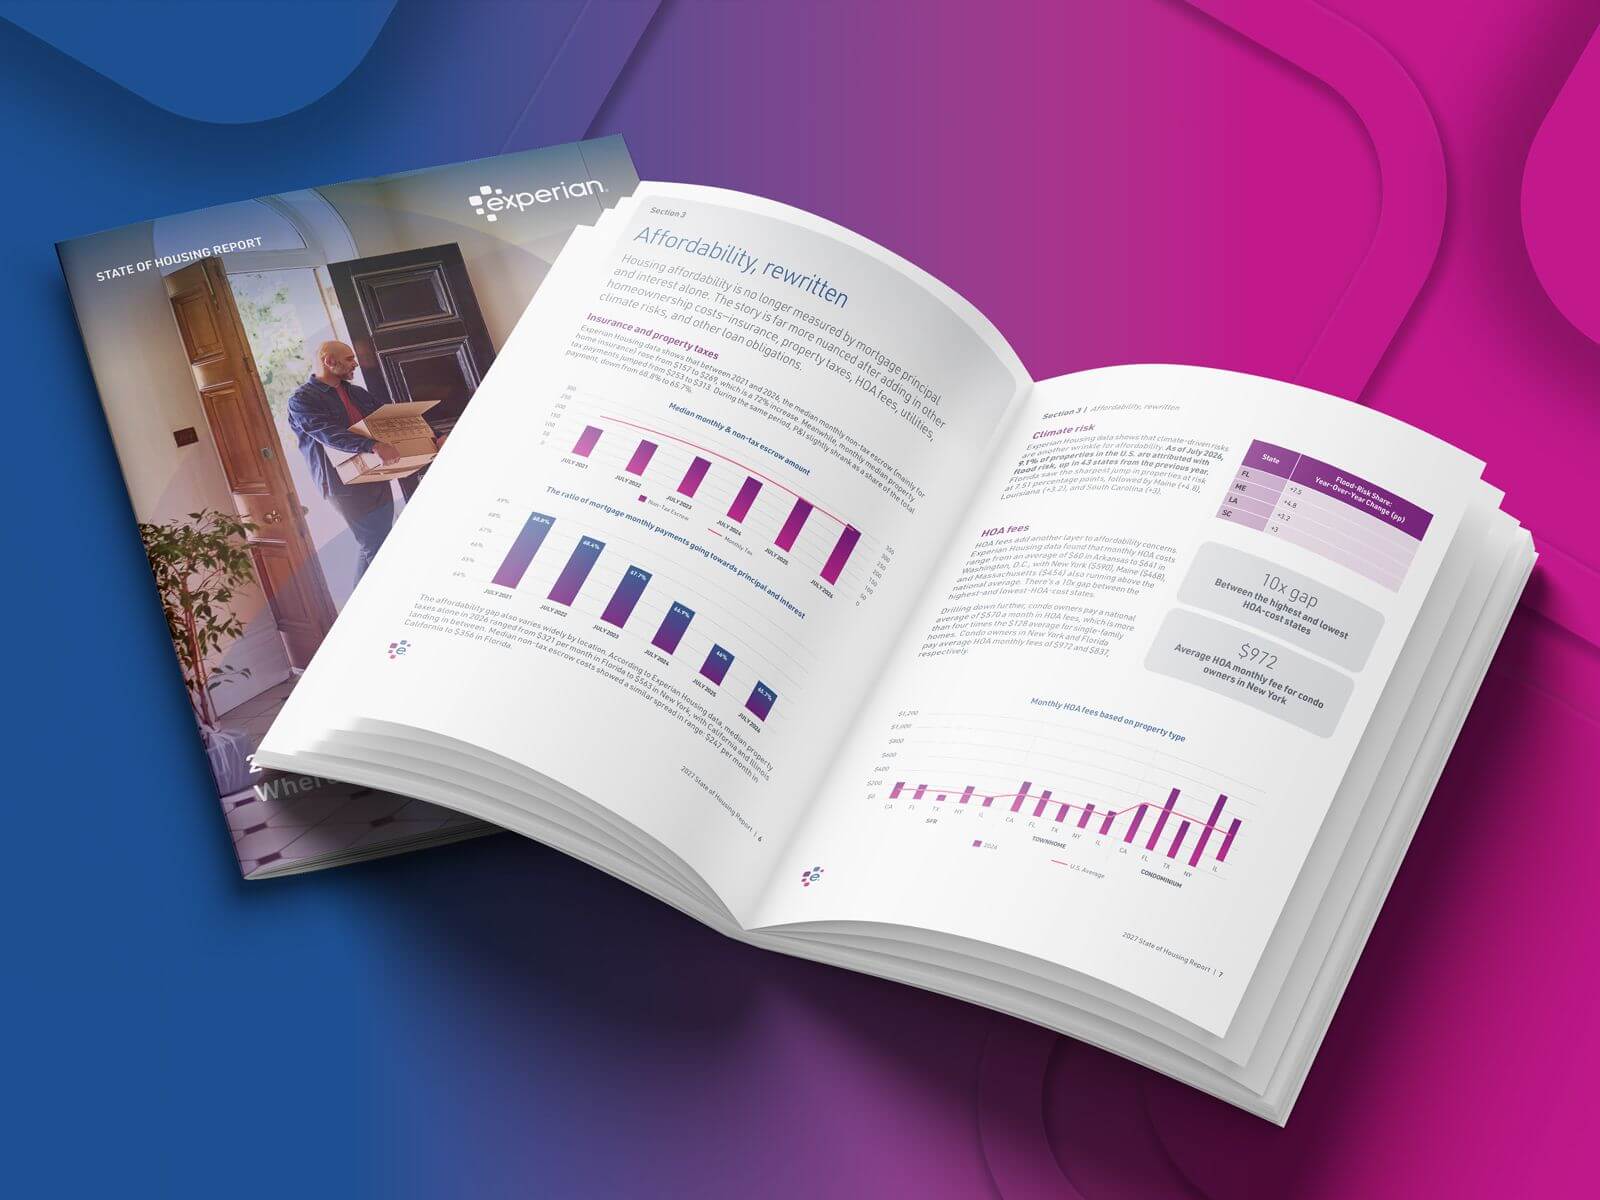
2027 State of the U.S. Housing Market Report
The U.S. housing market may begin to thaw in 2027, but improvement won't be universal. Changing affordability, borrower readiness, household finances and property-level costs will shape where opportunity emerges and who is positioned to act.
Experian's 2027 State of the U.S. Housing Market Report takes a closer look at the consumer, financial, and market signals behind these shifts, helping lenders look beyond national averages to understand where housing opportunity may be emerging, for whom, and under what conditions.
Inside the report
Explore the trends and data shaping the 2027 housing market, including:
- Mortgage demand and borrower readiness
- The true cost of homeownership
- Regional market conditions
- Household financial resilience
- Home equity and lending opportunity
- Renter sentiment and future demand
- Economic and consumer trends
 Webinar
Reducing Mortgage Friction: How Income & Employment Verification is Evolving in 2026
In today’s competitive mortgage market, lenders are challenged to reduce origination costs, improve operational efficiency, and create a better borrower experience. This webinar explores how the Experian Verify Preview Report gives lenders visibility into employment and income record availability before ordering a full Verification of Income and Employment (VOIE) report. By providing transparency upfront, lenders can reduce unnecessary verification expenses, improve operational efficiency, and make more informed sourcing decisions.
What we’ll cover:
- How to determine record availability before ordering a full income and employment verification report
- Strategies for reducing unnecessary verification spending while improving operational efficiency
- Ways to improve borrower experience, accelerate loan processing, and reduce lender workload through smarter verification workflows
- How verification innovation supports broader mortgage automation and data-driven decisioning initiatives
 Webinar
Commercial construction risk isn't generic. Your score shouldn't be either.
Most commercial risk models are designed to assess every industry. Construction operates by a different set of rules. Explore the data, research, and analytics behind Experian's first construction-specific score and learn how trade creditors can improve risk visibility, credit decisions, and portfolio performance.
 Webinar
Q3 2026 Macroeconomic Scenarios Forecast
Explore Experian's Q3 2026 U.S. economic outlook and scenarios forecasts.
- See GDP projections for 2026 and 2027.
- Understand the outlook for inflation and unemployment.
- Review expectations for Federal Reserve interest rates.
- Compare base-case, optimistic and pessimistic scenarios.