 Edited by Samuel Mountjoy
Will Removing Myself as an Authorized User Help My Credit?
Edited by Samuel Mountjoy
Quick Answer
- Removing yourself as an authorized user can help your credit if the primary account holder makes late payments or maintains a high balance.
- Leaving the account may also hurt your credit if the account was the oldest one on your credit report.
Removing yourself as an authorized user on a credit card could help your credit, depending on how the account is being managed.
When the primary account holder demonstrates responsible credit behavior, like making all payments on time and keeping credit utilization low, your credit will generally benefit. But if they pay credit card bills late or the card has a consistently high balance, your credit may suffer—or not improve at the rate you'd like it to.
Here's how to know if it's time to remove yourself as an authorized user on another person's credit card.
How Removing Yourself as an Authorized User Could Affect Your Credit
Removing yourself as an authorized user will eliminate a credit account from your credit report, which could have either a positive or a negative impact on your credit score. The precise effect will depend on whether the primary account holder has sound credit management, and whether you have other accounts in your name.
Here are some potential positive effects:
- Removal of late payments: If the person whose account you've chosen to join makes credit card payments late or not at all, those negative items could negatively affect your credit. Experian doesn't include negative information, including late payments, on authorized users' credit reports, but other credit reports might, which could affect scores based on those reports. As a result, removing yourself from the account could benefit you.
- Removal of high debt balances: Perhaps the primary account holder consistently maintains high credit utilization, meaning their credit card balance is a high percentage of the card's credit limit. Removing yourself from the account could give you the chance to prioritize keeping credit utilization below 10% on all credit cards in your name, which can help you achieve high credit scores.
Alternatively, negative impacts could include:
- Thin credit file: If you have no credit history, becoming an authorized user on a trusted person's credit card lets you build credit without having to apply for a card in your own name. When the account holder makes payments on time and keeps balances low, your affiliation is likely to help your credit. That means that when you don't have many other active credit cards or loans in your own name, removing yourself as an authorized user could leave you with a thin credit file and limited accounts with which to calculate a credit score.
- Credit score drop: Particularly if the primary accountholder was a responsible manager of credit, the removal of the account from your credit file could lead to a drop in your credit score. You'll lose on-time payment history, your length of credit history will shorten, and your overall credit utilization could increase, since your available credit will decline.
Learn more: What Is an Authorized User on a Credit Card?
Get your FICO® ScoreΘ for free
Sign up and get instant online access to your FICO® Score for free.
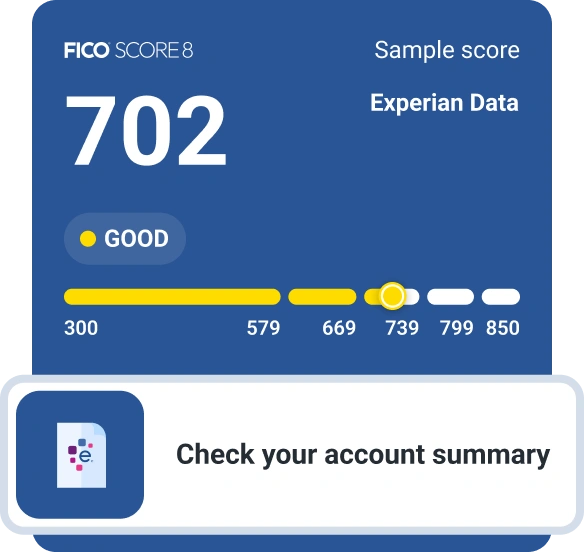
Checking your own credit won’t lower your credit scores.
View specific factors that are affecting your score and how to improve it.
When to Remove Yourself as an Authorized User
Here's when to consider ending your affiliation with the primary cardholder's account:
- The account owner misses payments. The biggest red flag when you're an authorized user is when the account holder makes even one late or missed payment. A single credit card payment made 30 days late can seriously damage their credit score, and might affect yours, too, depending on how the credit bureaus treat authorized user account activity. When they miss one payment, there's likely a higher chance they'll miss more in the future.
- The primary user has high credit utilization. Credit utilization above 30% can start to damage credit scores—and the ideal credit utilization rate to aim for is under 10%. That means that when the card's credit limit is $5,000, the card's balance shouldn't climb past $500 at any time. If you know the primary account holder gets close to maxing out the card—or doesn't seem to pay attention to their credit utilization throughout the month—that's a sign to remove yourself as an authorized user.
- Your relationship with the primary account holder has changed. Perhaps the primary cardholder was your spouse or partner and the relationship has ended, or you want to otherwise distance yourself from them. These are sound reasons to remove yourself as an authorized user and look for other ways to build credit on your own.
- Your credit hasn't noticeably improved. It may turn out that your status as an authorized user isn't benefiting you as much as you expected, and pursuing other credit-building methods are more helpful. Perhaps the card issuer doesn't report your payment history to all the credit bureaus, or the account is not old enough to provide you with a longer credit history (more on that below).
If you decide to leave the account as an authorized user, consider signing up for a credit-builder loan or a secured credit card instead. Both of these let you build credit in your own name, rather than adding someone else's credit history to yours.
How to Remove Yourself From an Account
You're generally able to remove yourself as an authorized user by calling the credit card issuer and requesting the change. You may also be able to ask to remove yourself from the account online, depending on the company.
The account will no longer appear on your credit report, and its activity will not be factored into your credit scores. That also means that your length of credit history, which constitutes 15% of your FICO® ScoreΘ, will be affected. In other words, if the credit card you were attached to was the oldest account on your report, your credit history will be shorter without it. But that's a worthwhile change if the account was poorly managed otherwise; late payments have a larger effect on your creditworthiness than length of history.
Making Sure You've Been Removed as an Authorized User
To double-check that you've successfully removed yourself as an authorized user, check your credit report. All accounts in your name, or that you're connected to—including car loans, student loans, credit cards and mortgages—will appear there.
If you've asked the appropriate credit issuer to be removed from the account yet it's still showing up on your credit report, you have the right to contact each credit bureau individually and dispute the inaccuracy. Explain that you are no longer an authorized user and request that all activity going back to the day you were removed from the account be struck from your credit report.
The Bottom Line
The potential perks of being an authorized user are big, but so are the pitfalls. To avoid disappointment, and jeopardized credit, pick your primary account holder carefully. Then pay close attention to their account usage and payment history. If it's time to cut ties, know that there are other options for getting started with or improving credit. Removing yourself as an authorized user when necessary is a step toward thoughtful, vigilant financial proficiency.
What makes a good FICO® Score?
Learn what it takes to achieve a good credit score. Review your FICO® Score for free and see what’s helping and hurting your score.
Get your FICO® ScoreNo credit card required

About the author

Brianna McGurran
Brianna McGurran is a freelance journalist and writing teacher based in Brooklyn, New York. Most recently, she was a staff writer and spokesperson at the personal finance website NerdWallet, where she wrote "Ask Brianna," a financial advice column syndicated by the Associated Press.
Read more from Brianna