Case Study
Published April 3, 2020
Fintech Credit & Economic Trends MarketingLearn how home equity lender, Spring EQ, leveraged Experian Boost™, which captures the value of consumer's utility and telecom trade lines, to help applicants near approval or risk thresholds qualify for better loan terms and conditions.
Complete the form to access the case study
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Thank you for your interest
Your free Experian resource is now available. Enjoy!
 Report
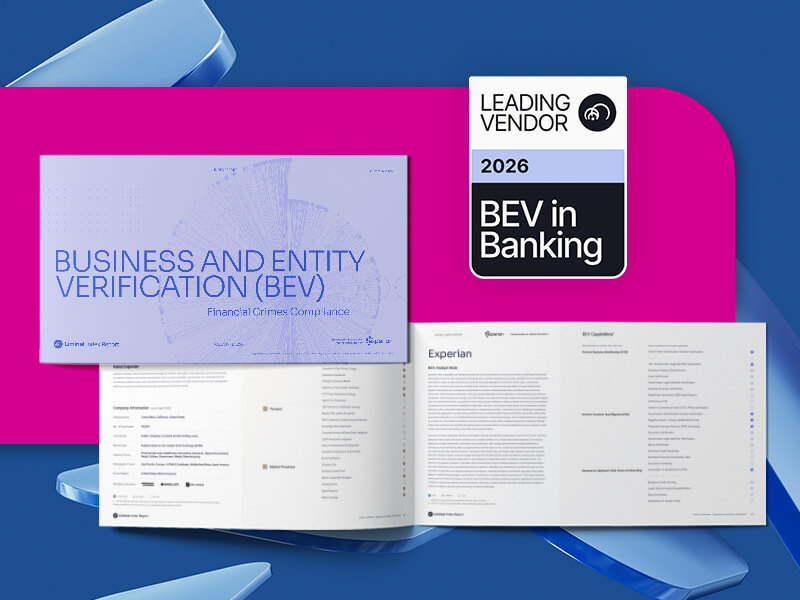
Liminal 2026 Business and Entity Verification (BEV) Index Report - Licensed for distribution by Experian
Experian was named a leading BEV vendor for 2026. Liminal assessed 86 vendors and examined the challenges banks face when verifying businesses and their owners.
Download the report to explore:
- Why 40% of banks name identifying beneficial owners as their biggest verification challenge.
- Why 87.5% of banks prefer one broad financial crime platform over standalone business verification tools.
- How credit assessment and ongoing monitoring are coming together in business verification.
About this report: The Liminal 2026 Business and Entity Verification (BEV) Index Report was researched and written by Liminal. Liminal evaluated 86 vendors and named 19 as Leading Vendors. Experian is one of the 19. Leading Vendor status is not a ranking, and the report does not mean Liminal endorses any one company over another.
Experian is a licensed distributor of this report. Experian did not commission, sponsor or fund it.
Learn more about the Liminal Index at Liminal. KYB Providers Index 2026 | Liminal
Copyright 2026 Liminal Strategy, Inc. Reproduced under license. Used with permission.
 Webinar
Data Strategies for Smarter Tribal Lending Decisions
As Tribal lending evolves, understanding how consumer behavior, credit demand and portfolio performance are shifting is becoming increasingly important for effective risk strategy.
- Examine emerging credit and consumer trends across Tribal lending
- Understand where risk and growth opportunities are shifting
- Explore how more specialized data and analytics can improve risk differentiation
- Consider how purpose-built scoring can support more informed lending decisions
 Webinar
Modernizing mortgage underwriting with better data
See how evolving credit scores, alternative data, and verification tools could help lenders improve the mortgage process and expand access to homeownership.
In this HousingWire conversation, Allison LaForgia speaks with Michele Bodda, Group President of Experian Housing, Verification Solutions and Employer Services. Bodda discusses how lenders can put modern credit scoring and consumer data to work in underwriting today.
Watch the video to hear about:
• Using alternative credit data to better represent consumers with limited traditional credit histories
• Bringing the right information into the underwriting process at the right time
• How Power Profile Plus lets lenders request another score later in the process without repurchasing the underlying credit data
• Experian’s investment in income and employment verification, including its partnership with Workday
• Opportunities to improve efficiency and help more people pursue homeownership
 Report
Credit Card Market Growth Chartbook: Q2 2026
Explore credit card market trends through Q2 2026, including changes in originations, issuer performance and consumer segments.
- Track secured and unsecured credit card growth.
- Compare national banks, regional banks, credit unions, fintechs and subprime issuers.
- Examine origination trends by credit score and generation.