White Paper
Published July 1, 2025
Housing Advanced Analytics & Modeling Data Sources Marketing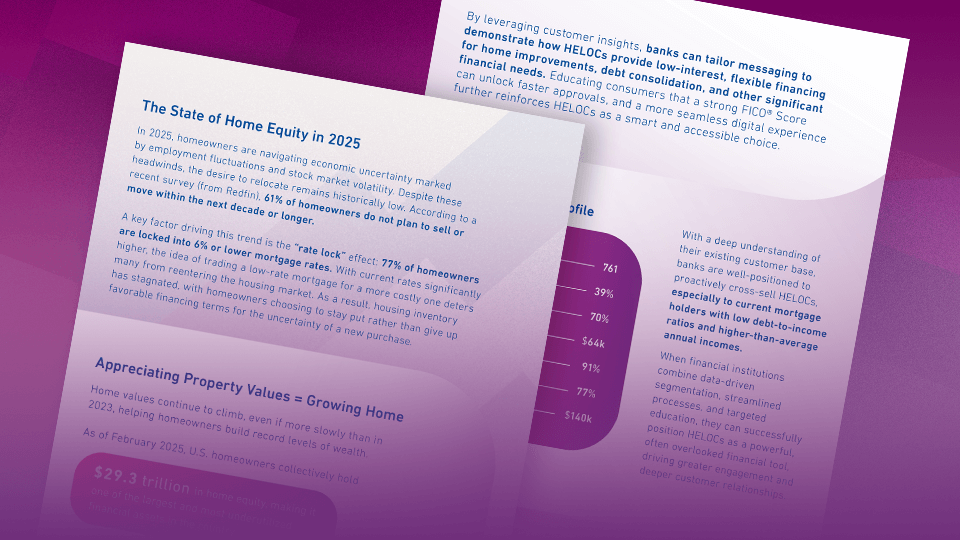
This white paper explores the transformative potential of Home Equity Lines of Credit (HELOCs) in 2025, a year marked by record-high homeowner equity and shifting consumer credit behavior. It offers data-driven insights into how lenders can tap into the $29 trillion in untapped equity by leveraging advanced analytics, behavioral segmentation, and digital innovation to meet evolving borrower needs.
Key Takeaways:
- $29T in Untapped Equity: Millions of homeowners are ideal HELOC candidates but remain underserved.
- Behavior Gap: Many consumers default to credit cards due to misconceptions about HELOCs.
- Smart Targeting: Use data to identify Revolvers and tailor offers that resonate.
- Digital Advantage: Compete with fintechs by streamlining approvals and closings.
Complete the form to access the white paper
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Thank you for your interest
Your free Experian resource is now available. Enjoy!
 Webinar
Modernizing mortgage underwriting with better data
See how evolving credit scores, alternative data, and verification tools could help lenders improve the mortgage process and expand access to homeownership.
In this HousingWire conversation, Allison LaForgia speaks with Michele Bodda, Group President of Experian Housing, Verification Solutions and Employer Services. Bodda discusses how lenders can put modern credit scoring and consumer data to work in underwriting today.
Watch the video to hear about:
• Using alternative credit data to better represent consumers with limited traditional credit histories
• Bringing the right information into the underwriting process at the right time
• How Power Profile Plus lets lenders request another score later in the process without repurchasing the underlying credit data
• Experian’s investment in income and employment verification, including its partnership with Workday
• Opportunities to improve efficiency and help more people pursue homeownership
 Webinar
Experian’s Ryan Rosales on Improving Verification Speed and Borrower Experience
In this episode of the Chrisman Commentary, we explore why income and employment verification are reaching a turning point for mortgage lenders and borrowers alike. Ryan Rosales discusses how new data sources, including Experian Verify’s integration with Workday, are helping move the industry beyond the traditional choice between a few verification providers and cumbersome manual documentation. Tune in to hear how greater competition, expanded data coverage, real-time verification, and a more open ecosystem could reduce borrower friction, lower lender costs, and potentially reshape the future of mortgage origination.
 Report
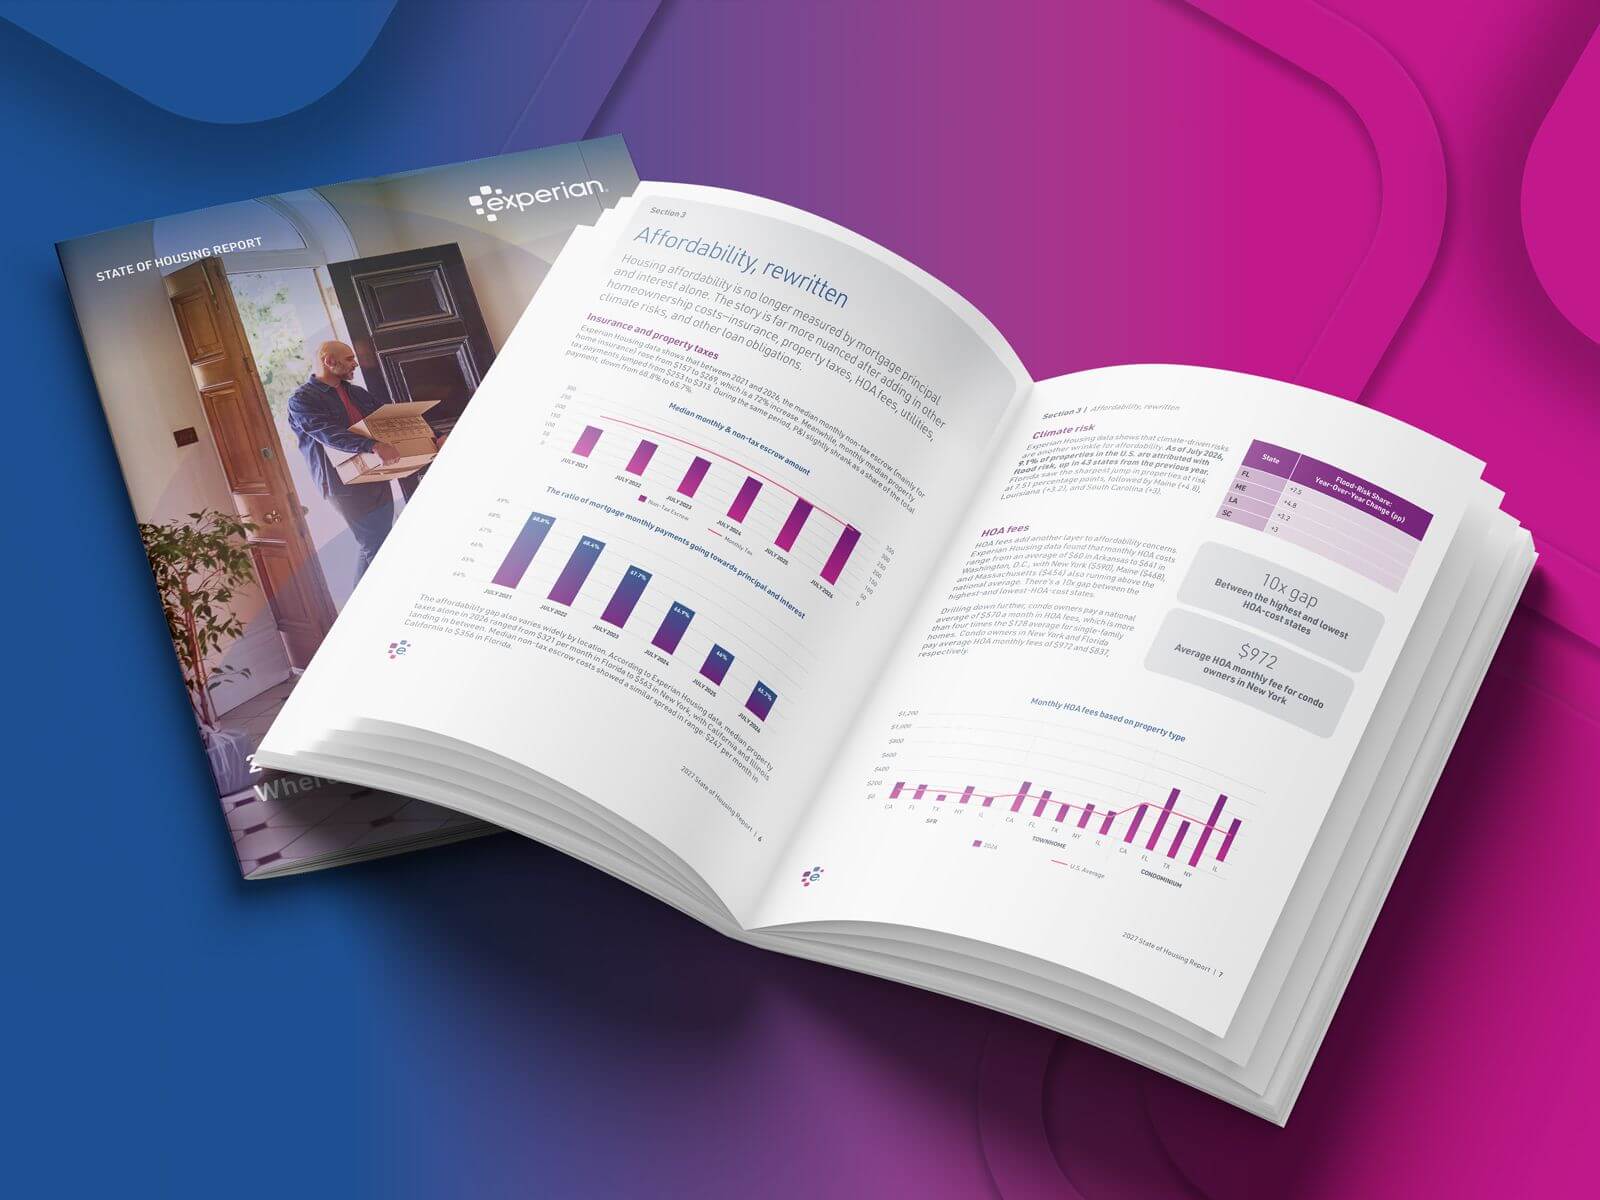
2027 State of the U.S. Housing Market Report
The U.S. housing market may begin to thaw in 2027, but improvement won't be universal. Changing affordability, borrower readiness, household finances and property-level costs will shape where opportunity emerges and who is positioned to act.
Experian's 2027 State of the U.S. Housing Market Report takes a closer look at the consumer, financial, and market signals behind these shifts, helping lenders look beyond national averages to understand where housing opportunity may be emerging, for whom, and under what conditions.
Inside the report
Explore the trends and data shaping the 2027 housing market, including:
- Mortgage demand and borrower readiness
- The true cost of homeownership
- Regional market conditions
- Household financial resilience
- Home equity and lending opportunity
- Renter sentiment and future demand
- Economic and consumer trends
 Webinar
AI in Lending: From Experimentation to Execution
Explore research on what financial institutions need to move AI initiatives forward responsibly.
- Understand the data and governance barriers slowing AI adoption
- See where lenders are investing to strengthen AI foundations
- Learn why data lineage, explainability and trust matter for scale
- Explore how connected intelligence can support modern lending