Modern credit scoring built for today’s mortgage market
Mortgage lenders need more than a point-in-time view of a borrower’s credit profile.
VantageScore 4.0 uses trended credit data, advanced modeling techniques, and broader scoreability, evaluating traditional credit data alongside non-traditional or alternative data sources, including rent, utility, and telecom payments, to help lenders assess credit risk with greater depth and precision.
VantageScore 4.0 provides a more inclusive and predictive approach to credit scoring, by incorporating richer behavioral information, including changes in balances, utilization and payments over time. The model also expands the population that can receive a score, giving lenders greater insight into applicants with limited, new or dormant credit histories and helping support more informed credit decisions.
The form below is for business inquiries only.
If you’re a consumer looking for help, please visit the consumer assistance page.
We are unable to address personal credit report and/or membership inquiries via this business form. Visit Experian.com/help or call 888-397-3742 for consumer assistance. For help with your business credit report, please visit Experian.com/small-business.
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
24 Months of Borrower Behavior
VantageScore 4.0 incorporates 24 months of trended credit data, helping lenders evaluate the trajectory of borrower behavior rather than relying only on a single snapshot in time.
See More Than a Snapshot
Traditional credit data provides important information about where a borrower stands today. VantageScore 4.0 adds another dimension by evaluating how credit behavior has changed over time.
VantageScore 4.0 evaluates traditional credit data alongside non-traditional or alternative data sources, including rent, utility and telecom payments, providing a broader view of consumer creditworthiness.
Trended credit data adds further context by capturing patterns in consumer credit behavior over time, including:
- Changes in balances
- Changes in credit utilization
- Payment amounts relative to amounts due
- Increases or decreases in balances over time
- Borrower payment behavior across multiple months
The model uses these behavioral trajectories to provide a more complete view of credit performance. For mortgage lenders, this can help distinguish between borrowers who may look similar at a single point in time but whose financial behaviors are moving in very different directions.
Strong Mortgage Predictive Performance
VantageScore 4.0 was designed to improve predictive performance across lending categories, including mortgage originations.
In more recent performance analysis using data from June 2020 through June 2022, VantageScore 4.0 demonstrated strong mortgage origination performance and improved its ability to capture higher-risk accounts compared with VantageScore 3.0.
4.0% Lift in Mortgage Originations
Compared with VantageScore 3.0, VantageScore 4.0 demonstrated improved predictive performance for mortgage originations. In a VantageScore performance analysis, VantageScore 4.0 delivered a 4.0% performance lift, measured by the incremental share of accounts that became 90 or more days past due captured within the bottom 20% of the scored population.
This matters because effective mortgage credit scoring is not simply about assigning a score. It is about helping lenders rank risk accurately enough to make informed underwriting decisions across a broad applicant population.
Better risk differentiation can help lenders make more informed mortgage credit decisions while maintaining disciplined risk management.
Score More Consumers Without Lowering Standards
One of the most important features of VantageScore 4.0 is its ability to provide scores for consumers who may not meet the requirements of conventional scoring models.
This includes:
- Thin-file consumers with limited credit history
- Young-to-credit consumers whose credit history is still developing
- Dormant consumers who have not had a recent update to their credit file
VantageScore 4.0 uses machine learning techniques within its model development to better capture patterns in consumers with sparse or limited credit information. These capabilities help expand scoreability while preserving risk differentiation.
The model was specifically built with scorecards for consumers with thin, young and dormant credit profiles, giving lenders a way to assess applicants who may otherwise be difficult to evaluate using conventional approaches.
Broader Scoreability
VantageScore 4.0 is designed to score consumers with thin-file, young-to-credit and dormant credit histories, giving mortgage lenders a broader view of potential borrowers.
For mortgage lenders, broader scoreability can create more opportunity to evaluate applicants who may have limited traditional credit histories but still demonstrate meaningful credit behavior.
Broader scoreability means more consumers can be evaluated as VantageScore 4.0 considers non-traditional or alternative data sources—including rent, utility and telecom payments—alongside traditional credit data, while lenders remain focused on predictive risk.
Built for Consistency Across the Three National Credit Bureaus
VantageScore 4.0 uses the same model specification across Equifax, Experian and TransUnion.
This approach is designed to support more consistent score alignment across the three national credit reporting companies and give lenders greater confidence in how risk is represented across bureau sources.
Consistency matters in mortgage lending because lenders frequently rely on information from multiple credit bureaus when evaluating applicants.
One Model Across Three Bureaus
VantageScore 4.0 uses the same model specification across all three national credit bureaus, supporting more consistent risk assessment.
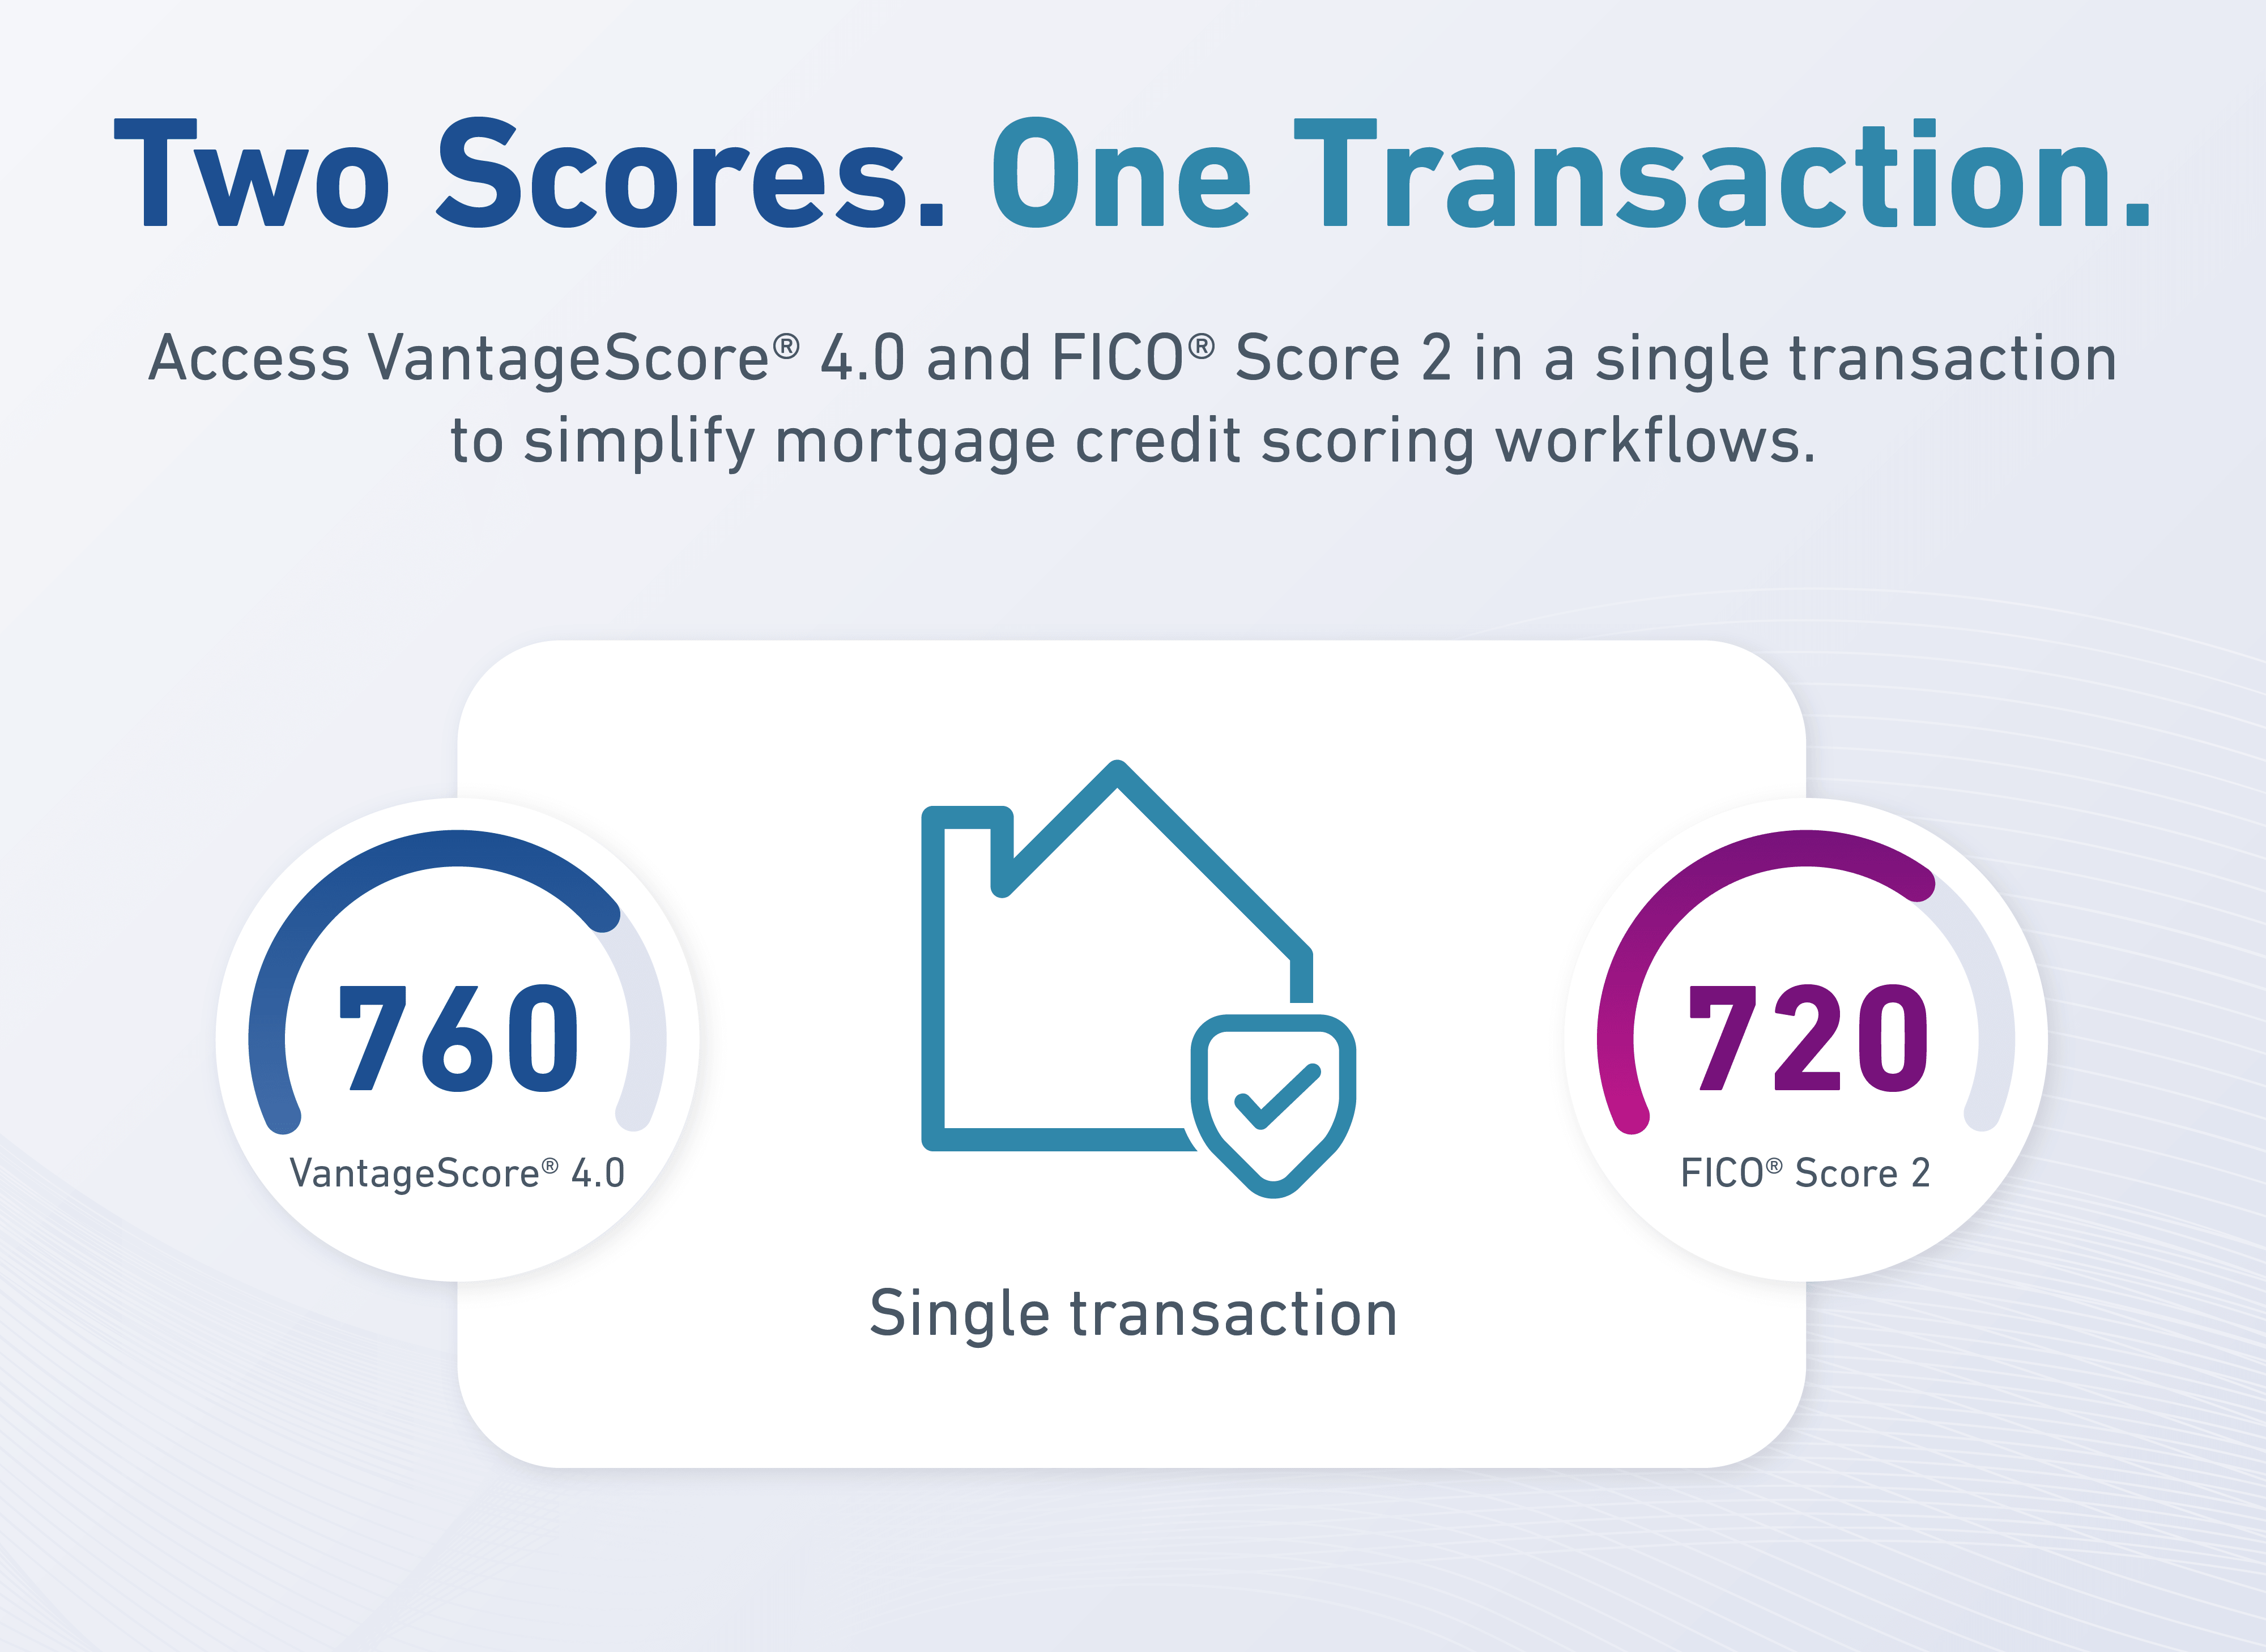
Access VantageScore 4.0 Through Experian Score Choice Bundle
Mortgage lenders can access VantageScore 4.0 through the Experian Score Choice Bundle, a first-of-its-kind mortgage credit scoring solution that brings VantageScore 4.0 and FICO® Score 2 together in a single transaction.
The bundle gives lenders more choice in mortgage credit scoring while helping simplify workflows and supporting a more transparent approach to pricing.
Frequently Asked Questions
VantageScore 4.0 is a tri-bureau credit risk model designed to help lenders rank consumers by their likelihood of default. It incorporates trended credit data, machine learning techniques and broader scoreability to provide a more complete view of borrower credit behavior.
VantageScore 4.0 gives mortgage lenders an additional way to evaluate borrower risk using behavioral trends, broader scoreability and strong mortgage-specific predictive performance. It can help lenders assess more consumers while maintaining focus on disciplined risk management.
VantageScore 4.0 combines traditional credit information with trended credit data, advanced modeling techniques and the ability to evaluate non-traditional or alternative data sources, including rent, utility and telecom payments. Together, these capabilities provide a broader view of consumer credit behavior, expand scoreability and help lenders assess credit risk with greater depth and precision.
Mortgage lenders can access VantageScore 4.0 through the Experian Score Choice Bundle, which provides VantageScore 4.0 and FICO® Score 2 in a single transaction. The bundle is designed to give lenders greater scoring flexibility while helping simplify workflows.
- Solutions
- Advanced analytics and modeling
- Collections and debt recovery
- Credit decisioning
- Credit profile reports
- Customer engagement and retention
- Data reporting and furnishing
- Data sources
- Data quality and management
- Fraud management
- Global data breach services
- Identity solutions
- Marketing solutions
- Regulatory compliance
- Risk management
- Workforce management