White Paper
Published March 10, 2026
Housing Credit Education Economic & Market Insights
Mortgage lenders face rising fallout, affordability strain, and shifting borrower expectations. This white paper explores how embedded financial wellness strengthens conversion, reduces risk, and builds long-term trust.
- Improve inquiry-to-close conversion
- Manage risk with real-time credit insights
- Address affordability pressures proactively
- Deepen engagement and drive sustainable growth
Complete the form to access the white paper
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Thank you for your interest
Your free Experian resource is now available. Enjoy!
 Report
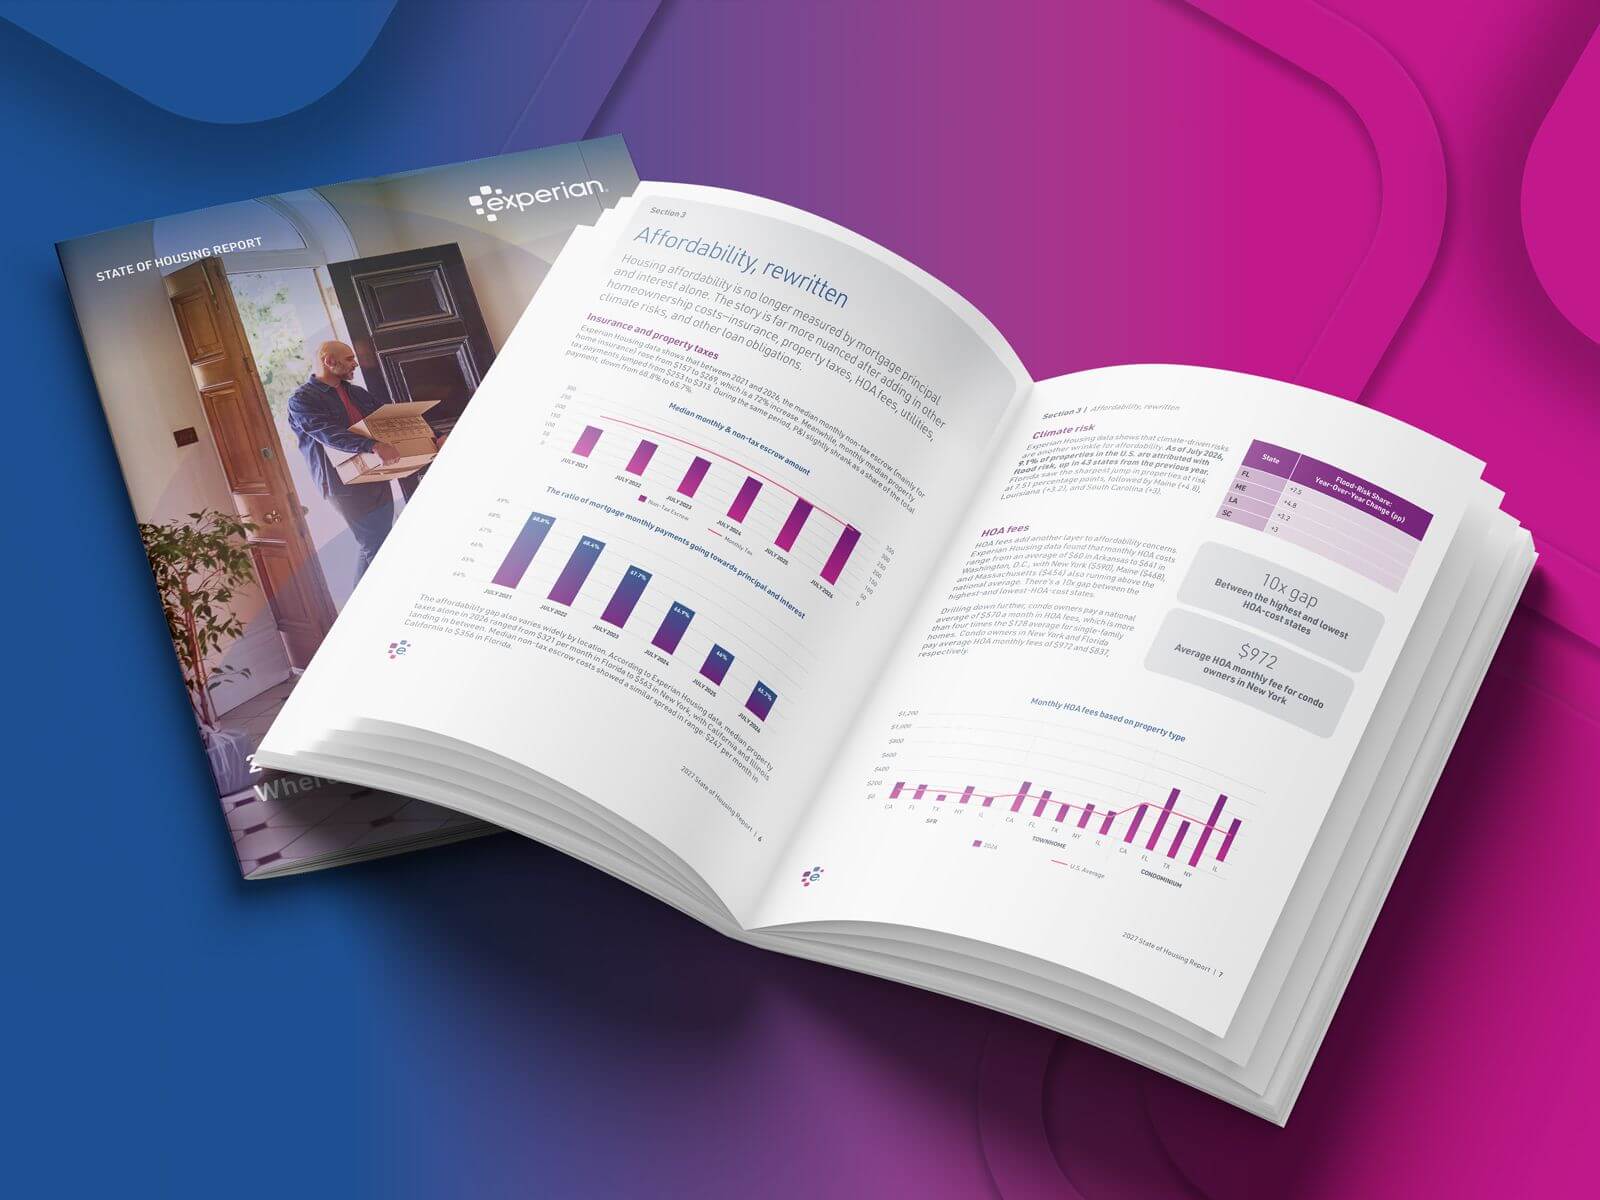
2027 State of the U.S. Housing Market Report
The U.S. housing market may begin to thaw in 2027, but improvement won't be universal. Changing affordability, borrower readiness, household finances and property-level costs will shape where opportunity emerges and who is positioned to act.
Experian's 2027 State of the U.S. Housing Market Report takes a closer look at the consumer, financial, and market signals behind these shifts, helping lenders look beyond national averages to understand where housing opportunity may be emerging, for whom, and under what conditions.
Inside the report
Explore the trends and data shaping the 2027 housing market, including:
- Mortgage demand and borrower readiness
- The true cost of homeownership
- Regional market conditions
- Household financial resilience
- Home equity and lending opportunity
- Renter sentiment and future demand
- Economic and consumer trends
 Webinar
Reducing Mortgage Friction: How Income & Employment Verification is Evolving in 2026
In today’s competitive mortgage market, lenders are challenged to reduce origination costs, improve operational efficiency, and create a better borrower experience. This webinar explores how the Experian Verify Preview Report gives lenders visibility into employment and income record availability before ordering a full Verification of Income and Employment (VOIE) report. By providing transparency upfront, lenders can reduce unnecessary verification expenses, improve operational efficiency, and make more informed sourcing decisions.
What we’ll cover:
- How to determine record availability before ordering a full income and employment verification report
- Strategies for reducing unnecessary verification spending while improving operational efficiency
- Ways to improve borrower experience, accelerate loan processing, and reduce lender workload through smarter verification workflows
- How verification innovation supports broader mortgage automation and data-driven decisioning initiatives
 Webinar
Q3 2026 Macroeconomic Scenarios Forecast
Explore Experian's Q3 2026 U.S. economic outlook and scenarios forecasts.
- See GDP projections for 2026 and 2027.
- Understand the outlook for inflation and unemployment.
- Review expectations for Federal Reserve interest rates.
- Compare base-case, optimistic and pessimistic scenarios.
 Webinar
Experian Mortgage Loan Performance Dataset + Snowflake Cortex
See how Experian’s Mortgage Loan Performance dataset on Snowflake helps teams quickly turn complex questions about mortgage portfolios into actionable insights. Explore how natural-language queries and ready-to-run analytics can support market sizing, credit risk, prepayment, escrow risk, and portfolio strategy.