Tag: analytics
Being able to explain how an ML model works and what drives its decisions is important if you want to use ML-powered models for underwriting.
For companies that regularly engage in financial transactions, having a customer identification program (CIP) is mandatory to comply with the regulations around identity verification requirements across the customer lifecycle. In this blog post, we will delve into the essentials of a customer identification program, what it entails, and why it is important for businesses to implement one. What is a customer identification program? A CIP is a set of procedures implemented by financial institutions to verify the identity of their customers. The purpose of a CIP is to be a part of a financial institution’s fraud management solutions, with similar goals as to detect and prevent fraud like money laundering, identity theft, and other fraudulent activities. The program enables financial institutions to assess the risk level associated with a particular customer and determine whether their business dealings are legitimate. An effective CIP program should check the following boxes: Confidently verify customer identities Seamless authentication Understand and anticipate customer activities Where does Know Your Customer (KYC) fit in? KYC policies must include a robust CIP across the customer lifecycle from initial onboarding through portfolio management. KYC solutions encompass the financial institution’s customer identification program, customer due diligence and ongoing monitoring. What are the requirements for a CIP? Customer identification program requirements vary depending on the type of financial institution, the type of account opened, and other factors. However, the essential components of a CIP include verifying the customer's identity using government-issued identification, obtaining and verifying the customer's address, and checking the customer against a list of known criminals, terrorists, or suspicious individuals. These measures help detect and prevent financial crimes. Why is a CIP important for businesses? CIP helps businesses mitigate risk by ensuring they have accurate and up-to-date information about their customers. This also helps financial institutions comply with laws and regulations that require them to monitor financial transactions for any suspicious activities. By having a robust CIP in place, businesses can establish trust and rapport with their customers. According to Experian’s 2024 U.S. Identity and Fraud Report, 63% of consumers say it's extremely or very important for businesses to recognize them online. Having an effective CIP in place is part of financial institutions showing their consumers that they have their best interests top of mind. Finding the right partner It’s important to find a partner you trust when working to establish processes and procedures for verifying customer identity, address, and other relevant information. Companies can also utilize specialized software that can help streamline the CIP process and ensure that it is being carried out accurately and consistently. Experian’s proprietary and partner data sources and flexible monitoring and segmentation tools allow you to resolve CIP discrepancies and fraud risk in a single step, all while keeping pace with emerging fraud threats with effective customer identification software. Putting consumers first is paramount. The security of their identity is priority one, but financial institutions must pay equal attention to their consumers’ preferences and experiences. It is not just enough to verify customer identities. Leading financial institutions will automate customer identification to reduce manual intervention and verify with a reasonable belief that the identity is valid and eligible to use the services you provide. Seamless experiences with the right amount of friction (I.e., multi-factor authentication) should also be pursued to preserve the quality of the customer experience. Putting it all together As cybersecurity threats are becoming more sophisticated, it is essential for financial institutions to protect their customerinformation and level up their fraud prevention solutions. Implementing a customer identification program is an essential component in achieving that objective. A robust CIP helps organizations detect, prevent, and deter fraudulent activities while ensuring compliance with regulatory requirements. While implementing a CIP can be complex, having a solid plan and establishing clear guidelines is the best way for companies to safeguard customer information and maintain their reputation. CIPs are an integral part of financial institutions security infrastructures and must be a business priority. By ensuring that they have accurate and up-to-date data on their customers, they can mitigate risk, establish trust, and comply with regulatory requirements. A sound CIP program can help financial institutions detect and prevent financial crimes and cyber threats while ensuring that legitimate business transactions are not disrupted, therefore safeguarding their customers' information and protecting their own reputation. Learn more
Model governance is growing increasingly important as more companies implement machine learning model deployment and AI analytics solutions into their decision-making processes. Models are used by institutions to influence business decisions and identify risks based on data analysis and forecasting. While models do increase business efficiency, they also bring their own set of unique risks. Robust model governance can help mitigate these concerns, while still maintaining efficiency and a competitive edge. What is model governance? Model governance refers to the framework your organization has in place for overseeing how you manage your development, model deployment, validation and usage.1 This can involve policies like who has access to your models, how they are tested, how new versions are rolled out or how they are monitored for accuracy and bias.2 Because models analyze data and hypotheses to make predictions, there's inherent uncertainty in their forecasts.3 This uncertainty can sometimes make them vulnerable to errors, which makes robust governance so important. Machine learning model governance in banks, for example, might include internal controls, audits, a thorough inventory of models, proper documentation, oversight and ensuring transparent policies and procedures. One significant part of model governance is ensuring your business complies with federal regulations. The Federal Reserve Board and the Office of the Comptroller of the Currency (OCC) have published guidance protocols for how models are developed, implemented and used. Financial institutions that utilize models must ensure their internal policies are consistent with these regulations. The OCC requirements for financial institutions include: Model validations at least once a year Critical review by an independent party Proper model documentation Risk assessment of models' conceptual soundness, intended performance and comparisons to actual outcomes Vigorous validation procedures that mitigate risk Why is model governance important — especially now? More and more organizations are implementing AI, machine learning and analytics into their models. This means that in order to keep up with the competition's efficiency and accuracy, your business may need complex models as well. But as these models become more sophisticated, so does the need for robust governance.3 Undetected model errors can lead to financial loss, reputation damage and a host of other serious issues. These errors can be introduced at any point from design to implementation or even after deployment via inappropriate usage of the model, drift or other issues. With model governance, your organization can understand the intricacies of all the variables that can affect your models' results, controlling production closely with even greater efficiency and accuracy. Some common issues that model governance monitors for include:2 Testing for drift to ensure that accuracy is maintained over time. Ensuring models maintain accuracy if deployed in new locations or new demographics. Providing systems to continuously audit models for speed and accuracy. Identifying biases that may unintentionally creep into the model as it analyzes and learns from data. Ensuring transparency that meets federal regulations, rather than operating within a black box. Good model governance includes documentation that explains data sources and how decisions are reached. Model governance use cases Below are just three examples of use cases for model governance that can aid in advanced analytics solutions. Credit scoring A credit risk score can be used to help banks determine the risks of loans (and whether certain loans are approved at all). Governance can catch biases early, such as unintentionally only accepting lower credit scores from certain demographics. Audits can also catch biases for the bank that might result in a qualified applicant not getting a loan they should. Interest rate risk Governance can catch if a model is making interest rate errors, such as determining that a high-risk account is actually low-risk or vice versa. Sometimes changing market conditions, like a pandemic or recession, can unintentionally introduce errors into interest rate data analysis that governance will catch. Security challenges One department in a company might be utilizing a model specifically for their demographic to increase revenue, but if another department used the same model, they might be violating regulatory compliance.4 Governance can monitor model security and usage, ensuring compliance is maintained. Why Experian? Experian® provides risk mitigation tools and objective and comprehensive model risk management expertise that can help your company implement custom models, achieve robust governance and comply with any relevant federal regulations. In addition, Experian can provide customized modeling services that provide unique analytical insights to ensure your models are tailored to your specific needs. Experian's model risk governance services utilize business consultants with tenured experience who can provide expert independent, third-party reviews of your model risk management practices. Key services include: Back-testing and benchmarking: Experian validates performance and accuracy, including utilizing statistical metrics that compare your model's performance to previous years and industry benchmarks. Sensitivity analysis: While all models have some degree of uncertainty, Experian helps ensure your models still fall within the expected ranges of stability. Stress testing: Experian's experts will perform a series of characteristic-level stress tests to determine sensitivity to small changes and extreme changes. Gap analysis and action plan: Experts will provide a comprehensive gap analysis report with best-practice recommendations, including identifying discrepancies with regulatory requirements. Traditionally, model governance can be time-consuming and challenging, with numerous internal hurdles to overcome. Utilizing Experian's business intelligence and analytics solutions, alongside its model risk management expertise, allows clients to seamlessly pass requirements and experience accelerated implementation and deployment. Experian can optimize your model governance Experian is committed to helping you optimize your model governance and risk management. Learn more here. References 1Model Governance," Open Risk Manual, accessed September 29, 2023. https://www.openriskmanual.org/wiki/Model_Governance2Lorica, Ben, Doddi, Harish, and Talby, David. "What Are Model Governance and Model Operations?" O'Reilly, June 19, 2019. https://www.oreilly.com/radar/what-are-model-governance-and-model-operations/3"Comptroller's Handbook: Model Risk Management," Office of the Comptroller of the Currency. August 2021. https://www.occ.treas.gov/publications-and-resources/publications/comptrollers-handbook/files/model-risk-management/pub-ch-model-risk.pdf4Doddi, Harish. "What is AI Model Governance?" Forbes. August 2, 2021. https://www.forbes.com/sites/forbestechcouncil/2021/08/02/what-is-ai-model-governance/?sh=5f85335f15cd
Digital transformation in banking reshapes processes, boosts innovation, and delivers personalized experiences to modern financial consumers.
Business intelligence analytics can help financial institutions optimize their decisioning and uncover safe growth opportunities.
Discover the different options and routes you can take to improve your debt collection process, enhance decisioning and maximize profitability. Read more!
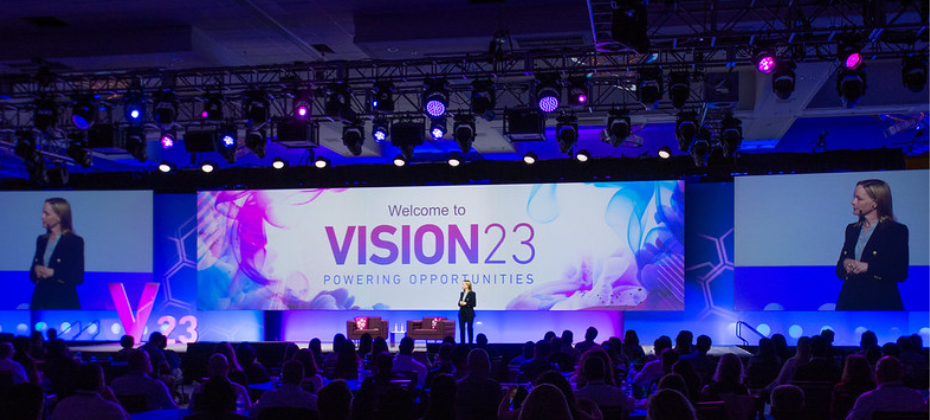
Jennifer Schulz, CEO of Experian, North America kicked off Experian’s annual Vision conference Tuesday morning pointing to data, analytics, technology and collective curiosity as the drivers for change and a more impactful tomorrow to more than 700 attendees. Keynote speaker: Jennifer Bailey Jennifer Bailey, Vice President of Apple Pay and Apple Wallet, spoke about the customer experience “ethos.” She explained how Apple takes a long-term view and values the single most important performance metric as customer experience. She said creating a seamless customer experience comes down to making things simple and understandable, and asking, “Are we solving a customer problem?” and “How are we making it easier for customers to enjoy and liver their lives. Bailey, who said of all apps she uses the weather app the most, also talked about innovation, and that both intent and making mistakes are important parts of the process. Apple’s products are known for their user-friendliness, and design is part of that. She encouraged the audience to give design teams room to create without bottom line pressures and not to be afraid to take well-considered risks. Keynote Speaker: Gary Cohn Gary Cohn, Vice Chairman of IBM, talked about the current economic climate, and while it’s a natural viewpoint to look to the past for guidance, the current environment is unlike any before. Cohn discussed regulatory compliance in the banking industry and prioritizing safety and soundness. While AI is topical and in numerous headlines recently, Cohn reminded the conference goers that AI isn’t new. He said what is new and important is that you can now teach models to find the information needed rather than having to feed all the information yourself. He believes AI is not the end of employment, but rather helps boost productivity, efficiency, and job satisfaction and provides organizations more data. As for advice for the audience, Cohn shared opportunities are in the uncomfortable zones and you have to be willing to fail in order to succeed. Session highlights – Day 1 The conference hall was buzzing with conversations, discussions and thought leadership. Overall themes that were frequently part of the conversation included seamless customer experiences, agility in face of economic changes and leveraging AI/ML into strategies. Fraud automation and preventing commercial fraud More businesses are opening than ever before and lenders and service providers need a way to determine risk from businesses who are less than a year old. There is no one-size-fits-all approach to fraud. A layered solution assesses risk and applies the correct friction to resolve the risk and pass or refer the applicant. Identity Today’s consumer wants a personalized experience and is privacy conscious. Additionally, regulators are also pushing for greater privacy. Clean rooms allow you and a partner to add data to a safe space and learn more about consumers without exposing data. The right data improves acquisition rates, identity verification and allows you to anticipate customer needs. Advanced scoring Data, models and strategy are the levers institutions are using to leverage responsible analytics to meet their objectives like safely growing existing portfolios, managing the “right” level of risk, and providing a seamless digital experience. However, the total value of a decisioning system is almost always constrained by its most rudimentary component. The panel of experts discussed their uses and goals for leveraging models and customer experience was at the top of their priorities. Recession preparedness Delinquency is on the rise and lending offers made continue to drop. Changes in the economic climate require frequent monitoring of portfolio and decisions, benchmarking against peers, updating credit models and decision strategies, and stress testing portfolio and models. Trends in credit risk management While AI at the hands of everyone is topical today, it ranked lowest on the list of trends attendees believed were impacting their business. At the top of the list? The growing demand for simpler, faster and seamless experiences. More insights from Vision to come. Follow @ExperianVision and @ExperianInsights to see more of the action.
Business leaders accross industries are using predictive analytics to make informed decisions.
Fraud mitigation is an ongoing process to identify suspected fraud quickly and manage any fallout without increasing risk.
Income and employment verification processes must be able to meet the demands of today's digital consumer. Learn how you can get it right.
Online transactions face a higher chance of being declined because face-to-face transactions come with a higher degree of confidence. Businesses who fail to address this problem run the risk of losing the customer permanently, damaging their reputation and bottom line. What can e-commerce marketplace merchants do to increase the approval rate of online payments without making fraud worse? Here are three tips: 1. Broaden access to data beyond what’s in the authorization stream. Merchants use a variety of solutions to prevent fraud and verify identities, but typically use very limited data to approve a transaction through the authorization stream between a merchant and issuer. The issuing bank often only compares the purchase data to the address listed on the card owner’s account, which can create discrepancies when a customer is trying to send an order to an alternate address from their primary home. That’s why it’s important for merchants to augment their decisioning with additional data sources to help inform the true customer risk profile. 2. Leverage capabilities that can assess risk for both the transaction and the individual behind it. Today, merchants leverage limited data including email address data, device information and other technologies in silos to augment their address verification capabilities. The challenge with these tools is that each judge the risk of a specific component of the transaction or the individual. Where integration is lacking, false positives are amplified. 3. Collaborate and share expertise and data across merchants and issuers. How can Experian help? Leveraging our multidimensional data, technical expertise and advanced analytics capabilities, we can help businesses frictionlessly authenticate valid customers, thus increasing revenue by increased approval rates, without increasing fraud or operating expenses. Only Experian, through our frictionless account ownership verification solution, can connect a payment card to a provided identity at checkout beyond a name or address match. This solution combines Experian’s vast data assets – including over 500 million credit card account numbers on file in the U.S. across 250 million consumers – with our advanced analytics capabilities to match and assess the risk of the identity attributes presented to the merchant to the identity attributes contributed by the credit card’s issuer and to Experian’s network of credit and identity inquiries. The result: Experian's patent-pending REST API simply and frictionlessly improves a merchant’s customer experience and helps increase revenue while reducing their fraud and operating expenses. Get started with Experian's account ownership verification solution now.
Experian recently announced Experian Identity and published an advertorial in American Banker outlining the integrated approach to identity that recognizes the full breadth of the company’s authoritative data solutions that help businesses better connect with their consumers in more personalized, meaningful and secure ways. The efforts address the rapidly changing definition and landscape of identity and take on the importance and needs for identity which span across the entire customer journey. From marketing to a specific consumer’s needs, to facilitating a friction-right customer experience, to protecting personal information. As such, there’s a gap for single-partner providers to help businesses navigate this change, while also putting the needs of the consumer first. “Identity data sets are constantly growing with inputs from new interactions. Many future sources of data have yet to be even conceived or developed,” said Kathleen Peters, Chief Innovation Officer, Experian Decision Analytics. “Staying ahead of the identity market curve is vital, and it requires building and continually evolving an enterprise-scale identity solution that interconnects with your own unique data and systems to create attribute-rich profiles of your customers that work across any identity application. That’s Experian Identity.” Experian Identity underscores the need businesses have to respond to increasing identity needs with interconnected, scalable technology, products and services that optimize the consumer experience. While the integrated approach announcement is new, the capability is not. Experian has been trusted for decades to secure individuals’ identity around the most important decisions in their lives – think purchasing a car or home, being identified at the doctor’s office, and more. As such, consumers remain at the center of every action. Experian Identity offers identity resolution, verification, authentication and protection, and fraud management solutions that include first- and third-party fraud, account takeover, credit card verification, identity resolution and restoration, risk-based authentication, synthetic identity protection and more. Additionally, we’ve included a special blog post introducing Experian’s identity capabilities from Kathleen Peters on the Experian Global News Blog and additional coverage. Stay tuned for more updates. Experian Global News Blog - Making Identities Personal: Experian Helps Businesses Build Consumer Trust American Banker – Making Identities Personal: Building Trust and Differentiating Your Brand Experian White Paper - Making Identities Personal For more information about Experian Identity, visit www.experian.com/identity-solutions.
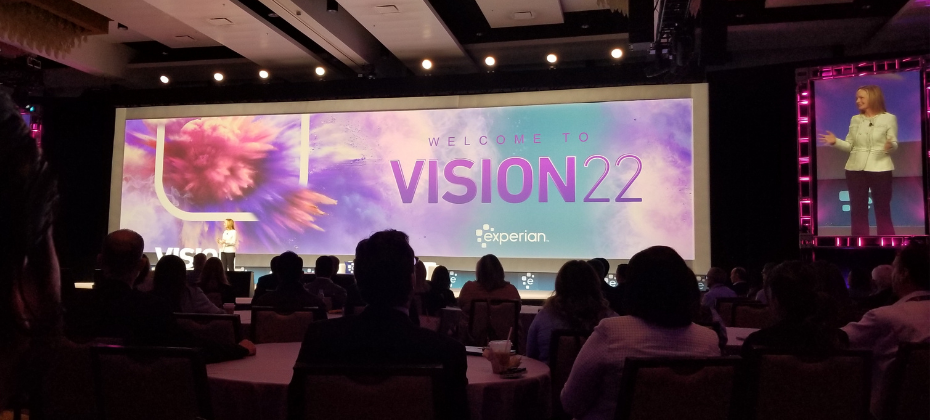
“Disruption has caused enormous amounts of innovation,” said Jennifer Schulz, CEO of Experian, North America. “We must continue to be the disruptors in our industry which takes effort, data, technology, bright minds and vision for what the future will be.” Schulz kicked off the 39th Vision conference with a future-focused keynote delivered to a crowd of more than 400 attendees. Alex Lintner, Group President, Experian Consumer Information Services, talked about the next phase of great, highlighting the digital transformation that has taken place in the generations of the past and the disruption and innovation happening today and in the future. Keynote speaker: Dr. Mohamed A. El-Erian Dr. Mohamed A. El-Erian, renowned economist and author, President of Queens’ College, Cambridge, Chief Economic Advisor at Allianz, Chair of President Obama’s Global Development Council and Former CEO and Co-Chief Investment Officer of PIMCO, spoke about the Fed, inflation, negative interest rates and the labor market, as well as the importance of inclusion. El-Erian, who said he reads the Financial Times religiously, acknowledged that we will make mistakes on the journey as we work to be even more inclusive. To navigate what’s ahead, he said we will need resilience, optionality and agility. “It’s important to connect with information, acknowledge the insecurity, in a language people understand, in order to connect,” he said. Session highlights – day 1 The conference hall was buzzing with conversations, discussions and thought leadership. Buy Now Pay Later A large audience was in attendance for a session that introduced Experian’s Buy Now Pay Later Bureau™ and explored how it’s the first and only solution of its kind — serving consumers, BNPL providers, financial institutions and regulators. Identity Identity is constantly evolving, and while biometrics and authentication may have become ubiquitous, there is much activity around the concepts of eIDs, identity wallets and identity networks. Experian is making identities personal and helping businesses to recognize, manage and connect customer identities in new ways using data, analytics and technology. Marketing In today’s hypercompetitive world, businesses need to engage the freshest data and increase velocity when it comes to time to market. An average of 120 days won’t cut it. Ascend Marketing speeds time to market and helps achieve higher ROI. Regulatory Landscape With so much happening at Capitol Hill, a panel of experts from DC discussed a number of topics and proposals (and their impacts), including the defense for risk-based pricing, the impact of suppressing negative data, and trending topics like Buy Now Pay Later and data portability. All the while, the tech showcase had a constant flow of attendees with demos ranging from data and decisioning to financial inclusion and technology. This is just the beginning. And as Schulz said, “There’s more to do.” More insights from Vision to come. Follow @ExperianVision to see more of the action.
Experian’s in-person Vision conference returns next Monday, April 11 in Los Angeles, Calif. The event is known for premier thought leadership, net-new insights and the latest and greatest in technology, innovation and data science. This year’s agenda promises to have intentional discussions around tomorrow’s trending topics including financial inclusion, buy now pay later, open banking, the future of fraud, alternative data strategies, and much more. A few spotlight sessions include: Top trends including the future application of the cloud and emerging technologies, emerging regulatory legislation and the broader implications and opportunities of DeFi. A deep dive into strategies around the targeting/marketing revolution and how to deliver in the post-COVID-19 market environments and bolster financial inclusion decisions. An introduction to Experian’s Buy Now Pay Later BureauTM, the industry’s first and only solution designed to address the needs of consumers, BNPL providers, financial institutions and regulators alike. A roundup of sessions addressing innovation in action spanning from real-time verifications, to data-driven automation, and unified platforms from data to deployment to decisioning. Several sessions highlighting future-looking strategies and solutions that leverage alternative data that can increase conversion rates while concurrently reducing risk. Multiple sessions centered on the rapidly changing identity environment and combatting emerging fraud threats. The event will also include a Tech Showcase, where attendees can get a taste of tomorrow today with more than 20 demos and the latest innovations at their fingertips. And, as always, the event features marquee keynote speakers sure to inspire. This year’s featured speakers are Dr. Mohamed A. El-Erian, President of Queens’ College, Cambridge, Chief Economic Advisor at Allianz, and Former CEO and Co-Chief Investment Officer of PIMCO; Allyson Felix, Olympic Gold Medalist, co-founder of Saysh, a footwear and lifestyle brand for women, and Right to Play and Play Works ambassador; and the closing keynote will feature actor, investor, entrepreneur and philanthropist, Ashton Kutcher. Stay tuned for additional highlights and insights on our social media platforms throughout the course of the conference. Follow Experian Insights on Twitter and LinkedIn.
There are many ways to promote a more equitable society - including financial inclusion or reducing the racial wealth gap for underserved communities.