Marketing & Acquisition
The average credit union manages between 100-300 vendor relationships, and nearly a third have no dedicated staff managing them. What was supposed to drive efficiency is stunting growth and compromising the member experience. Application volume is continuing to rise, and consumers expect a loan decision at digital speed. But for credit unions, meeting that expectation isn't the only goal. They must also continue to make the right lending decisions while also prioritizing risk management. The institutions pulling ahead aren't the ones with the most tools. They're the ones that have turned credit, fraud and decisioning into a single, coordinated system. A single loan decision touches: Credit data Identity verification Fraud signals Decisioning logic Reporting Rarely does all of that live in one place. More often, it’s stitched together across separate platforms, each with its own contract and its own support line. When a credit view and a fraud view are generated separately, they must be reconciled instead of read together in the same instant. Every handoff is a place where a decision slows down and a signal gets missed. It's why a fraud pattern that would be obvious next to the credit file often surfaces only after the funds are already gone. Fragmentation also makes it harder to optimize lending strategies over time. When data, analytics and decisioning are disconnected, credit unions have less visibility into what's working, what's changing and where strategies need to be adjusted. An integrated decisioning ecosystem closes those seams by design, with credit, fraud and lending strategy running on one platform and accessed through a single Application Programming Interface (API). Identity and compliance capabilities can be an integrated decisioning flow. The data doesn't need to be reconciled after the fact because it was never separated in the first place. Stop overengineering, start removing friction When decisioning underperforms, the instinct is to build something more custom: a proprietary model, tighter segmentation, more configuration. Custom modeling has its place for institutions with the scale and data to justify it. But often, for small or mid-sized credit unions, the bigger opportunity is a flexible decisioning strategy that uses a strong, continuously refreshed model. This shouldn't be either/or. The right approach gives credit unions a strong decisioning strategy today, with the ability to introduce more customized analytics and modeling as their needs evolve. The same principle applies to strategy management: credit unions can gain greater control through self-service capabilities as they build a more sophisticated data science team. That kind of flexibility is important as credit unions modernize their decisioning infrastructure. Research surveying more than 2,000 senior credit risk and fraud decision-makers across 11 countries found that organizations investing in unified platforms and modern infrastructure are moving faster and realizing the greatest Return on Investment (ROI). As their needs evolve, credit unions can adjust decisioning strategies without introducing another layer of technology or relying on third parties to make every change. Until self-service is the right fit, choose a partner that understands what makes your credit union’s membership and risk appetite different from others. Same member, same afternoon, faster answer Consider a credit union growing its auto and personal loan originations. A member applies for an auto loan on Saturday afternoon. Credit data, identity and fraud signals are read together in a single real-time pass instead of separate reviews: Most applications resolve immediately, approved or declined based on a more comprehensive view of the applicant. A smaller number are flagged for quick step-up verification and cleared within minutes. Only genuinely ambiguous cases reach an underwriter, who is working from one complete picture instead of reconciling multiple signals. The member has an answer before the weekend is over. The credit union books the loan before competitors even open on Monday. Built to scale This kind of process holds up today. However, the better test is whether it holds up eighteen months from now when application volume has grown, new products are live and the data flowing through the system looks nothing like it does right now. Future-proofing isn't only about handling more volume. It's about having room to be nimbler and make adjustments as quickly as the market changes. A credit union that relies on standard models within a decisioning strategy may want more customized analytics and greater control over its strategies tomorrow. Connect with us With more than three decades of credit expertise and one of the industry's largest data footprints, Experian helps credit unions do more than solve this year's friction. We're helping to build a decisioning foundation that scales, so growth becomes something the system absorbs, rather than something it must be rebuilt around. Explore More
Discover how the National Urban League and Experian partner to expand financial literacy and create economic opportunity.
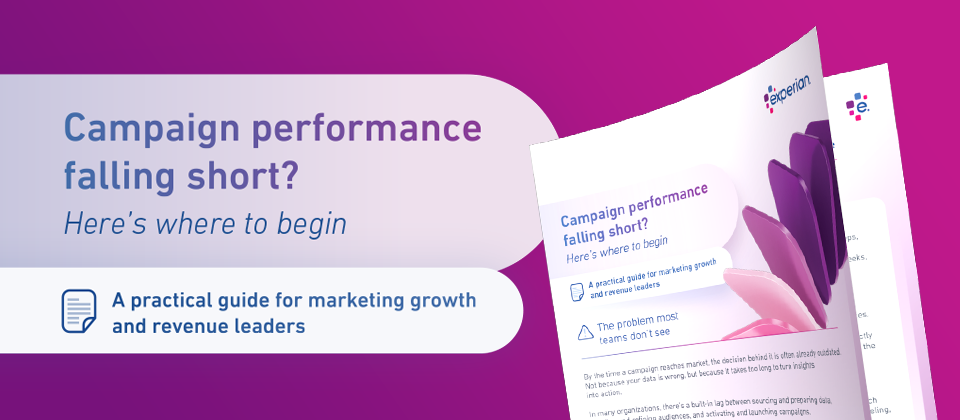
Learn how to launch campaigns faster, act on fresher insights and continuously optimize performance. Read more!
The mortgage industry is adapting to a structural shift. Experian’s 2026 State of the U.S. Housing Market Report shows a market in transition. Conventional loans account for 72% of originations, FHA 17.5% and VA 10.8% with VA showing the strongest growth from 2023 to 2025. But origination mix only tells part of the story. Beneath it lies an arguably more consequential shift: borrower expectations, affordability pressures and regulatory changes are converging. On the regulatory front, the Homebuyers Privacy Protection Act (HPPA) may reduce mortgage trigger leads and limit broad competitive outreach. As competitive visibility narrows, the lender relationship becomes more central and important beyond the closing transaction. In this environment, lenders must provide value to win, and that increasingly means financial wellness. A growing trust gap Only 34% of first mortgage hard inquiries of first mortgage hard inquiries convert into funded originations, according to Experian. That means two-thirds of borrowers who initiate the process never close. External data confirms the trend as Mortgage Bankers Association reported retail mortgage pull-through rates declined to roughly 69% in early 2025 – the lowest in over a decade – and as low as 55% among depository lenders. While pull-through can be impacted by a number of factors not influenced by the lender, when borrowers abandon applications, it can be a biproduct of uncertainty – something that the lender can influence. This is where financial wellness becomes strategic and lenders can close the trust gap by providing proactive credit visibility and guidance before underwriting friction occurs. Read more in our white paper, “The New Unlock for Mortgage.” Affordability stress While rates have eased from their 2023 highs, they remain above 6%, sustaining the lock-in effect and limiting housing supply, according to Experian’s 2026 State of the U.S. Housing Market Report. Approximately 70% of homeowners are locked into sub-6% mortgages, according to Freddie Mac. Beyond mortgage rates, increases in property taxes and non-tax escrow amounts (i.e. insurance) increase affordability pressures for consumers. Financial wellness solutions that incorporate credit monitoring, budgeting insights and cashflow visibility help borrowers understand whether they are prepared. Opportunity among millennials and Gen Z Nearly 47% of U.S. renters expect to purchase a home within four years, rising to 67% within eight years, according to Experian. This signals the time to invest in financial wellness as a differentiator, and both a growth and retention driver, is now. Financial wellness as the new unlock for mortgage Financial wellness is not an ancillary service but the foundation upon which borrower confidence, long-term engagement, conversion and risk management connect. Lenders who embed solutions like credit education, score visibility, alerts, and identity protection directly into the consumer experience can differentiate themselves from the competition above and beyond rates alone. Read more in our white paper, “The New Unlock for Mortgage.” Learn more about Experian Mortgage
Discover how Experian’s Rent Bureau and Observed Data can transform your mortgage lead strategy by predicting income, risk, and readiness earlier in the funnel—improving targeting and reducing acquisition costs.
With the Fed initiating rate reductions, the housing market is entering a new phase. Learn what mortgage lenders must know about affordability, borrower behavior, and emerging opportunities.
Direct mail is reshaping mortgage and home equity lending in 2025. See why prescreen targeting, data-driven personalization, and market exits are creating new growth opportunities for lenders.
Explore strategies to drive smarter acquisitions, deepen existing relationships and improve marketing efficiency.
With the Fed initiating rate reductions, the housing market is entering a new phase. Learn what mortgage lenders must know about affordability, borrower behavior, and emerging opportunities.
The June 2025 housing market trends report presents a nuanced view of the U.S. mortgage and home equity landscape.
Understanding generational trends and preferences is more crucial than ever, especially for the financial services industry.
Ascend Intelligence Services™ Target leverages custom response models and optimized prescreen strategies to enhance response rates.
Discover how data analytics in utilities helps energy providers navigate regulatory, economic, and operational challenges. Learn how utility analytics and advanced analytics solutions from Experian can optimize operations and enhance customer engagement.
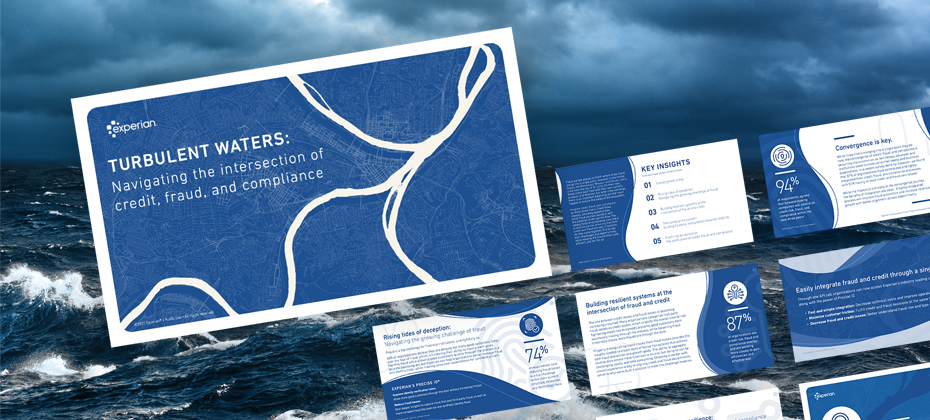
The days of managing credit risk, fraud prevention, and compliance in silos are over. As fraud threats evolve, regulatory scrutiny increases, and economic uncertainty persists, businesses need a more unified risk strategy to stay ahead. Our latest e-book, Navigating the intersection of credit, fraud, and compliance, explores why 94% of forward-looking companies expect credit, fraud, and compliance to converge within the next three years — and what that means for your business.1 Key insights include: The line between fraud and credit risk is blurring. Many organizations classify first-party fraud losses as credit losses, distorting the true risk picture. Fear of fraud is costing businesses growth. 68% of organizations say they’re denying too many good customers due to fraud concerns. A unified approach is the future. Integrating risk decisioning across credit, fraud, and compliance leads to stronger fraud detection, smarter credit risk assessments, and improved compliance. Read the full e-book to explore how an integrated risk approach can protect your business and fuel growth. Download e-book 1Research conducted by InsightAvenue on behalf of Experian
Discover how data and analytics can enhance deposit growth strategies, improve customer engagement, and drive financial wellness for banks and credit unions.