Tailoring Your Lending Strategy for Gen Y and Gen Z First-time Homebuyers

by Scott Hamlin 4 min read April 17, 2024

Click here to watch our recent webinar on first-time homebuyers.

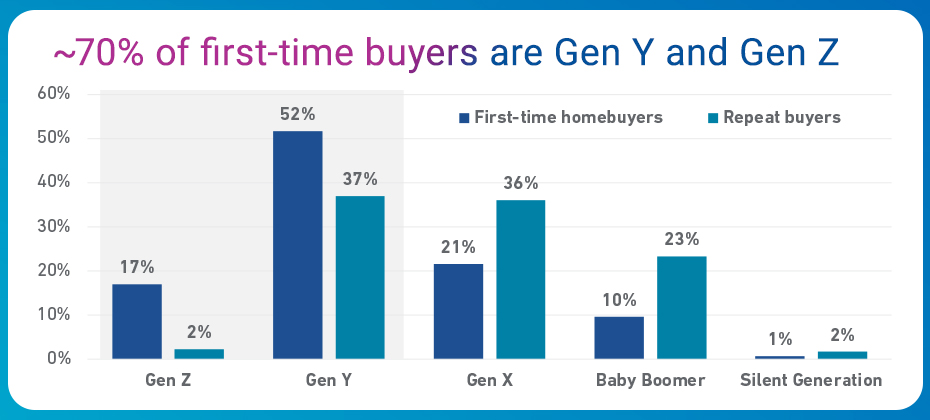
The younger generations comprise nearly 70% of first-time homebuyers, according to recent Experian Mortgage research. Understanding the generational traits of first-time homebuyers, particularly motivated younger generations, is critical to building highly targeted marketing strategies. Gen Z and Gen Y are essential in the first-time homebuyer market and represent close to 40% of repeat buyers, indicating they consider homeownership important beyond just their first purchase.
Generation Y borrowers lead the pack

Generation Y borrowers see homeownership as part of the American Dream but have waited longer than previous generations to purchase their first home.1 Additionally, as digital natives, they have grown up in a world with online resources and digital tools, making the home buying process more convenient for them. They can effortlessly research homes, compare mortgage rates, and even complete paperwork without leaving their home – a time and cost-saving advantage.

With their desire for stability and their technological proficiency, it comes as no surprise that Gen Y borrowers are at the forefront of the homebuying market, accounting for 52% of all first-time buyers.

Keep your eye on the next wave: Generation Z borrowers

Although Generation Z is the youngest group with both young adults and those entering adulthood, they should not be overlooked in the real estate market. Despite their age, Gen Z possesses characteristics and tendencies that make them legitimate potential first-time homebuyers.

Having grown up in an era characterized by technical advancements and economic instability, Gen Z has observed various challenges, such as the impact of the 2008 financial crisis on their families. They have also witnessed their parents and older siblings navigating student loan debt and a volatile job market. As a result, Gen Z individuals tend to approach life decisions with a cautious mindset.

However, it is important to note that Gen Z is a generation known for their ambition and determination. They have an entrepreneurial spirit. A strong desire for stability. According to a recent survey conducted by Chase2, homeownership holds an important place in the dreams of nearly 90% of Generation Z individuals. This unwavering aspiration for owning a home and increasing purchasing power establishes Generation Z as a significant influence in the real estate market.

Market to each generation where they are most comfortable, for Y and Z it is online and on the go

To get the attention of these younger generations, mortgage lenders must understand that for these groups, digital technology is the norm, integrated into all aspects of their lives. They rely heavily on social media, online reviews, and mobile apps for research and communication. Therefore, it is crucial for lenders to implement a marketing strategy that encompasses social media platforms and personalized email, and, increasingly, text communications, to resonate with the tech savvy nature of these generations. That said, there is nuance in every population, and we see this when observing communication preferences across generations. We know, for example, that first-time homebuyers are considerably more likely than the general public to respond to e-mail offers. Understanding communication preferences for each prospect is important for tailoring your omni-channel marketing approach.

Growing up in a world where technology is constantly advancing, Generations Y and Z are accustomed to having immediate access to information and services at their fingertips. As a result, they expect an efficient mortgage lending process that uses online, smartphone-enabled tools and platforms. They count on the ability to complete applications and paperwork online, receive updates and notifications via email or text, and have access to resources and tools to track and manage their mortgage journey.

Lenders embracing these realities about Gen Y and Gen Z and connecting with them where they are, will be better positioned to serve this demographic and grow their own business.

For more information about the lending possibilities for first-time homebuyers, download our latest white paper.

Download white paper

1 “Bank of America’s 2023 Homebuyer Insights Report Explores How Hopeful Buyers are Forging Ahead,” bankofamerica.com. 

2 “Millennial and Gen Z Adults Still See American Dream Within Reach Despite Challenges,” chase.com.


Related Posts

Cash Flow Insights: Powering the Next Evolution in Lending

For decades, credit data has given lenders a trusted foundation for assessing risk. Now, consumer-permissioned cash flow data is adding another layer of insight into consumers’ financial lives, including income, spending, liquidity and changing financial obligations. The opportunity is significant. Nearly one in five consumers lacks access to or has damaged credit. New Experian research also shows that 60% of consumers who have previously been denied credit or received less favorable terms than expected believe the outcome would have been different if lenders had considered their recent income and banking activity alongside their credit history. 1,2 For lenders, cash flow insights can provide additional context about a consumer’s financial capacity and support more informed underwriting decisions. The next challenge is making those insights easier to use consistently and responsibly at scale. What are cash flow insights? Cash flow insights are derived from consumer-permissioned banking data and provide visibility into how money moves into and out of a consumer’s accounts. Depending on the information available, cash flow data can provide insight into financial behaviors such as: Income and income stability: Regular and irregular income streams and changes over time Spending and recurring expenses: Everyday spending patterns and ongoing financial obligations Account balances and liquidity: Available funds and changes in account balances Debt obligations: Loan payments and other recurring debt commitments Cash flow patterns: How money moves into and out of accounts over time Traditional credit information provides a rich history of how consumers have managed credit. Cash flow insights add context about their current financial activity and capacity, providing lenders with a more complete view of financial health. Cash flow insights can also add predictive value to risk assessment. Experian analysis shows Cashflow Score can deliver up to a 25% lift in predictive performance over conventional credit scores when tailored to targeted risk tiers.3 How lenders can put cash flow insights to work at scale As interest in cash flow insights grows, the conversation is moving beyond what the data can reveal to how financial institutions can use it consistently and responsibly. That requires standardized consumer reporting, clear governance and decision-ready insights that can work within established lending processes. The launch of Experian Cashflow Data Bureau at Vision 2026 reflects this shift from access to adoption. The new consumer reporting agency operates under the Fair Credit Reporting Act (FCRA) and is designed to help financial institutions adopt consumer-permissioned cash flow insights at scale. A key part of that foundation is the cash flow consumer report, which organizes consumer-permissioned banking information into a standardized consumer report regulated under the FCRA. This gives lenders a consistent foundation for incorporating cash flow information into lending decisions while providing consumers with access to the information in their report. Turning greater visibility into better decisions The next evolution in credit isn’t about choosing between traditional credit and cash flow data. Each provides a different perspective. Traditional credit information offers deep insight into how consumers have managed credit over time. Cash flow insights can add context about financial activity and capacity. Bringing those perspectives together can give lenders greater visibility into consumers’ financial health and help them better distinguish between risk and resilience, support more informed decisions and identify opportunities to responsibly expand access to credit. As cash flow adoption continues to grow, its value will come from how effectively it complements the information lenders already use. The opportunity isn't simply to see more data. It's to turn that additional visibility into smarter, more informed decisions. Explore how Experian Cashflow Data Bureau is helping financial institutions put consumer-permissioned cash flow insights into practice at scale. Learn more [1] Federal Reserve Bank of New York, The Market for Credit Building: Demand, Product Characteristics and Consumer Uses, 2026. [2] Experian commissioned Atomik Research to conduct an online survey of 2,000 U.S. adults age 18+. Fieldwork took place July 16–21, 2026. Margin of error: +/- 2.2 percentage points at a 95% confidence level. [3] Based on Experian analysis when Cashflow Score is compared with conventional credit scores, tailored to targeted risk tiers. Predictability based on KS.

October 14, 2026 by Julie Lee
The Three Onboarding Fraud Pain Points That Slow Growth (And How to Solve Them) 

Effective fraud prevention is critical to balancing security and customer experience during onboarding. Learn more!

October 12, 2026 by Charles Hunter
How Rental Data Is Expanding Financial Opportunity for Millions of Renters 

Discover how rental payment reporting can expand credit access, strengthen credit profiles and improve risk assessment for renters and housing providers.

October 8, 2026 by Manjit Sohal

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe
