Tag: lending
Identity intelligence and alternative data can help lenders validate consumers and support more informed decisions across the customer lifecycle.
Manual processes are quietly expensive. Every handoff between teams, every file transfer waiting in a queue and every decision that sits on someone's desk adds cost, introduces risk and slows the customer experience. For financial institutions, those delays translate directly into lost revenue and eroded margins. That’s why workflow automation is becoming critical for financial institutions looking to stay competitive. Done well, it doesn't just make existing tasks faster. It reshapes how decisions get made across the entire customer lifecycle, from the first marketing touch to account servicing and beyond. What is workflow automation? Workflow automation is the use of technology to run a sequence of tasks, decisions and handoffs with minimal manual intervention. Instead of a person moving work from one step to the next — pulling data, applying a rule, routing an account and sending a communication — software executes those steps automatically based on defined logic and real-time data. For financial institutions, workflow automation usually combines four ingredients: Data Connecting to the internal and external data sources that inform a decision. Analytics Scores, models and attributes that turn raw data into insights. Decisioning A rules engine that determines the right action for each customer or account. Execution The operational layer that carries out the action, whether that's an offer, a credit line change or outreach. The benefits of workflow automation The value of automation goes well beyond "doing the same thing faster." The benefits financial institutions consistently see include:Greater efficiency and lower operating costsAutomation frees underwriters, analysts and agents to focus on exceptions and high-value work rather than repetitive processing. Faster, more consistent decisionsA credit application that once waited in a queue can be assessed in real time against consistent, auditable policies, improving both the applicant's experience and portfolio quality. Better customer experiencesAutomation enables financial institutions to personalize communications at the point of interaction and offer the self-service options that many people now prefer. Improved compliance and governanceReduce the risk of costly compliance failures with built-in controls, audit trails and guided workflows. ScalabilityRespond to changing volumes without sacrificing speed, consistency or the customer experience. Where workflow automation makes the biggest difference Workflow automation tends to deliver the most value where decisions are frequent, repeatable and informed by data. In financial services, those opportunities exist across the customer lifecycle. Onboarding Onboarding is a customer's first experience of your organization, and it's also where friction can cause customers to abandon the process and turn to another provider. Forty percent of U.S. consumers have considered walking away from opening a new account when the process felt burdensome.1 An automated onboarding workflow can bring together document verification, device intelligence, behavioral analytics, credit attributes and more, then orchestrate them into a single decision. The result is a lower-friction experience for the customer and a consistent, auditable process. Once customers are on the books, serving them well means making continuous, high-volume decisions: credit line changes, cross-sell and up-sell opportunities, risk monitoring and retention actions. Automation makes it practical to run these recurring decisions consistently across an entire portfolio, using a holistic view of each customer that draws on multiple scores and attributes. Lending The underwriting process is a great example of how workflow automation can help prevent applicants from waiting days for an answer. Loan origination and credit decisioning capabilities are designed to create a seamless review process across consumer and commercial lending. After automating originations with our solutions, Michigan State University Federal Credit Union cut application processing time to under 24 hours. Fraud Financial institutions are checking fraud at every touchpoint, and the standard for AI fraud detection continues to rise as fraudsters use AI to slip under the thresholds of any single detection tool. Rather than running fraud checks in isolation, an automated workflow can run multiple fraud and identity verification services in parallel and weigh signals together. A fraud decisioning platform connects signals across internal systems, Experian data and third-party services, allowing teams to stay on top of evolving threats. Build a strong foundation for workflow automation Workflow automation can connect these stages, creating a consistent decisioning framework. What ultimately separates good automation from great automation is the quality of the data and decisioning software underneath it. An automated workflow is only as good as the information feeding it. That's where our comprehensive credit, alternative and identity data with the tools financial institutions need to act on it. Learn more here FAQs How does automated decisioning improve credit decisions? Automated decisioning applies consistent logic to every account in real time or in bulk, enabling faster and more informed decisions, quicker responses to market and regulatory changes at the point of interaction. What is workflow automation in financial services? It's the use of software to execute sequences of data gathering, analysis, decisioning and action. Does workflow automation replace human judgment? No. The goal is to automate routine, high-volume decisions so skilled staff can focus on the exceptions and complex cases that genuinely require human judgment. For example, a sensitive collections conversation or a nuanced underwriting call. Are we still compliant with regulations if we use an automated workflow process? Well-designed platforms include built-in governance, audit trails and compliance controls that help institutions align with requirements like the Fair Credit Reporting Act (FCRA) and other regulatory guidelines improving compliance compared with manual processes. How long does it take to implement? It varies by solution and scope, but modern cloud-based platforms are designed for fast onboarding and limited IT involvement. 1Global Fraud Snapshot 2025: Opportunities and challenge in identity, fraud and financial crime
What if some of your best potential borrowers are the ones your traditional credit strategy can't fully see? A credit score can tell lenders a lot about a consumer, but it doesn't always capture the full picture of how someone is managing their financial life. For consumers with nontraditional income patterns or limited credit histories, that incomplete view can mean missed opportunities. In this Ask the Expert session, David Elmore of Experian talks with Michelle Goeppner, Chief Lending Officer at Vantage West Credit Union, about how alternative data can provide additional context around consumer risk, uncover opportunities traditional data alone might miss and help lenders expand their reach without disrupting strategies that already work. Who could lenders be missing? That question is especially important when a consumer’s financial life doesn’t fit neatly into a traditional credit profile. Take gig workers. Someone driving for Uber or delivering for DoorDash likely has a different income pattern than a salaried employee — irregular, seasonal, spread across platforms. That doesn't mean they aren't reliably managing bills, rent and other obligations. It just means a traditional file may not show it. Goeppner has a name for the risk of overlooking that context: FOMM — Fear of Missing Members. You've heard of FOMO — Fear of Missing Out. I think about it as FOMM — Fear of Missing Members. Who are we leaving behind if we're not using it?Michelle Goeppner, Chief Lending Officer For credit unions especially, that's not just a data question — it's a mission question. A partial view of a member's finances can mean missing a member the institution exists to serve. The credit score alone doesn't tell you where someone's headed Traditional credit data is still foundational to lending decisions. But alternative data — income, cash flow, payment behavior — adds a layer that a credit score alone can't provide. Goeppner illustrates the distinction with two consumers who have exactly the same credit score: I don't know if you're a 640 score on your way to 720 — or are you a 640 headed southwards to 580? It doesn't show me how you're managing your day-to-day financial lifeMichelle Goeppner, Chief Lending Officer Two borrowers can share the same score and be moving in opposite directions. Alternative data helps lenders tell the difference — and put that score in context rather than treating it as the whole story. Start small and layer it in Adopting alternative data doesn't mean overhauling an existing strategy. As Goeppner puts it, it's additive, not a replacement: It's not a rip and replace. You don't have to let go of your existing playbook. It's additive — you layer it in.Michelle Goeppner, Chief Lending Officer Her advice for getting started: Define the problem first. Are you trying to increase approvals, reach more underserved borrowers, or improve decisioning for a specific product? Test before you scale. Revisit loans you've already booked and ask whether alternative data would have changed the outcome — or pilot it on a single product before rolling it out further. Build in governance from day one. Document what changed, where the new data was used, and what results followed. As Goeppner puts it: “Crawl, walk, run. Slow and grow.” More loans without changing the risk profile For Vantage West, the value of that approach has shown up in its lending results. It has been an absolute game changer for us at Vantage West. We have been able to make more loans to our target members, our target segments, without changes to our risk profile.Michelle Goeppner, Chief Lending Officer That distinction matters. The goal isn't approving more loans for its own sake — it's having enough information to recognize good borrowers that traditional data alone would have missed. The result is a fuller picture of the people behind the credit file, and more confidence in deciding who a lender can serve. Explore alternative data with us Alternative data can help lenders add context to traditional credit information for a more complete view of consumers. Experian works with institutions of all sizes to incorporate additional consumer signals into existing lending strategies — strengthening decisioning, managing risk and identifying new opportunities for growth. Learn more Contact us About our experts Michelle Goeppner Chief Lending Officer, Vantage West Credit Union Michelle Goeppner is a dynamic financial services executive with over two decades of experience driving strategic growth, product innovation, and operational excellence across leading credit unions and financial institutions. Currently serving as the Chief Lending Officer at Vantage West Credit Union, Michelle leads the strategic vision for multi-billion-dollar consumer loan and deposit portfolios, as a member of the Executive Coalition. Her expertise spans consumer lending, product management, integrated marketing, and talent development, with a proven track record of leveraging fintech partnerships, automation, and data-driven strategies to optimize portfolio performance and member engagement. Throughout her career, Michelle has held pivotal leadership roles in organizations such as Alliant Credit Union and Discover Financial Services. She is recognized for her collaborative approach, detail-oriented execution, and commitment to developing future female leaders. Michelle’s contributions include founding Alliant’s Women’s Resource Group, serving on advisory councils and boards, and earning multiple industry awards for excellence and innovation. She holds an Executive Certification in Product Management from UC Berkeley, a Master of Science in Integrated Marketing Communications from Roosevelt University, and a Bachelor of Science in Marketing from Northern Illinois University. David Elmore Vice President of Fintech Sales, Experian David Elmore leads a team of fintech sales professionals at Experian focused on helping fintech organizations drive responsible, scalable growth through data-driven analytics and decisioning. With more than 20 years in financial services — a decade of it focused on fintech — he brings deep expertise in applying traditional and alternative data across the customer lifecycle. David and his team partner with fintech leaders to navigate opportunities across acquisition, underwriting, portfolio management, and collections, balancing innovation, risk, and trust.
Since 1996, The Internal Revenue Service (IRS) has issued more than 27 million individual taxpayer identification numbers (ITINs) – a 9-digit number used by individuals who are required to file or report taxes in the United States but are not eligible to obtain a Social Security number (SSN). Across the country, ITIN holders are actively contributing to their communities and the U.S. financial system. They pay bills, build businesses, contribute billions in taxes and manage their finances responsibly. Yet despite their clear engagement, many remain underrepresented within traditional lending models. Lenders have a meaningful opportunity to bridge the gap between intention and impact. By rethinking how ITIN consumers are evaluated and supported, financial institutions can: Reduce barriers that have historically held capable borrowers back Build products that reflect real borrower needs Foster trust and strengthen community relationships Drive sustainable, responsible growth Our latest white paper takes a more holistic look at ITIN consumers, highlighting their credit behaviors, performance patterns and long-term growth potential. The findings reveal a population that is not only financially engaged, but also demonstrating signs of ongoing stability and mobility. A few takeaways include: ITIN holders maintain a lower debt-to-income ratio than SSN consumers. ITIN holders exhibit fewer derogatory accounts (180–400 days past due). After 12 months, 76.9% of ITIN holders remained current on trades, a rate 15% higher than SSN consumers. With deeper insight into this segment, lenders can make more informed, inclusive decisions. Read the full white paper to uncover the trends and opportunities shaping the future of ITIN lending. Download white paper
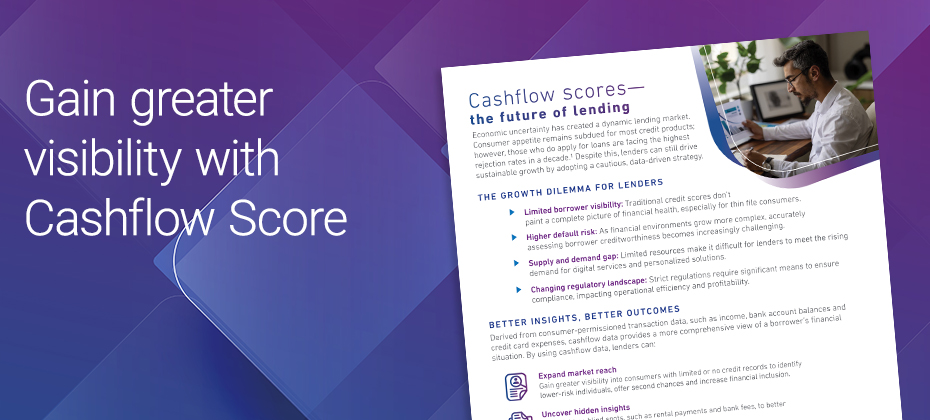
Discover how cashflow data empowers lenders to unlock new growth opportunities and manage risk more effectively.
We are squarely in the holiday shopping season. From the flurry of promotional emails to the endless shopping lists, there are many to-dos and even more opportunities for financial institutions at this time of year. The holiday shopping season is not just a peak period for consumer spending; it’s also a critical time for financial institutions to strategize, innovate, and drive value. According to the National Retail Federation, U.S. holiday retail sales are projected to approach $1 trillion in 2024, , and with an ever-evolving consumer behavior landscape, financial institutions need actionable strategies to stand out, secure loyalty, and drive growth during this period of heightened spending. Download our playbook: "How to prepare for the Holiday Shopping Season" Here’s how financial institutions can capitalize on the holiday shopping season, including key insights, actionable strategies, and data-backed trends. 1. Understand the holiday shopping landscape Key stats to consider: U.S. consumers spent $210 billion online during the 2022 holiday season, according to Adobe Analytics, marking a 3.5% increase from 2021. Experian data reveals that 31% of all holiday purchases in 2022 occurred in October, highlighting the extended shopping season. Cyber Week accounted for just 8% of total holiday spending, according to Experian’s Holiday Spending Trends and Insights Report, emphasizing the importance of a broad, season-long strategy. What this means for financial institutions: Timing is crucial. Your campaigns are already underway if you get an early start, and it’s critical to sustain them through December. Focus beyond Cyber Week. Develop long-term engagement strategies to capture spending throughout the season. 2. Leverage Gen Z’s growing spending power With an estimated $360 billion in disposable income, according to Bloomberg, Gen Z is a powerful force in the holiday market. This generation values personalized, seamless experiences and is highly active online. Strategies to capture Gen Z: Offer digital-first solutions that enhance the holiday shopping journey, such as interactive portals or AI-powered customer support. Provide loyalty incentives tailored to this demographic, like cash-back rewards or exclusive access to services. Learn more about Gen Z in our State of Gen Z Report. To learn more about all generations' projected consumer spending, read new insights from Experian here, including 45% of Gen X and 52% of Boomers expect their spending to remain consistent with last year. 3. Optimize pre-holiday strategies Portfolio Review: Assess consumer behavior trends and adjust risk models to align with changing economic conditions. Identify opportunities to engage dormant accounts or offer tailored credit lines to existing customers. Actionable tactics: Expand offerings. Position your products and services with promotional campaigns targeting high-value segments. Personalize experiences. Use advanced analytics to segment clients and craft offers that resonate with their holiday needs or anticipate their possible post-holiday needs. 4. Ensure top-of-mind awareness During the holiday shopping season, competition to be the “top of wallet” is fierce. Experian’s data shows that 58% of high spenders shop evenly across the season, while 31% of average spenders do most of their shopping in December. Strategies for success: Early engagement: Launch educational campaigns to empower credit education and identity protection during this period of increased transactions. Loyalty programs: Offer incentives, such as discounts or rewards, that encourage repeat engagement during the season. Omnichannel presence: Utilize digital, email, and event marketing to maintain visibility across platforms. 5. Combat fraud with multi-layered strategies The holiday shopping season sees an increase in fraud, with card testing being the number one attack vector in the U.S. according to Experian’s 2024 Identity and Fraud Study. Fraudulent activity such as identity theft and synthetic IDs can also escalate. Fight tomorrow’s fraud today: Identity verification: Use advanced fraud detection tools, like Experian’s Ascend Fraud Sandbox, to validate accounts in real-time. Monitor dormant accounts: Watch these accounts with caution and assess for potential fraud risk. Strengthen cybersecurity: Implement multi-layered strategies, including behavioral analytics and artificial intelligence (AI), to reduce vulnerabilities. 6. Post-holiday follow-up: retain and manage risk Once the holiday rush is over, the focus shifts to managing potential payment stress and fostering long-term relationships. Post-holiday strategies: Debt monitoring: Keep an eye on debt-to-income and debt-to-limit ratios to identify clients at risk of defaulting. Customer support: Offer tailored assistance programs for clients showing signs of financial stress, preserving goodwill and loyalty. Fraud checks: Watch for first-party fraud and unusual return patterns, which can spike in January. 7. Anticipate consumer trends in the New Year The aftermath of the holidays often reveals deeper insights into consumer health: Rising credit balances: January often sees an uptick in outstanding balances, highlighting the need for proactive credit management. Shifts in spending behavior: According to McKinsey, consumers are increasingly cautious post-holiday, favoring savings and value-based spending. What this means for financial institutions: Align with clients’ needs for financial flexibility. The holiday shopping season is a time that demands precise planning and execution. Financial institutions can maximize their impact during this critical period by starting early, leveraging advanced analytics, and maintaining a strong focus on fraud prevention. And remember, success in the holiday season extends beyond December. Building strong relationships and managing risk ensures a smooth transition into the new year, setting the stage for continued growth. Ready to optimize your strategy? Contact us for tailored recommendations during the holiday season and beyond. Download the Holiday Shopping Season Playbook
How can lenders ensure they’re making the most accurate and fair lending decisions? The answer lies in consistent model validations.
With the advent of AI and ML, optimizing credit prescreen campaigns has never been easier or more efficient.
Automate your credit limit management process to better serve your customers and quickly respond to the volatile market.
View our digital lending trends report for a full analysis on origination volume trends, delinquency trends, and consumer behavior insights. Read more!
Learn how Washington State Employees Credit Union increased their revenue and member satisfaction by implementing a digital prequalification process.
Lenders are increasingly using artificial intelligence (AI) and machine learning (ML) throughout the customer lifecycle and access to these advanced tools is expanding.
A move toward inclusive finance, including incorporating alternative data in credit scoring models, is a crucial step towards promoting financial inclusion.
There are many ways to promote a more equitable society - including financial inclusion or reducing the racial wealth gap for underserved communities.
Shri Santhanam, Executive VP and GM of Experian's Global Analytics and Artificial Intelligence talks advanced analytics and AI in lending in recent podcast.