Tag: interest rates
Amid interest rates leveling out and some lenders reassessing go-to-market strategies, the automotive finance landscape is experiencing notable shifts in market share. According to Experian’s State of the Automotive Finance Market Report: Q1 2025, banks recouped some of their total finance market share for the first time in several years, reaching 26.6% during the quarter, up from 24.8% a year ago. On the other hand, captives’ total market share declined from 31.3% to 29.8% year-over-year and credit unions experienced a modest increase from 20.2% to 20.6%. Despite the overall market share shifts, captives continue to lead in new vehicle financing at 57.1% in Q1 2025, although down from 62.1% the year prior. Meanwhile, banks increased to 24.1% this quarter, from 20.4% in Q1 2024 and credit unions went from 9.6% to 10.9% during the same period. On the used side, banks and credit unions were grouped much closer together. Banks led the way with 28.4% of the used finance market in Q1 2025, up from 27.9% last year, while credit unions went from 27.7% to 28.2% year-over-year and captives declined from 8.5% to 7.4%. As market share movement continues to be a valuable indicator of shifting strategies and consumer behavior, it’s important for automotive professionals to keep a close eye on these shifts to uncover new opportunities while looking for ways to stay ahead of the rapidly evolving industry. Breaking down the latest finance trends Data in the first quarter of 2025 shows the automotive finance market continues to stabilize as automotive professionals gain clearer visibility into lender behavior and consumer demand. For example, the average loan amount for a new vehicle increased $1,110 year-over-year to $41,720 in Q1 2025. However, the average interest rate dropped from 6.9% to 6.7%, and the average monthly payment went from $737 last year to $745 this quarter. For used vehicles, the average loan amount saw a slight uptick of $90 year-over-year, reaching $26,144 this quarter. Meanwhile, the average interest rate declined from 12.4% last year to 11.9% this quarter and the average monthly payment trended lower at $521, from $524 in Q1 2024. Monitoring and leveraging market share shifts and financing trends can support strategic planning while empowering automotive professionals to anticipate consumer purchasing patterns and tailor conversations more effectively to meet buyers where they are during their car buying journey. To learn more about automotive finance trends, view the full State of the Automotive Finance Market: Q1 2025 presentation on demand.
Driven by a range of appealing factors including lower monthly payments and a wider array of models—due to the continuous rise in new vehicle inventory—leasing has reappeared as an optimal choice for consumers who are in the market for a vehicle. According to Experian’s State of the Automotive Finance Market Report: Q2 2024, leasing increased to 25.35%, up from 21.14% in Q2 2023 and 19.30% the year prior. While the average monthly payment and interest rate for a new loan modestly increased year-over-year, leasing is increasingly becoming a more attractive option for those leaning towards flexibility and affordability. For example, the average monthly payment on a leased vehicle was $148 less than a loan this quarter. What’s more, it seems consumers are leaning towards larger vehicles. For instance, the Honda CR-V (2.98%) continued to lead the top leased models in Q2 2024, and it was followed closely by the Tesla Model Y (2.61%). Rounding out the top five were the Honda Civic (2.29%), Ford F-150 (2.02%), and Chevrolet Silverado 1500 (1.86%). Prime financing grows and lease payments decline across all segments When looking at risk distribution trends in Q2 2024, prime consumers accounted for nearly 70% of the total finance market—with prime coming in at 37.82%, down from 39.84% last year and super prime increasing from 28.98% to 31.59% year-over-year. Subprime also saw a slight increase, going from 13% to 13.06% during the same period. It’s notable that all risk segments experienced a decrease in average monthly payments for leased vehicles, as super prime went from $601 in Q2 2023 to $586 in Q2 2024, prime declined to $583 this quarter, from $596 last year, and subprime was at $597, from $611. With the average monthly payments declining year-over-year for majority of shoppers, it can potentially create a more competitive market and drive more consumers towards this finance option—something automotive professionals should keep a close eye on. New and used vehicle finance market overview Data in Q2 2024 found that new vehicle loan amounts increased slightly, reaching $40,927, up from $40,743 last year, and the average interest rate went from 6.78% to 6.84% year-over-year. Despite the increases, the average monthly payment for a new vehicle only experienced a $1 growth to $734 this quarter. On the used side, the average loan amount declined from $27,316 Q2 2023 to $26,248 in Q2 2024, and the average rate grew from 11.47% to 12.01% in the same time frame. Though, the average monthly payment declined to $525 this quarter, from $536 last year. As the automotive industry continues to adapt to the changing market conditions and consumer preferences, it’s important for professionals to leverage the most current data—this will allow them to effectively assist consumers by meeting their financial needs with the available options. To learn more about automotive finance trends, view the full State of the Automotive Finance Market: Q2 2024 presentation on demand.
According to Experian’s State of the Automotive Finance Market Report: Q4 2023, EVs comprised 8.6% of total new retail transactions, an increase from 7.1% in Q4 2022.
According to Experian’s State of the Automotive Finance Market Report: Q3 2023, the average new vehicle loan amount decreased to $40,184, from $41,543 in Q3 2022 and the average used vehicle loan amount went from $28,684 to $27,167 year-over-year.
Experian’s State of the Automotive Finance Market Report: Q4 2022 found that the year-over-year (YOY) average new loan amount increased 4.04%, a smaller growth rate compared to 12.46% YOY in Q4 2021
To help the industry better understand the widespread growth, ahead of the show we compiled an Auto Finance Year-in-Review report to break down all things EV—from financing trends to vehicle segments and more.
The mortgage and real estate industries have been uniquely affected by COVID-19. Here's 3 components missing from a truly modernized mortgage experience.
Some segments of the financial markets are beginning to bet that the Federal Reserve will take interest rates negative for the first time in U.S. history.
The Federal Open Market Committee closed their latest meeting on April 29 and provided a look into how long rates may remain at their current levels.
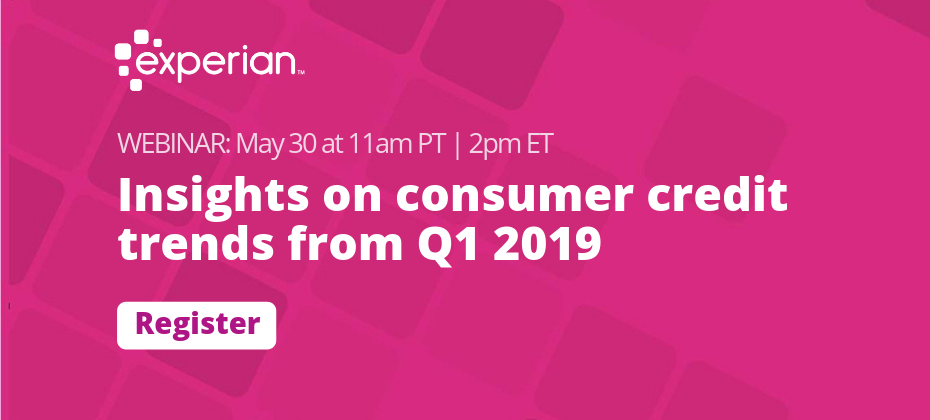
Consumer credit trends and markets are constantly evolving, particularly when it comes to originations and delinquencies on mortgages, credit cards and auto loans. According to Experian research, over 2.7 million out of 89 million active automotive loans and leases are either 30 or 60 days delinquent. Triggers that signal a greater likelihood of consumers falling delinquent on loans, mortgages and credit card payments, include high-interest rates, a high utilization rate and recent derogatory trades. By tracking and forecasting consumer trends over time, you can more easily predict consumer behavior and better prepare for potential issues within each market. Join Gavin Harding, Experian Senior Business Consultant, and Alan Ikemura, Experian Data Analytics Senior Product Manager, during our live Quarterly Credit Trends webinar on May 30 at 2:00 p.m. ET. Our expert speakers will provide a view of the real estate market and share insights on the latest consumer credit trends. Highlights include: 2019 economic drivers Q1 2019 origination and delinquency trends Mortgage Home equity Bankcard Auto Register now
Not only are personal loans are increasing, but so is the share of those loans originated by FinTechs is also growing quickly across all generations.
Since 1948, International Credit Union Day – a time to recognize the credit union movement – has been celebrated the third Thursday of October. The day is the perfect time to remind your members and consumers about all of the services and benefits your credit union offers. This year’s theme, “The Authentic Difference,” celebrates what makes credit unions stand out. Here are 10 reasons CUs deserve a spotlight: Credit unions are non-profit cooperatives, owned and operated by its members. That means they emphasize consumer value to more than 217 million members worldwide. Profits go back to members in the form of reduced fees, higher savings rates and lower loan rates. Personal relationships are key. Credit unions pride themselves on developing relationships with their members, and CUs are typically staffed by friendly reps who know customers by name. Checking accounts are free. Roughly 80 percent of credit unions offer free checking accounts, compared to less than 50 percent of banks, according to economic research firm Moebs Services. Few ATM fees. Many credit union customers are able to avoid ATM fees because CUs typically give them access to a large network of ATMs by sharing branches and other resources. Savings rates are above average. Because credit unions don't have to pay dividends to shareholders and are exempt from federal taxes they can offer high rates on saving accounts. The average credit union offers CD, money market, and savings rates well above the national banking rates average. Lower interest rates. Credit unions offer lower interest rates on some loans. The difference between banks and credit unions was greatest in car-loan interest rates, according to a September report by SNL Financial. The average 36-month used-car loan interest rate offered by CUs was 2.67 percent compared to 4.45 percent for banks. For new-car loans, CUs offered an average interest rate for 48 months of 2.60 percent compared to 3.94 percent for banks. Invested in the community. A credit union’s core values are focused on its members and the communities where they live and work. Many provide financial education and outreach to consumers. It’s easier to get credit. CUs don’t have to abide by loan restrictions and qualifications mandated by a corporate office, so they have more flexibility to make loans when possible. Small-business support: CUs may know borrowers and are able to take into account intangibles like community reputation and accountability. Also, they understand the value to the community of a small business, its market and credit needs. Joining is easy. Many credit unions base eligibility simply on where you live, instead of restricting membership to a particular employer. Since expanding eligibility, credit union membership has grown by about two percent a year for the past decade.