Latest Posts
Fraud prevention in lending has become increasingly complex. As consumers expect faster, more seamless digital experiences, fraudsters are using increasingly sophisticated tactics to exploit gaps in identity verification, application processes and account security. In response, many lenders have added new fraud tools and data sources to their technology stacks. But simply adding more tools doesn't necessarily create a stronger fraud strategy. When solutions operate independently, lenders may struggle to connect risk signals, respond quickly to emerging threats and determine when additional verification is actually necessary. Fraud orchestration can help solve this challenge by bringing fraud tools, data and risk signals together within a coordinated decisioning workflow. Instead of treating each fraud solution as a separate checkpoint, organizations can use orchestration to determine which checks to perform and what action to take based on the risk associated with each interaction. For lenders, this can lead to faster decisions, stronger fraud prevention and a more seamless experience for legitimate customers. What is fraud orchestration? Fraud orchestration is the process of coordinating multiple fraud prevention tools, data sources, analytics and risk signals within a unified workflow.A lender may use a wide range of capabilities to identify and prevent fraud, including: Identity verification Device intelligence Document verification Biometrics Behavioral signals Email and phone intelligence Consortium and bureau data Velocity checks Internal fraud data Rules and machine learning models Individually, these capabilities can provide valuable information about an applicant or customer. Fraud orchestration helps lenders bring those signals together and determine the appropriate response. Rather than requiring every applicant to pass through the same sequence of fraud checks, an orchestrated workflow can adapt based on the risk presented.For example, an applicant whose identity, device and application information show little indication of fraud may be able to proceed without additional verification. An application displaying inconsistencies or elevated risk signals could trigger additional identity verification, document verification or manual review. In this way, fraud orchestration helps turn a collection of individual fraud tools into a coordinated fraud prevention strategy. Why lenders need fraud orchestration Digital lending has made it possible for consumers to apply for credit quickly and conveniently. But it has also created more opportunities for fraudsters to exploit digital channels. Lenders may encounter identity theft, synthetic identities, account takeover, first-party fraud, automated attacks and other forms of fraud throughout the customer lifecycle. At the same time, fraudsters can adapt their methods as organizations introduce new controls. The challenge is compounded when fraud prevention tools operate in silos. A device intelligence solution may identify one risk signal, while an identity verification service identifies another. Behavioral data may reveal additional anomalies. Internal data and third-party information may provide still more context. Evaluating these signals separately can make it difficult to develop a complete picture of risk. It can also lead organizations to apply additional controls broadly, potentially creating unnecessary friction for legitimate applicants. Fraud orchestration provides a framework for connecting these capabilities so organizations can assess risk more holistically and respond appropriately. How fraud orchestration works While fraud orchestration strategies vary by organization, an orchestrated fraud workflow generally involves several interconnected steps. 1. Collect risk signals The process begins by gathering relevant information about an application or customer interaction. Depending on the use case, this might include identity information, device characteristics, behavioral signals, application data, historical information and third-party fraud intelligence. 2. Analyze the interaction Rules, risk models and advanced analytics can evaluate the available signals and identify patterns associated with legitimate or potentially fraudulent activity. Technologies such as AI fraud detection can help organizations analyze large volumes of information and identify complex patterns that may be difficult to detect using static rules alone. Similarly, fraud detection machine learning can help uncover relationships across large datasets and adapt as fraud patterns change. 3. Determine the appropriate next step The orchestration layer uses the available risk information to determine what should happen next. A low-risk interaction might proceed without additional verification. An interaction with conflicting signals could trigger another fraud check. Higher-risk activity could require step-up authentication, document verification or manual review. The goal is not necessarily to perform every available fraud check. It is to perform the appropriate checks based on the risk presented. 4. Make and execute the decision Once the necessary information has been evaluated, the workflow can support a decision or route the interaction to the appropriate next step. This approach allows organizations to automate more decisions while reserving additional verification and human review for situations where they may provide the greatest value. Fraud orchestration across the lending journey Although fraud prevention is often associated with the initial application, fraud risk doesn't disappear after an account is opened.An effective orchestration strategy can help organizations manage fraud risk throughout the customer lifecycle. Application and onboarding At application, lenders can combine identity information with device, behavioral, application and other risk signals to evaluate potential fraud.Passive capabilities can be particularly valuable at this stage because they can help identify risk without automatically requiring additional actions from the applicant. For example, behavioral analytics can analyze how users interact with digital forms and provide additional insight into potential risk. When incorporated into an orchestrated workflow, behavioral signals can help determine whether an application should continue normally or whether additional verification may be warranted. Identity verification When an application contains inconsistencies, orchestration can trigger additional identity checks based on the type and level of risk detected. Rather than requiring every applicant to upload an identity document or complete another verification step, lenders can reserve additional controls for situations where they are needed. Credit decisioning Fraud risk and credit risk are distinct, but both can influence lending decisions. Connecting fraud insights with broader decisioning workflows can help lenders evaluate applications efficiently while applying appropriate fraud controls. Account management Fraud orchestration can continue after origination. Changes to contact information, login behavior, devices or other account characteristics may create new risk signals. An orchestrated workflow can use those signals to determine whether additional authentication or verification is appropriate. Transactions and disbursements Fraud controls can also be applied when funds are disbursed or when other sensitive transactions occur. Combining account, identity and transaction-related signals can help organizations identify potentially suspicious activity before completing an action. Benefits of fraud orchestration for lenders Bringing fraud capabilities together within an orchestrated workflow can create several advantages. Faster decision making Running every applicant through every available fraud check can slow decisions and create unnecessary complexity. Fraud orchestration allows lenders to dynamically select the appropriate tools and data sources based on risk. Straightforward applications can move through the process quickly, while higher-risk applications receive additional scrutiny. Stronger fraud prevention Fraud signals become more useful when they can be evaluated together. Combining identity, device, behavioral and other information can provide a more complete picture of an interaction. Advanced analytics and machine learning can identify patterns across those signals, while orchestration determines the appropriate response. This layered approach can also make fraud strategies more adaptable as threats evolve. Reduced manual review Manual review can be valuable for complex cases, but it can also increase operating costs and extend decision times. Better coordination of fraud signals can help organizations automate decisions where sufficient information is available and direct investigators toward applications that genuinely require additional attention. Better customer experiences Strong fraud prevention doesn't have to mean creating more friction for every customer. Orchestration can help organizations distinguish between interactions that can proceed normally and those that warrant additional verification. Legitimate applicants may encounter fewer unnecessary challenges, while additional controls can be introduced when risk increases. The result is a more risk-based approach to friction: applying it where it adds value rather than making every customer prove their legitimacy through the same process. Greater flexibility Fraud threats, business strategies and technology change over time. An orchestration approach can make it easier to adjust workflows, incorporate new data sources and deploy additional fraud capabilities without rebuilding the entire fraud process. This flexibility can help organizations respond more quickly as fraud patterns and customer expectations evolve. Building an effective fraud orchestration strategy Fraud orchestration isn't simply a technology implementation. Organizations also need to determine how data, analytics, policies and customer experience should work together. A useful framework is to think about four capabilities: Connect. Bring together relevant fraud tools, internal information and third-party data sources. Analyze. Use rules, models and analytics to evaluate signals collectively and develop a clearer view of risk. Orchestrate. Determine which capabilities should be invoked and what action should occur based on the risk presented. Adapt. Monitor results and adjust strategies as fraud patterns, business needs and customer behavior change. The objective is to create a fraud strategy that can respond differently to different levels and types of risk rather than applying a fixed set of controls to every interaction. Turning fraud signals into coordinated decisions Lenders have access to more fraud data and technology than ever before. The challenge is making those capabilities work together. Fraud orchestration provides the connective layer between data, fraud detection and action. By coordinating fraud tools and risk signals within a unified workflow, lenders can identify risk earlier, dynamically apply the appropriate controls and make faster decisions. Experian helps organizations connect data, analytics and fraud prevention capabilities to support identity verification and fraud decisioning throughout the customer lifecycle. With an orchestrated approach, lenders can strengthen fraud prevention while reducing unnecessary friction for legitimate customers. As fraud threats continue to evolve, the ability to connect, analyze and act on risk signals in real time can help lenders stay ahead of emerging threats while delivering the fast, convenient experiences consumers expect. Explore our Fraud Orchestration Infographic Fraud Orchestration in Lending: One Workflow, Not Five Disconnected Tools
New data indicate signs of increased VantageScore 4.0 adoption. Recent Experian Capital Markets data reporting points to gradual growth in VantageScore 4.0 adoption, and more loans beginning to appear in a larger share of GSE pools.
Ransomware attacks can create challenges that extend far beyond an organization’s IT systems. When critical applications become unavailable or sensitive information is compromised, businesses may face operational disruption, financial losses and difficult decisions about how to support affected customers. While cybersecurity defenses are essential, organizations also need clear response procedures, coordinated communication and recovery plans. Understanding how ransomware attacks happen, their potential impact and the steps organizations can take to prepare can help businesses respond more effectively when an incident occurs. What is a ransomware attack? A ransomware attack is a type of cyberattack in which criminals use malicious software or extortion tactics to demand payment from an organization. Traditionally, ransomware encrypts files or systems, preventing authorized users from accessing information until a ransom is paid. Some attackers also steal sensitive data and threaten to release it unless their demands are met. These tactics may occur separately or together, creating challenges for organizations trying to restore operations and protect sensitive information. Paying a ransom does not guarantee that attackers will restore access, delete stolen information or refrain from making additional demands. How do ransomware attacks happen? Ransomware attacks often begin when cybercriminals gain unauthorized access to an organization’s systems or accounts. Once inside, attackers may attempt to expand their access, steal information or deploy malicious software. Common attack methods include: Phishing and social engineering: Deceptive emails or messages that trick employees into opening malicious attachments, visiting harmful websites or sharing login credentials Compromised credentials: Stolen passwords or authentication information used to access business systems and accounts Unpatched vulnerabilities: Security weaknesses in software, servers or network devices that attackers exploit Third-party access: Compromised vendors or connected systems that provide a potential entry point Malicious downloads: Harmful software installed through deceptive websites, compromised applications or unsafe downloads Understanding these methods can help organizations identify potential weaknesses and strengthen their security practices. How do ransomware attacks affect businesses and customers? The consequences of a ransomware attack depend on the systems affected, the information involved and the organization's ability to contain the incident. Business disruption and financial losses When critical systems become unavailable, organizations may experience interruptions to customer service, payment processing, internal operations or other essential functions. The financial impact can be significant. According to the FBI's 2025 Internet Crime Report, reported ransomware-related losses reached approximately $32.3 million, up from $12.5 million in 2024. These figures do not capture the full financial impact of ransomware incidents, including business interruption, recovery expenses and other indirect costs. Customer data exposure and fraud risks Some ransomware incidents involve the theft of sensitive information, potentially exposing customers to identity theft or fraud. If attackers obtain login credentials or personal information, organizations may also need to consider related threats, including account takeover. Customer trust and reputation Customers expect organizations to protect their information and communicate clearly when incidents affect them. Delayed or confusing communication may create additional uncertainty. A coordinated response can help organizations provide timely information and appropriate support to affected individuals. What should organizations do after a ransomware attack? When a ransomware incident is suspected, organizations should activate their incident response procedures and work with qualified professionals to assess and contain the threat. Important response steps include: Activate the response team: Bring together IT, cybersecurity, legal, privacy, communications and leadership teams as appropriate. Contain the incident: Identify affected systems and take steps to limit further unauthorized activity while preserving relevant evidence. Investigate the impact: Determine which systems and information may have been compromised, including whether sensitive data was accessed or removed. Evaluate notification requirements: Work with legal and privacy advisers to determine applicable regulatory, contractual and customer communication obligations. Support affected customers: Prepare clear communications and appropriate resources when personal information has been exposed. An established data breach response strategy can help organizations coordinate customer notification and support activities following an incident. How can organizations prepare for and recover from ransomware attacks? Organizations can prepare for ransomware attacks by combining security controls, tested backups, employee training and a documented incident response plan. Recovery planning should also address how teams will restore systems, assess data exposure and communicate with affected customers. Key preparedness measures include: Maintain secure backups: Keep protected backups and regularly test restoration procedures. Strengthen access controls: Implement multifactor authentication and limit access to sensitive systems. Update software: Address known vulnerabilities through consistent patch management. Train employees: Help staff recognize phishing attempts and suspicious activity. Monitor security threats: Use appropriate detection and monitoring tools to identify potential attacks. Test response plans: Conduct exercises that evaluate technical recovery, communication and decision-making responsibilities. Following an incident, recovery should focus on restoring systems safely, addressing remaining vulnerabilities and evaluating potential risks to affected individuals. Organizations may also need to consider whether compromised information could contribute to additional fraud. Depending on the circumstances, fraud prevention solutions may support broader identity risk management efforts. Security teams should also evaluate related threats, including automated bot attacks, when assessing potential misuse of compromised accounts or credentials. Once operations are restored, reviewing lessons learned can help organizations strengthen their security controls, response procedures and future preparedness. How can breach response planning help protect customers? Ransomware preparedness should account for both operational recovery and the potential impact on customers. If sensitive information is compromised, organizations may need to coordinate notifications, respond to customer questions and provide appropriate support. Experian® offers data breach resolution services that help organizations plan for and manage customer-facing aspects of a breach, including notification management and response support. By establishing response procedures before an incident, organizations can improve coordination and prepare to address customer needs when a breach occurs. Prepare for a more coordinated breach response Explore Experian's data breach response solutions and learn how to plan for customer notification and support. Explore data breach response solutions Download the 2027 Data Breach Response Guide
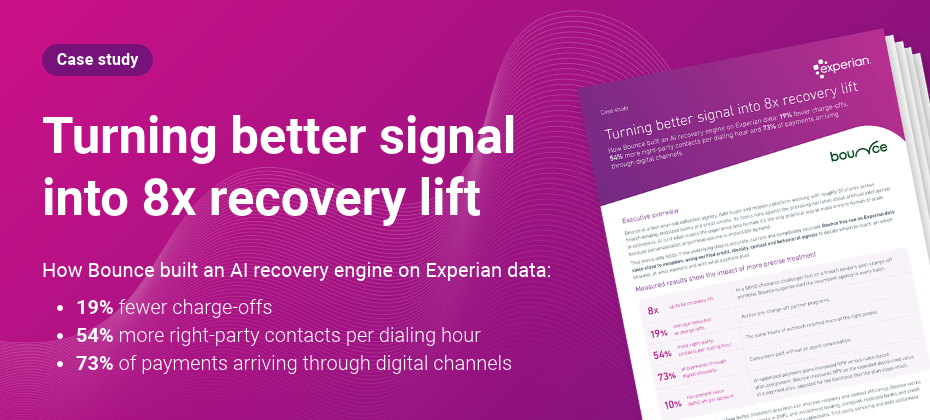
Artificial Intelligence (AI) can help collections teams personalize debt recovery at scale, but only when it has accurate, current data to work with. Bounce, a collection agency, debt buyer and recovery platform shares how they combine consumer data, affordability models and compliance rules to decide when and how to reach people. A more tailored, data-driven approach to recovery Many traditional collections strategies rely on broad treatment paths. Accounts may enter a queue and receive a set sequence of letters and calls, regardless of a consumer’s circumstances or preferred channel. Bounce is taking a more tailored collections strategy, using data to guide prioritization, outreach and treatment. How data supports five stages of debt recovery Bounce assesses affordability so offers are sized to what a consumer may realistically sustain emphasizing human agents handling conversations where a person can make a difference, including disputes, hardship, complex negotiation and high-balance accounts. Bounce integrates Experian data at five points in the recovery lifecycle: Portfolio hygiene Identifying bankrupt and deceased consumers so those accounts can receive special handling. Segmentation and prioritization Ranking consumers by likelihood of repayment in the near term. Contact and channel strategy Pinpointing best-known phone and address data at the point of outreach. Timing Alerts notifying teams of relevant changes in a consumer's credit file. Model enrichment Building a custom model to apply Premier and Trended 3D attributes to it. Results With the reimagined recovery approach, Bounce found: Up to 8x recovery lift 19% average reduction in charge-offs 54% more right-party contacts per dialing hour Why Bounce's approach depends on Experian data Bounce's view is that documented data lineage helps support approval of automated treatment decisions. Data quality and freshness can limit how precisely a model treats consumers: a model can only act on the information available to it. The case study also describes compliance rules set by legal and compliance teams and enforced as constraints the model can't override. Explore the Bounce case study Download the case study to learn how Bounce uses data across recovery, assigns work between models and human agents, and reports its results. Download case study

Today’s AI-powered fraud bots are exceptionally good at mimicking human behavior. Learn why a modern defense strategy is key.

Learn what incident response is, the key steps in the process and how to build and test an incident response plan for a data breach.

Experian’s new Recovery Scores model turns portfolio intelligence into more focused recovery strategies, helping organizations improve returns, direct effort and accelerate speed to cash. The challenge isn’t simply working more accounts. Whether a debt buyer is evaluating an acquisition, an agency is deciding where to assign collector time or a lender is managing its own post-charge-off accounts, the question is similar: How can limited capacity be directed toward accounts with the greatest potential for recovery? Prioritizing accounts mainly by age, balance or when they were last worked may not show which ones are most likely to generate a recovery. With the new Recovery Scores model, organizations can rank charged-off accounts by expected collectability, providing a consistent signal to inform placement strategy and treatment decisions across the recovery lifecycle. Make collector capacity a strategic resource Working every account with the same level of attention isn’t always practical. The more useful question is: Where should teams focus first to protect speed to cash? Our model performance analysis found: 80% of recovered dollars come from the top 40% of accounts worked. The value isn’t simply a better ranking. It’s how organizations can use it for collections optimization. Score bands can inform different strategies for placement, outsourcing, auction and legal channel treatment rather than applying the same approach across an entire portfolio. For debt buyers: The scores can inform acquisition pricing and how a newly purchased portfolio is divided across internal collections, legal channels and resale. Expected collectability can shape debt portfolio analysis, including how a portfolio is valued and segmented before collection work begins. For agencies: Score bands can help teams focus collector resources on accounts with stronger recovery potential. For first-party lenders: Managing recovery internally, the scores provide another signal to help structure decisions about which accounts to work and in what order. Look beyond collectability alone Prioritization rarely comes down to a single variable. Consider two accounts that both rank highly for expected collectability, but one has a substantially larger balance. Their recovery likelihood may be similar, but the potential dollars recovered are not. The Recovery Scores model uses debt collections analytics by combining Experian’s bureau-based score with current balance information. This helps organizations consider both the likelihood of recovery and the potential dollars at stake, while sensitive balance information remains within the organization’s working environment. Monitor accounts as they change The first decision about an account is rarely the last. Teams continually make choices about treatment, placement and resource allocation as accounts move through the recovery process. Recovery Scores is also available as a trigger. When underlying information changes, teams can receive an update and reconsider an account’s placement without waiting for the next portfolio-wide re-score. An account that shows lower recovery potential today may have a different recovery outlook later. Turn recovery potential into a portfolio strategy When portfolios contain more accounts than teams can work at once, the question isn’t simply, “How many accounts can we work?” It is, “Where can our resources have the greatest impact?” The latest Recovery Scores model helps organizations sharpen placement and treatment decisions. It gives debt buyers a way to price and segment portfolios with greater confidence and gives lenders another tool to direct limited collector time across their own post-charge-off portfolios. Learn more about Experian Recovery Scores
Learn what a third-party breach is and steps to prepare, contain risk, and support affected customers. Read more!
Mortgage underwriting is entering a new phase. In a recent conversation with HousingWire’s Allison LaForgia, Michele Bodda, Group President of Experian Housing, Verification Solutions, and Employer Services, discussed how modern credit scores, alternative data and verification tools are changing how lenders evaluate borrowers. Lenders can now judge modernization by its results, Bodda said. “Now we’re actually letting more modern scores get into underwriting to help price loans and go all the way through to securitization,” she told HousingWire. “We’re letting the scores and the data actually speak for itself instead of just talking about it.” The Right Data at the Right Time Modernizing underwriting means providing useful information at the right stage, rather than giving lenders everything at once. “You don’t need everything all at once. You don’t need everything on initial pull,” Bodda said. Alternative data, such as rental payments and buy now, pay later activity, can help show how consumers manage obligations, especially those with thinner credit files. A thin credit file does not necessarily mean someone has a thin financial life. “It’s our responsibility as one of the primary data providers to make sure we can make all of that available, so that we’re best representing the consumer,” Bodda said. A fuller view of data may help lenders identify creditworthy applicants who might otherwise be difficult to assess. Simplifying Verification and Reducing Friction Bodda also shared how Experian is making credit information more easily accessible and reducing unnecessary costs during the originations process, explaining that new enhancements to Experian’s Power Profile Plus allow lenders to pull credit data at the start of underwriting and request another score later without repurchasing the data. “You can pull it later and not pay for the credit data again,” Bodda said. Experian is also investing in income and employment verification, including through a new partnership with Workday. Bodda explained that Experian will continue to focus on process improvement, competition and innovation across the mortgage ecosystem. A Broader Path to Homeownership As consumer expectations and underwriting capabilities evolve, borrowers want a process that reflects their financial lives, while lenders seek greater efficiency. Modern scores, relevant data, and streamlined verification can help lenders assess applications with more context—and may help more people pursue homeownership. “If we as an industry can open this up and bring more people into the process, then we’re going to thrive,” Bodda said in the interview. Watch the interview and hear all of Michele’s insights, and more here.
A data-driven credit customer experience offers personalization and low friction — it's a win-win for consumers and businesses.
Digital commerce is creating more ways to shop and more ways for fraud to hide. Discover how you can effectively prevent e-commerce fraud.
See how NeuroID helps businesses distinguish legitimate AI agents from fraud bots, while Agent Trust verifies agent-initiated transactions.
Artificial intelligence (AI) can raise the value of an organization’s data, but it also raises the standard that data needs to meet. According to Gartner, only 14% of leaders say their data is AI-ready. A dataset might be accurate enough for a monthly report or a traditional analytics workflow and still fall short when it is used to train, inform or operate an AI system. That is because AI readiness depends not only on whether data is clean, but also on whether it is appropriate for the specific use case, sufficiently complete and representative, properly governed and maintained as conditions change. For financial institutions, that distinction matters. Banks, credit unions and fintechs may use AI across areas such as credit decisioning, fraud detection, risk management and customer engagement. Each use case puts different demands on the underlying data. Understanding those demands is the first step toward building an AI-ready data foundation. What is AI-ready data? AI-ready data is data that has been prepared and managed, so it is fit for an intended AI use case. There is no single condition that makes every dataset ready for every AI application. A dataset suitable for a marketing model may need different attributes, controls and levels of completeness than data supporting a credit risk or fraud workflow. A practical way to think about AI readiness is through four characteristics: Reliable: Is the data accurate, complete, valid and consistent enough for its intended purpose? Relevant: Does it contain the right information, context, definitions, attributes and level of detail for the AI application? Safe: Are permissions, sensitive information, restricted attributes and governance requirements understood and appropriately managed? Representative: Does the data reflect the people, entities, behaviors or processes the AI will encounter when it is used? This is where AI-ready data differs from simply having clean data. Traditional data quality often focuses on issues such as invalid values, inconsistent formats, duplicates and missing information. Those fundamentals still matter. But AI introduces additional questions: Does the dataset represent the population the model will encounter? Can teams understand where the data came from and how it changed? Is its use permitted? Are changes in data quality or distribution being monitored? In other words, clean data is an important foundation. AI readiness asks the next question: Is this data fit for this AI use? How to make your data AI-ready: a practical framework Preparing data for AI does not have to mean rebuilding your data environment from scratch. A more practical approach is to assess the data against the intended use case and address the gaps that could affect trust, usability or governance. Resolve identities and establish trusted records AI systems can struggle when the same customer, account or entity appears differently across systems. Variations in names, addresses and other identifying information can create duplicates or fragmented records. That makes identity resolution and data matching an important starting point. Matching and deduplication can help organizations identify records that refer to the same entity and create a more trustworthy view of the data. Depending on the use case, this may mean establishing trusted records (or golden records) that downstream analytics and AI processes can use more consistently. The goal is not simply to eliminate duplicates. It is to give an AI workflow a clearer understanding of who or what each record represents. Standardize and maintain data hygiene Consistency matters when AI systems need to interpret information across multiple datasets. Different formats, incomplete fields, outdated contact details or inconsistent naming conventions can make it harder to connect and use information reliably. Data hygiene processes can help validate, cleanse and standardize information before it enters AI workflows. This foundation also makes matching, enrichment and governance more effective because records are being evaluated from a more consistent starting point. The right standard still depends on the use case. Rather than asking whether every field is perfectly clean, ask which data quality dimensions could materially affect the AI application. Enrich data when important context is missing AI can only work with the information it has available. In some cases, internal data may be accurate but incomplete for the intended purpose. Data enrichment can add relevant context or attributes to existing data, helping create a more complete dataset for analysis and decision-making. The principle here is relevance, not simply volume. More data is not automatically better data. Before adding attributes, determine what information the use case actually needs. An enrichment strategy should help fill meaningful gaps rather than expand the dataset without a clear purpose. Build governance and lineage into the process For AI, knowing what a data point says may not be enough. Organizations also need to understand where it came from, what it can be used for and who is responsible for it. Governance can help document elements such as: Data ownership and stewardship Approved purposes and permitted uses Policies and controls Data lineage and transformations Approvals and audit information Sensitive or restricted information These considerations are especially important in regulated industries such as financial services, where organizations may need evidence of how information moved through a process and how it was managed. Making governance part of the AI-data workflow can also help teams answer a fundamental question later: Why did we trust this data for this use? Monitor data readiness continuously AI readiness is not a one-time cleanup project. Customer information changes. New records enter systems. Data sources and business processes evolve. The characteristics of a dataset can also change over time. Ongoing profiling and quality monitoring can help teams identify changes earlier and determine whether data remains fit for the AI process it supports. That means measuring data health against the use case, not simply running a cleanup before launch and assuming the work is finished. A sustainable AI-ready data practice creates a feedback loop to assess, improve, monitor and reassess. AI-ready data in financial services Financial services offer a useful picture of why AI readiness depends on context. Consider three potential applications. Credit decisioning For AI decisioning, reliable and well-governed data can be foundational to how organizations develop and operate decision processes. The data needed will depend on the particular credit decisioning model and decision being made. Teams may need to consider completeness, consistent definitions, representativeness, lineage and controls around permitted use, not simply whether the source records pass conventional quality checks. Fraud detection and identity Fraud signals often come from multiple systems and interactions. Connecting information to the correct person, device, account or entity can therefore become particularly important. Strong identity resolution, matching and data quality practices can create a more consistent foundation for AI fraud detection and other fraud analytics. As autonomous technologies become part of digital interactions, identity questions are also expanding beyond people. Learn more about AI agent identity verification and the emerging challenges associated with establishing confidence in AI-driven transactions. Marketing and customer engagement AI-driven marketing may rely on information from customer, account, interaction and third-party data. Identity resolution can help connect fragmented records, while enrichment can add relevant contexts where appropriate. Data quality monitoring can then help organizations maintain the usefulness of that information as customer records and conditions change. Across these use cases, the underlying principle is the same: the definition of “ready” follows the business purpose. How we can help build an AI-ready data foundation Becoming AI-ready requires more than fixing individual errors. Organizations need a repeatable way to understand, improve, govern and monitor the data feeding important business processes. We support those steps through data quality solutions that can help organizations address different parts of the readiness framework. For example, identity resolution and matching can help connect records that represent the same entity. Aperture Data Studio brings data quality and governance capabilities together in a data intelligence solution. It can support activities including profiling, cleansing, standardization, matching, deduplication, enrichment, cataloging, governance and monitoring, helping organizations manage data as an ongoing business asset rather than a one-time preparation task. For organizations considering AI, that integrated approach can help shift the conversation from “Is our data clean?” to a more useful question: Is our data fit, trusted and governed for the AI use case we want to pursue? Explore the data intelligence platform
Learn how banks can convert rising fraud investment into protection customers recognize, value and feel in our recent report. Read more!
Experian NeuroID for Account Defense has been named Best Authentication Innovation in Datos Insights’ 2026 Fraud & AML Impact Awards.