Four Ways Financial Institutions Can Drive Financial Inclusion

by Corliss Hill 4 min read July 28, 2022

There’s no magic solution to undoing the decades of policies and prejudices that have kept certain communities unable to fully access our financial and credit systems. But you can take steps to address previous wrongs, increase financial inclusion and help underserved communities. If you want to engage consumers and keep them engaged, you could start with the following four areas of focus.

1. Find ways to build trust

Historical practices and continued discriminatory behavior have created justifiable distrust of financial institutions among some consumers.

In February 2022, Experian surveyed more than 1,000 consumers to better understand the needs and barriers of underserved communities. The respondents came from varying incomes, ethnicity and age ranges. Fewer than half of all the consumers (47 percent) said they trusted their bank’s personal finance advice and information, and that dropped to 41 percent among Black Americans.

In a follow-up webinar discussion of financial growth opportunities that benefitted underserved communities, we found that many financial institutions saw a connection between their financial inclusion efforts and building trust with customers and communities.

Here is a sample question and a breakdown of the primary responses:

What do you think is the greatest business advantage of executing financial inclusion in your financial institution or business?1

  • Building trust and retention with customers and communities (78%)
  • Increasing revenue by expanding to new markets (6%)
  • Enhancing our brand and commitment to DEI (14%)
  • Staying in alignment with regulator and compliance guidelines (2%)

Organizations may want to approach financial inclusion in different ways depending on their unique histories and communities. But setting quantifiable goals and creating a roadmap for your efforts is a good place to start.

2. Highlight data privacy and mobile access

If you want to win over new customers, you’ll need to address their most pressing needs and desires. Consumers’ top four considerations when signing up for a new account were consistent, but the specific results varied by race.
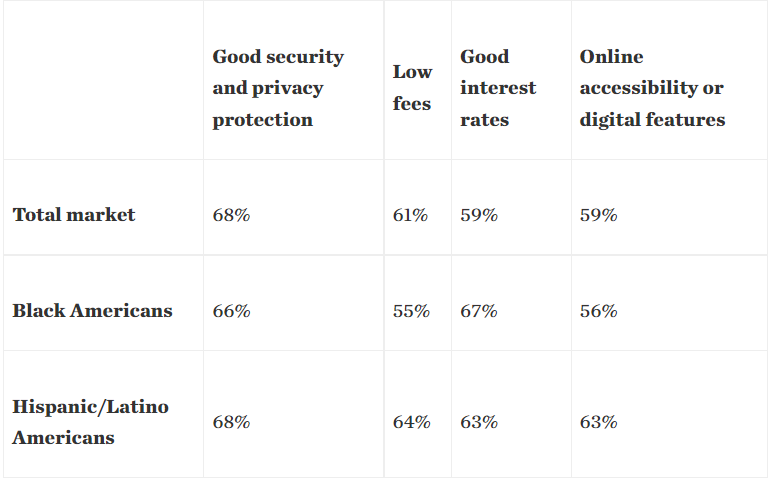
Keep this in mind as you consider messaging around the security and privacy measures. Also, consider how underserved communities might access your online services. Having an accessible and intuitive mobile app or mobile-friendly website is important and likely carries even more weight with these groups.

According to the Pew Research Center, as of 2021, around a quarter of Hispanic/Latino and 17% of Black Americans are smartphone-dependent — meaning they have a smartphone but don’t have broadband access at home. Low-income and minority communities are also less likely to live near bank branches or ATMs.

https://www.pewresearch.org/internet/fact-sheet/mobile/?menuItem=d40cde3f-c455-4f0e-9be0-0aefcdaeee00

3. Offer lower rates and fees

Low rates and fees are also a top priority across the board — everyone likes to save money. However, fewer Black and Hispanic households have $1,000 in savings or more compared to white households, which could make additional savings opportunities especially important.

There have been several recent examples of large banks and credit unions eliminating overdraft fees. And the Bank On National Account Standards can be a helpful framework if you offer demand deposit accounts.

Lowering interest rates on credit products can be more challenging, particularly when consumers don’t have a thick (or any) credit file. But by integrating expanded FCRA-regulated data sources and new scoring models, such as Experian’s Lift PremiumTM, creditors can score more applicants and potentially offer them more favorable terms.

4. Leverage credit education tools and messaging

For consumers who’ve had negative credit experiences, are new to credit, or are recent immigrants with little understanding of the U.S. credit system, building and using credit can feel daunting.

  • About 80% of women have little or no confidence in getting approved for credit or worry that applying could hurt them further.
  • Only 20% of consumers who make less than $35,000 a year say they’re “extremely” or “very” confident they’ll be approved for credit.

While most consumers haven’t used credit education tools before, they’re willing to try. More than 60 percent of Black and Hispanic respondents said they’re likely to sign up for free credit education tools and resources from their banks.

Offering these tools could be an opportunity to strengthen trust and help consumers build credit, which can also make it easier for them to qualify for financial products and services in the future.

Moving forward with financial inclusion

Broadening access to credit can be an important part of financial inclusion, and financial institutions can grow by expanding outreach to underserved communities. However, the relationship must be built on trust, security, and offerings that meet these consumers’ needs.

Through our Inclusion Forward™ initiative, Experian can support your financial inclusion goals — helping you empower underserved communities by helping them grow their financial futures.

Learn more about Experian financial inclusion solutions and financial inclusion tools.

Related Posts

Cash Flow Insights: Powering the Next Evolution in Lending

For decades, credit data has given lenders a trusted foundation for assessing risk. Now, consumer-permissioned cash flow data is adding another layer of insight into consumers’ financial lives, including income, spending, liquidity and changing financial obligations. The opportunity is significant. Nearly one in five consumers lacks access to or has damaged credit. New Experian research also shows that 60% of consumers who have previously been denied credit or received less favorable terms than expected believe the outcome would have been different if lenders had considered their recent income and banking activity alongside their credit history. 1,2 For lenders, cash flow insights can provide additional context about a consumer’s financial capacity and support more informed underwriting decisions. The next challenge is making those insights easier to use consistently and responsibly at scale. What are cash flow insights? Cash flow insights are derived from consumer-permissioned banking data and provide visibility into how money moves into and out of a consumer’s accounts. Depending on the information available, cash flow data can provide insight into financial behaviors such as: Income and income stability: Regular and irregular income streams and changes over time Spending and recurring expenses: Everyday spending patterns and ongoing financial obligations Account balances and liquidity: Available funds and changes in account balances Debt obligations: Loan payments and other recurring debt commitments Cash flow patterns: How money moves into and out of accounts over time Traditional credit information provides a rich history of how consumers have managed credit. Cash flow insights add context about their current financial activity and capacity, providing lenders with a more complete view of financial health. Cash flow insights can also add predictive value to risk assessment. Experian analysis shows Cashflow Score can deliver up to a 25% lift in predictive performance over conventional credit scores when tailored to targeted risk tiers.3 How lenders can put cash flow insights to work at scale As interest in cash flow insights grows, the conversation is moving beyond what the data can reveal to how financial institutions can use it consistently and responsibly. That requires standardized consumer reporting, clear governance and decision-ready insights that can work within established lending processes. The launch of Experian Cashflow Data Bureau at Vision 2026 reflects this shift from access to adoption. The new consumer reporting agency operates under the Fair Credit Reporting Act (FCRA) and is designed to help financial institutions adopt consumer-permissioned cash flow insights at scale. A key part of that foundation is the cash flow consumer report, which organizes consumer-permissioned banking information into a standardized consumer report regulated under the FCRA. This gives lenders a consistent foundation for incorporating cash flow information into lending decisions while providing consumers with access to the information in their report. Turning greater visibility into better decisions The next evolution in credit isn’t about choosing between traditional credit and cash flow data. Each provides a different perspective. Traditional credit information offers deep insight into how consumers have managed credit over time. Cash flow insights can add context about financial activity and capacity. Bringing those perspectives together can give lenders greater visibility into consumers’ financial health and help them better distinguish between risk and resilience, support more informed decisions and identify opportunities to responsibly expand access to credit. As cash flow adoption continues to grow, its value will come from how effectively it complements the information lenders already use. The opportunity isn't simply to see more data. It's to turn that additional visibility into smarter, more informed decisions. Explore how Experian Cashflow Data Bureau is helping financial institutions put consumer-permissioned cash flow insights into practice at scale. Learn more [1] Federal Reserve Bank of New York, The Market for Credit Building: Demand, Product Characteristics and Consumer Uses, 2026. [2] Experian commissioned Atomik Research to conduct an online survey of 2,000 U.S. adults age 18+. Fieldwork took place July 16–21, 2026. Margin of error: +/- 2.2 percentage points at a 95% confidence level. [3] Based on Experian analysis when Cashflow Score is compared with conventional credit scores, tailored to targeted risk tiers. Predictability based on KS.

October 14, 2026 by Julie Lee
The Three Onboarding Fraud Pain Points That Slow Growth (And How to Solve Them) 

Effective fraud prevention is critical to balancing security and customer experience during onboarding. Learn more!

October 12, 2026 by Charles Hunter
How Rental Data Is Expanding Financial Opportunity for Millions of Renters 

Discover how rental payment reporting can expand credit access, strengthen credit profiles and improve risk assessment for renters and housing providers.

October 8, 2026 by Manjit Sohal

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe

