Getting the Job Done with Alternative Credit Data

by Kelly Nguyen 3 min read July 9, 2019

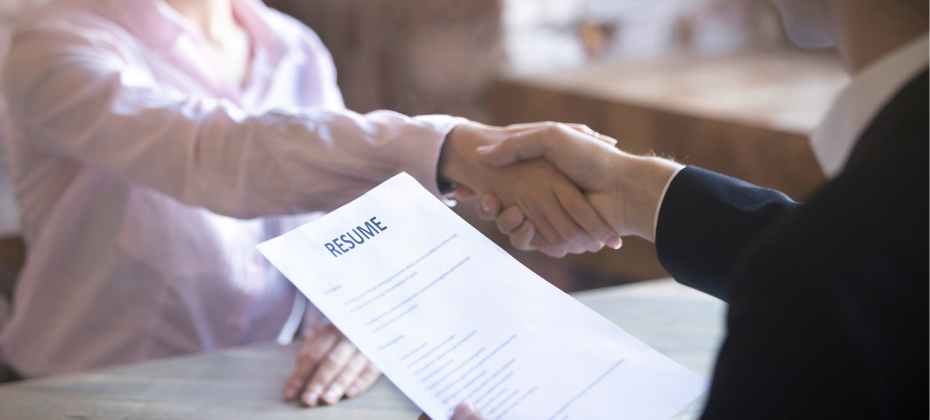
Would you hire a new employee strictly by their resume? Surely not – there’s so much more to a candidate than what’s written on paper. With that being said, why would you determine your consumers’ creditworthiness based only on their traditional credit score?

Resumes don’t always give you the full picture behind an applicant and can only tell a part of someone’s story, just as a traditional credit score can also be a limited view of your consumers. And lenders agree – findings from Experian’s 2019 State of Alternative Credit Data revealed that 65% of lenders are already leveraging information beyond the traditional credit report to make lending decisions.

So in addition to the resume, hiring managers should look into a candidate’s references, which are typically used to confirm a candidate’s positive attributes and qualities. For lenders, this is alternative credit data.

References are supplemental but essential to the resume, and allow you to gain new information to expand your view into a candidate – synonymous to alternative credit data’s role when it comes to lending.

Lenders are tasked with evaluating their consumers to determine their stability and creditworthiness in an effort to prevent and reduce risk. While traditional credit data contains core information about a consumer’s credit data, it may not be enough for a lender to formulate a full and complete evaluation of the consumer. And for over 45 million Americans, the issue of having no credit history or a “thin” credit history is the equivalent of having a resume with little to no listed work experience.

Alternative credit data helps to fill in the gaps, which has benefits for both lenders and consumers. In fact, 61% of consumers believe adding payment history would have a positive impact on their credit score, and therefore are willing to share their data with lenders.

Alternative credit data is FCRA-compliant and includes information like alternative finance data, rental payments, utility payments, bank account information, consumer-permissioned data and full-file public records. Because this data shows a holistic view of the customer, it helps to determine their ability to repay debts and reveals any delinquent behaviors. These insights help lenders to expand their consumer lending universe– all while mitigating and preventing risk.

The benefits can also be seen for home-based and small businesses. Fifty percent of all US small businesses are home-based, but many small business owners lack visibility due to their thin-file nature – making it extremely difficult to secure bank loans and capital to fund their businesses. And, younger generations and small business owners account for 58% of business owners who rely on short term lending.

By leveraging alternative credit data, lenders can get greater insights into a small business owner’s credit profile and gauge risk. Entrepreneurs can also benefit from this information being used to build their credit profiles – making it easier for them to gain access to investment capital to fund their new ventures.

Like a hiring manager, it’s important for lenders to get a comprehensive view to find the most qualified candidates. Using alternative credit data can expand your choices  – read our 2019 State of Alternative Credit Data Whitepaper to learn more and register for our upcoming webinar.
Register Now

Related Posts

Ask the Expert: The Future of Lending Starts With Identity With Shawn Rife and Brian Cardona

Identity intelligence and alternative data can help lenders validate consumers and support more informed decisions across the customer lifecycle.

September 16, 2026 by Julie Lee
Financial Institutions Are Rethinking Customer Acqusition

Customer acquisition strategies are constantly evolving toward more precise targeting. From a marketing lens, you can track every step, optimize communication channels and still miss the person most likely to convert. Attribution can tell us which channels work and automation can make marketing spend more efficient. But both assume we know who is actually on the other end. Financial institutions are learning that finding audiences and targeting them is no longer the biggest challenge. As acquisition optimization marketing becomes more sophisticated, teams can measure and act on more signals than before. What they can't always know is whether the person on the receiving end is real. Customer acquisition has evolved into an identity problem. The challenge is not that every questionable signal represents malicious activity. It's that acquisition systems must make increasingly intelligent decisions with an imperfect understanding of who they're actually engaging. When identities are fragmented, duplicated, temporary or synthetic, optimization becomes a question of trust as much as targeting. When your signals don't reliably identify customers The customer journey often includes searching, filling out a form, creating an account, requesting a quote and subscribing. All of these signals work well when identity is relatively stable.  However, financial institutions are finding that these signals are becoming less reliable. A single person can operate across multiple personas, devices, browsers, aliases, accounts and intermediaries while several apparent “people” may actually represent one underlying actor. Financial instituions are finding: Fragmented customer signals Difficulty distinguishing an old account from a new one Different digital pathways associated with the same individual Signals that are generated by automation Real customers getting flagged because signals are too thin to evaluate confidently Legacy signals continue to be challenged Marketing has historically treated intent as a valuable signal because intent was relatively difficult to produce. A search required human intent. A form required someone to fill it out. An inquiry implied a meaningful amount of human effort. Financial institutions are already combating AI-enabled fraud, and now marketing teams are starting to face it on a massive scale. AI can mimic human behavior by researching products, comparing prices, filling out forms, creating accounts and signing up for services. A valid email address is no longer enough. Marketers need to know: How long has it existed? How recently has it been active? Does its activity appear consistent or suddenly anomalous? Has it gone dormant and returned? Is it associated with patterns that suggest stability or unusual behavior? How to build on your strongest signal Email remains one of the most persistent identifiers in digital commerce, following people across devices, platforms, transactions, subscriptions, accounts and years of activity. For over two decades, this has shaped how AtData thinks about identity. Now, as part of Experian, it’s shaping how an entire platform and team approach identity. A marketer doesn’t need every prospect to have existed online for twenty years. But understanding whether a newly acquired prospect has meaningful identity context can dramatically improve the quality of the decision being made around it. Better identity intelligence can help organizations reduce unnecessary friction by improving their ability to recognize legitimate customers. With a strong identity foundation, marketing teams can better address: Which audiences are more likely to convert? Which leads are high quality? Which channels are driving incremental growth? What do the best prospects look like? The value isn't simply having an email address. It's understanding the history and behavioral context associated with it. That context can provide a stronger digital identity signal, helping marketers understand how long they have been active, whether its behavior is consistent with that of a real person and whether current activity aligns with past patterns. It continues to be one of the most persistent identifiers in digital commerce. An infrastructure built for what's coming The acquisition of AtData by Experian reflects a fundamental shift in how identity infrastructure needs to work. Experian's scale and decisioning capabilities, combined with AtData's real-time email intelligence, create a strong platform. Read more about the why behind the acquisition and see how email works as an identity anchor for fraud prevention. Contact us to learn about our customer acquisition solutions

September 15, 2026 by Zohreen Ismail
As Electric Vehicle Adoption Eases, Dealers Can Find New Opportunities To Reach Consumers

After years of rapid growth, new electric vehicle (EV) registrations have moderated, and the EV market has entered a new chapter. But slower growth shouldn’t be mistaken for disappearing demand, with data suggesting the reality is much more nuanced. According to Experian Automotive’s Automotive Consumer Trends Report: Q2 2026, battery EVs accounted for 8.21% of new retail registrations in the last 12 months, down from 9.23% a year earlier. However, consumers aren’t simply walking away from electrification. In fact, more than one million new EVs were registered during the past 12 months and the used EV market recorded more than 540,000 registrations over the same period. The opportunity may be less about waiting for the EV market to grow and more about understanding where EV demand is present, who is driving them, and how to reach those consumers more effectively. Who is likely to purchase an EV and what vehicle types are they interested in? Understanding who’s in the market for an EV can allow dealers to position themselves around consumers’ needs as they choose a vehicle that fits their everyday lifestyle. In the second quarter of 2026, Millennials and Gen X accounted for 67.83% of new EV registrations, nearly 10 percentage points above their combined share of all new, retail registrations. Millennials were also the largest generational audience across both new and used EV market share, coming in at 35.76% and 38.42%, respectively. It’s important to consider that the EV shopper isn’t necessarily looking for an unfamiliar or new type of vehicle. In many cases, they’re seemingly looking for an electric version of the practical vehicle they already know. For instance, SUVs accounted for 77.47% of new EV registrations in Q2 2026, which was similar to SUVs’ 63.49% share of all new retail registrations. For these shoppers, creating messaging around value, practicality, and available choices may resonate differently than premium technology messaging aimed at some new-EV prospects. The more precisely dealers can identify those audiences, the less they need to depend on broad EV market momentum to generate demand. To learn more about EV insights, view the full Automotive Consumer Trends Report: Q2 2026 presentation.

September 15, 2026 by Kirsten Von Busch

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe