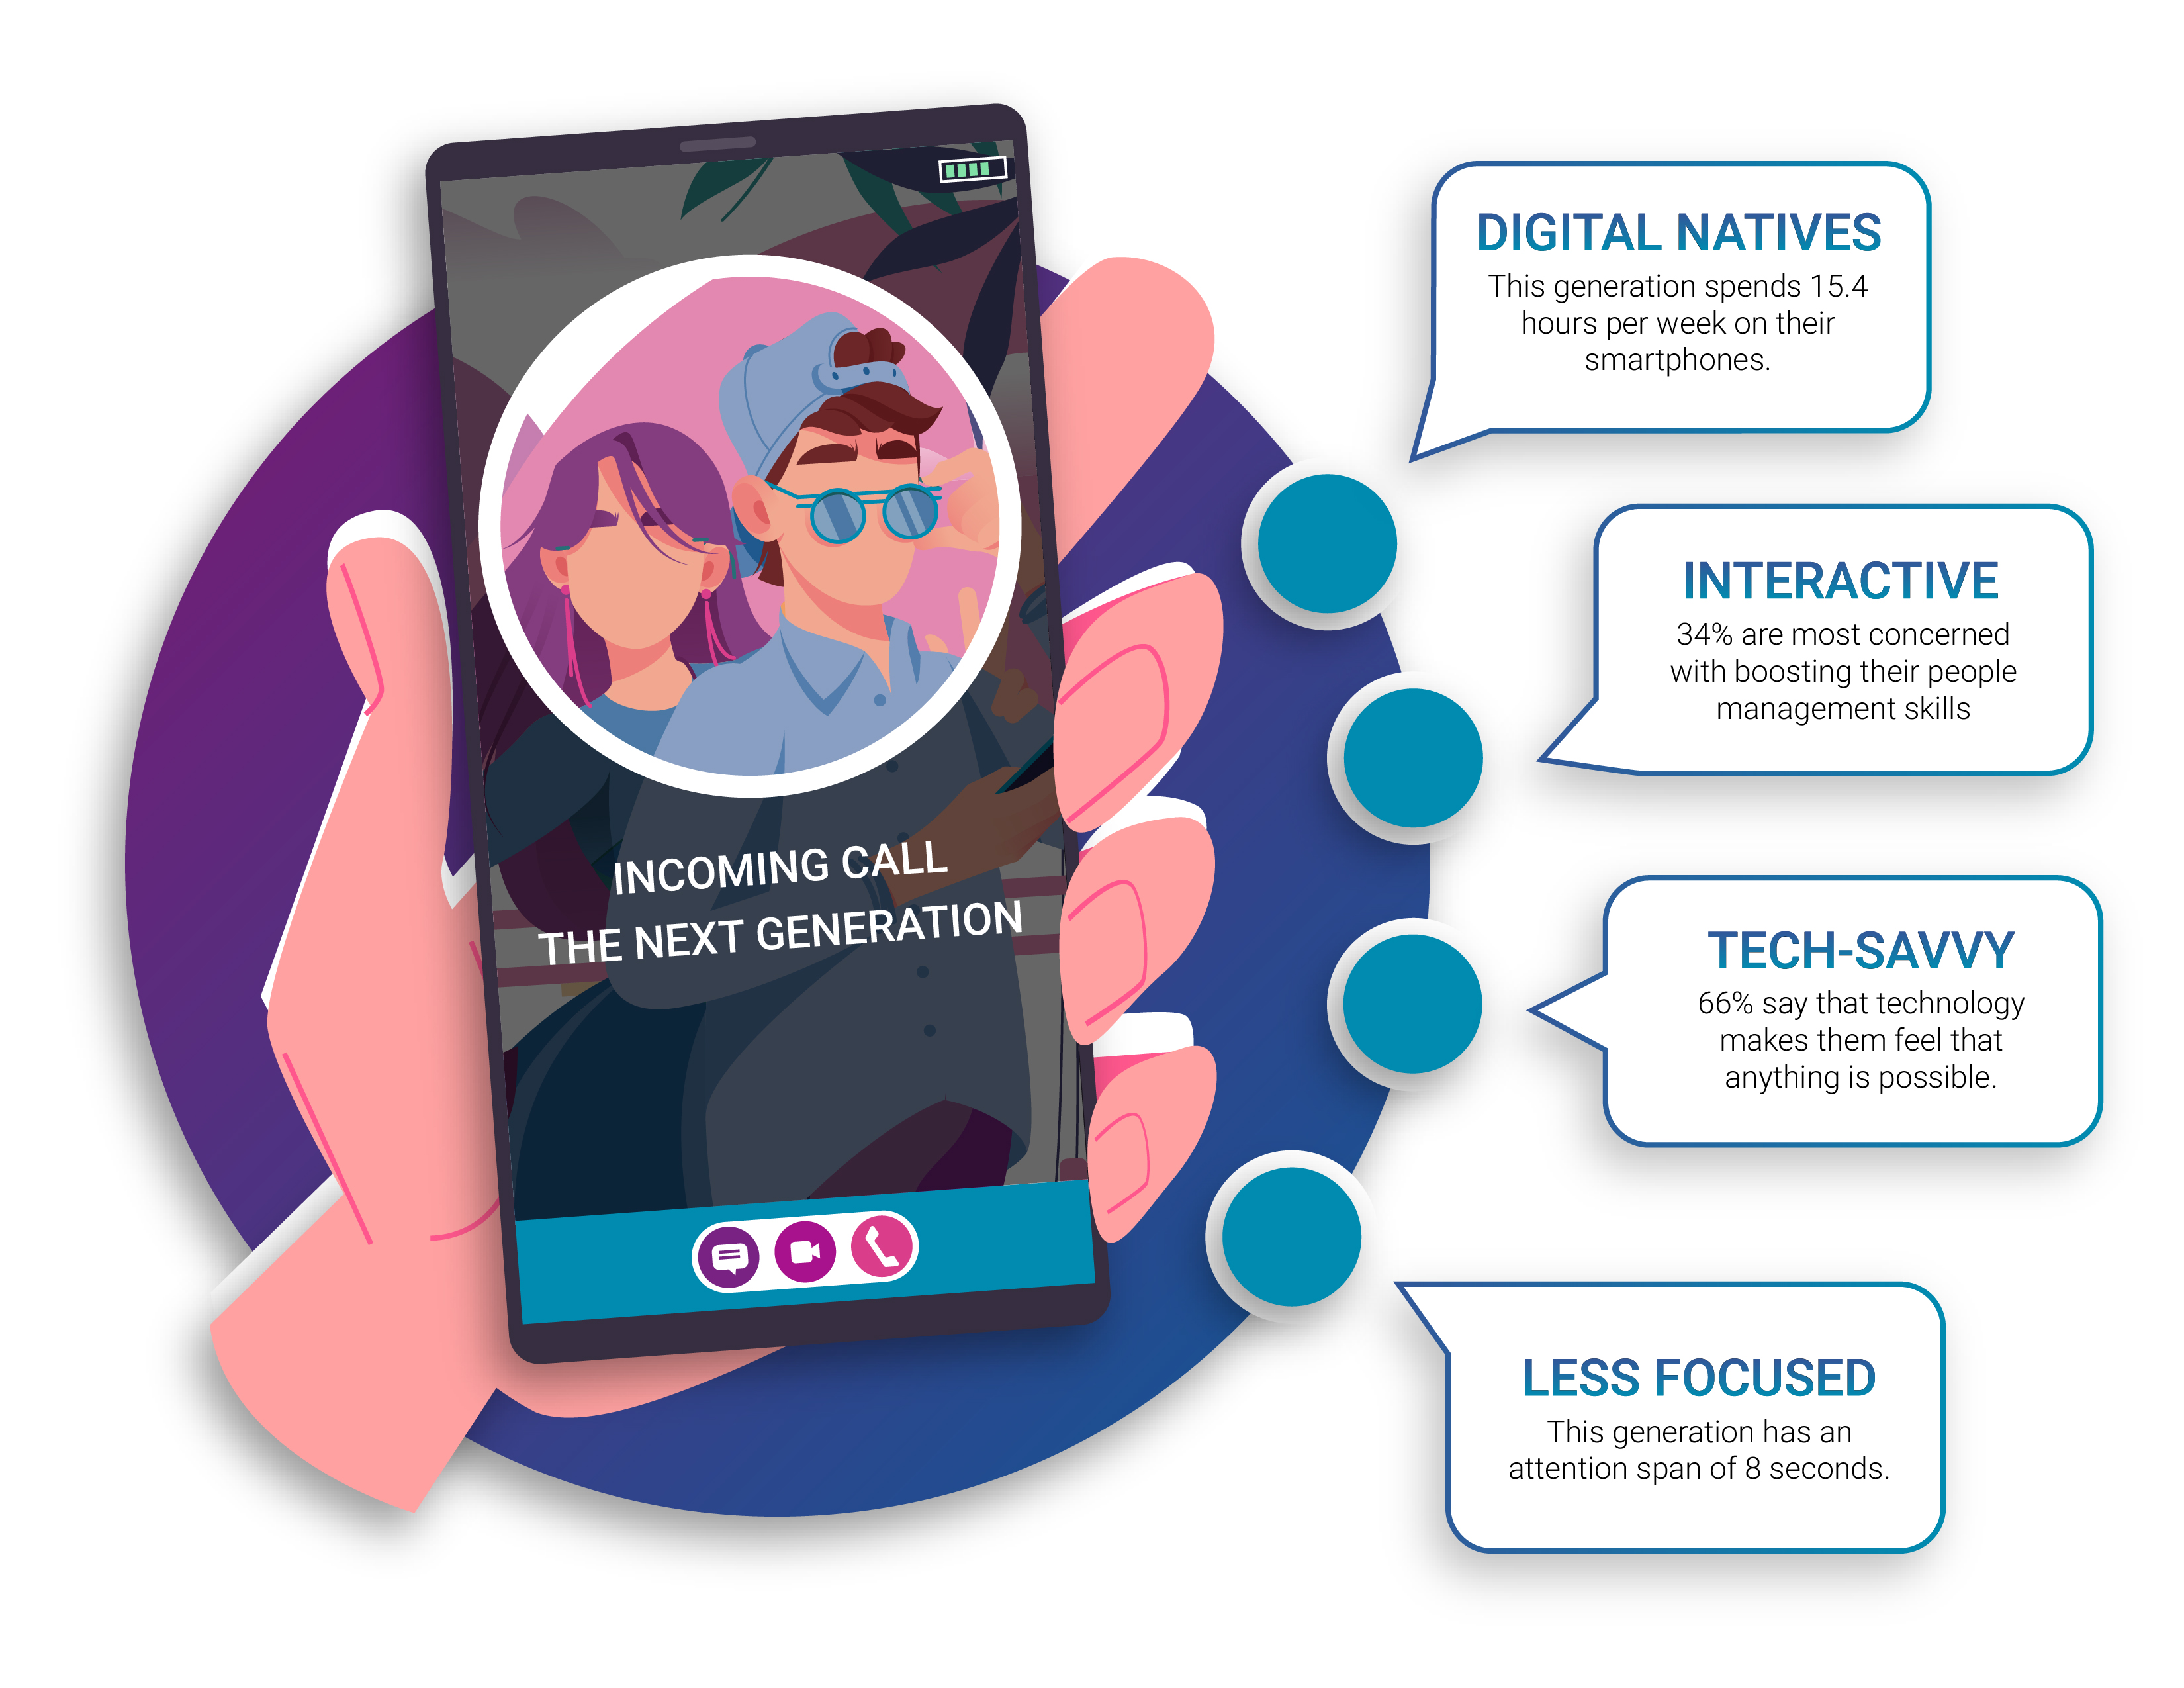
Gen Z, or “Zoomers,” born from 1997 to 2012, are molded by modern transformations. They have witnessed events from post-9/11 impacts to the rise of the internet and the COVID-19 crisis. As early adopters of technology, their lives are intertwined with smartphones, online shopping, social platforms, cloud services, emerging fintech, and artificial intelligence. They are called “digital natives” as they are the first generation to grow up with internet as part of their daily life.
Research generally indicates that this post-millennial generation values practicality, favoring financial stability over entrepreneurial pursuits. They appreciate communication tailored to them and often employ social media to cultivate their personal brands. As a generation growing up immersed in technology, they tend to choose digital interactions, seeking to forge robust, secure, genuine, and unconstrained digital experiences.
The challenge of identity verification
Identity verification presents a considerable challenge for Generation Z. According to a Fortune survey, close to 50% of this demographic regrets not opening financial accounts earlier, citing a lack of readiness to join the financial ecosystem by the age of 18. Consequently, this has given rise to “digital ghosts”—people with minimal or nonexistent financial histories who face challenges when trying to utilize financial services.
The 2009 Credit Card Accountability Responsibility and Disclosure Act mandates that individuals under 21 need a cosigner or show income proof to get a credit card, hindering their early financial involvement. Moreover, conventional identity checks are becoming less reliable due to the surge in identity theft.
Innovative solutions for verifying Gen Z
Verifying identities and preventing fraud among Gen Z presents unique challenges due to their digital-native status and limited credit histories. Here are some effective strategies and approaches that financial institutions can adopt to address these challenges:
-
Leveraging alternative data sources
- Academic records leverage information from higher learning institutions such as universities, colleges, and vocational schools. This data can be vital for authenticating the identities of younger individuals who may lack a substantial credit history.
- Employment verification retrieve data confirming the identity and employment status, especially focusing on Gen Z who are new to the job market.
- Utility and telecom records leverage payment histories for utilities, phone bills, and other recurring services, which can provide additional layers of identity verification.
- Alternative financial data includes online small dollar lenders, online installment lenders, single payment, line of credit, storefront small dollar lenders, auto title and rent-to-own.
-
Phone-Centric ID
- Phone-Centric Identity refers to technology that leverages and analyzes mobile, telecom, and other signals for the purposes of identity verification, identity authentication, and fraud prevention. Phone-Centric Identity relies on billions of signals from authoritative sources pulled in real time, making it a powerful proxy for digital identity and trust.
-
Advance authentication technologies
- Behavioral biometrics analyze user behaviors such as typing patterns, navigation habits, and device usage. These subtle behaviors can help create a unique profile for each user, making it difficult for fraudsters to impersonate them.
- Adaptive risk-based authentication that adjusts the level of security based on the user’s behavior, location, device, and other factors. For example, a higher level of verification might be required for transactions that are deemed unusual or high-risk.
-
Real-time fraud detection
- AI and machine learning: Deploy AI and machine learning algorithms to analyze transaction patterns and detect anomalies in real-time. These technologies can identify suspicious activities and flag potential fraud.
- Fraud analytics: Use predictive analytics to assess the likelihood of fraud based on historical data and current behavior. This approach helps in proactively identifying and mitigating fraudulent activities.
-
Secure digital onboarding
- Digital identity verification: Implement digital onboarding processes that include online identity verification with real-time document verification. Users can upload government-issued IDs and take selfies to confirm their identity.
- Video KYC (Know Your Customer): Use video calls to conduct KYC processes, allowing bank representatives to verify identities and documents remotely via automated identity verification. This method is secure and convenient for tech-savvy Gen Z customers.
Make identity verification easy
To authenticate identities and combat fraud within the Gen Z population, financial organizations need to implement a comprehensive strategy utilizing innovative technologies, non-traditional data, and strong protective protocols. Such actions will enable the creation of a trustworthy and frictionless banking environment that appeals to a generation adept in digital interactions, thereby establishing trust and encouraging enduring connections.
To learn more about Experian’s automated identity verification solutions, visit our website.


