Credit & Risk
If you’re a manager at a business that lends to consumers or otherwise extends credit, you certainly are aware that 10-15% of your current customers and prospective future customers are among the approximately 27 million consumers who are now – or will soon be -- fitting another bill into their monthly budgets. Early in the COVID-19 pandemic, the government issued a pause on federal student loan payments and interest. Now that the payment pause has expired, millions of Americans face a new bill averaging more than $200. Will they pay you first? If this is your concern, you aren’t alone: Experian recently held a webinar that discussed how the end of the student loan pause might affect businesses. When we surveyed the webinar attendees, nearly 3 out of 4 responses included Risk Management as a main concerns now. Another top concern is about credit scores. Lenders and investors use credit scores – bureau scores such FICO® or VantageScore® credit score or custom credit scores proprietary to their institution – to predict credit default risk. The risk managers at those companies want to know to what extent they can continue to rely on those scores as Federal student loan payments come due and consumers experience payment shock. I’ve analyzed a large and statistically meaningful sample (10% of the US consumer population in Experian’s Ascend Sandbox) to shed some light on that question. As background information, the average consumer with student loans had lower scores before the pandemic than the average of the general population. One of my Experian colleagues has explored some of the reasons at https://www.experian.com/blogs/ask-experian/research/average-student-loan-payments). Here are some of the things we can learn from comparing the credit data of the two groups of people. I looked at a period from 2019 and from 2023 to see how things have changed: Average credit scores increased during the pandemic, continuing a long-term trend during which more Americans have been willing and able to meet all their obligations. During the COVID Public Health Emergency, consumers with student loans brought up their scores by an average of 25 points; that was 7 points more than consumers without student loans. Another way to look at it: in 2019, consumers with student loans had credit scores 23 points lower than consumers without. By 2023, that difference had shrunk to 16 points. Experian research shows that there will be little immediate impact on credit scores when the new bills come due. Time will tell whether these increased credit scores accurately reflect a reduction in the risk that consumers will default on other bills such as auto loans or bankcards soon, even as some people fit student loan bills into their budgets. It is well-known that many people saved money during the public health emergency. Since then, the personal savings rate has fallen from a pandemic high of 32% to levels between 3% and 5% this year – lower than at any point since the 2009 recession. In an October 2023 Experian survey, only 36% of borrowers said they either set aside funds or they planned using other financial strategies specifically for the resumption of their student loan payments. Additional findings from that study can be found here. Furthermore, there are changes in the way your customers have used their credit cards over the last four years: Consumers’ credit card balances have increased over the last four years. Consumers with student loans have balances that are on average $282 (4%) more now than in 2019. That is a significantly smaller increase than for consumers without student loans, whose total credit card debt increased by an average of $1,932 (26%). Although their balances increased, the ratio of consumers’ total revolving debt balances to their credit limits (utilization) changed by less than 1% for both consumers with student loans and consumers without. In 2019, the utilization ratio was 9.8 percentage points lower for consumers with student loans than consumers without. Four years later, the difference is nearly the same (9.6 points). We can conclude that many student loan borrowers have been very responsible with credit during the Public Health Emergency. They may have been more mindful of their credit situation, and some may have planned for the day when their student loan payments will be due. As the student loan pause come to an end, there are a few things that lenders and other businesses should be doing to be ready: Even if you are not a student loan lender, it is important to stay on top of the rapidly evolving student loan environment. It affects many of your customers, and your business with them needs to adapt. Anticipate that fraudsters and abusers of credit will be creative now: periods of change create opportunities for them and you should be one step ahead. Build optimized strategies in marketing, account opening, and servicing. Consider using machine learning to make more accurate predictions. Those strategies should reflect trends in payments, balances, and utilization; older credit scores look at a single point in time. Continually refresh data about your customers—including their credit scores and important attributes related to payments, balances, and utilization patterns. Look for alternative data that will give you a leg up on the competition. In the coming weeks and months, Experian’s data scientists will monitor measures of performance of the scores and attributes that you depend on in your data-driven strategies — particularly focusing on the Kolmogorov-Smirnov (KS) statistics that will show changes in the predictive power of each score and attribute. (If you are a data-driven business, your data science team or a trusted partner should be doing the same thing with a more specific look at your customer base and business strategies.) In future reports and blog posts, we’ll shed light on the impact student loans are having on your customers and on your business. In the meantime, for more information about how to use data and advanced analytics to grow while controlling costs and risks, all while staying in compliance and providing a good customer experience, visit our website.
With great risk comes great reward, as the saying goes. But when it comes to business, there's huge value in reducing and managing that risk as much as possible to maximize benefits — and profits. In today's high-tech strategic landscape, financial institutions and other organizations are increasingly using risk modeling to map out potential scenarios and gain a clearer understanding of where various paths may lead. What is a risk model? A risk model is a representation of a particular situation that's created specifically for the purpose of assessing risk. That risk model is then used to evaluate the potential impacts of different decisions, paths and events. From assigning interest rates and amortization terms to deciding whether to begin operating in a new market, risk models are a safe way to analyze data, test assumptions and visualize potential scenarios. Risk models are particularly valuable in the credit industry. Credit risk models and credit risk analytics allow lenders to evaluate the pluses and minuses of lending to clients in specific ways. They are able to consider the larger economic environment, as well as relevant factors on a micro level. By integrating risk models into their decision-making process, lenders can refine credit offerings to fit the assessed risk of a particular situation. It goes like this: a team of risk management experts builds a model that brings together comprehensive datasets and risk modeling tools that incorporate mathematics, statistics and machine learning. This predictive modeling tool uses advanced algorithmic techniques to analyze data, identify patterns and make forecasts about future outcomes. Think of it as a crystal ball, but with science behind it. Your team can then use this risk model for a wide range of applications: refining marketing targets, reworking product offerings or reshaping business strategies. How can risk models be implemented? Risk models consolidate and utilize a wide variety of data sets, historical benchmarks and qualitative inputs to model risk and allow business leaders to test assumptions and visualize the potential results of various decisions and events. Implementing risk modeling means creating models of systems that allow you to adjust variables to imitate real-world situations and see what the results might be. A mortgage lender, for example, needs to be able to predict the effects of external and internal policies and decisions. By creating a risk model, they can test how scenarios such as falling interest rates, rising unemployment or a shift in loan acceptance rates might affect their business, and make moves to adjust their strategies accordingly. One aspect of risk modeling that can't be underestimated is the importance of good data, both quantitative and qualitative. Efforts to implement or expand risk modeling should begin with refining your data governance strategy. Maximizing the full potential of your data also requires integrating data quality solutions into your operations in order to ensure that the building blocks of your risk model are as accurate and thorough as possible. It's also important to ensure your organization has sufficient model risk governance in place. No model is perfect, and each comes with its own risks. But these risks can be mitigated with the right set of policies and procedures, some of which are part of regulatory compliance. With a comprehensive model risk management strategy, including processes like back testing, benchmarking, sensitivity analysis and stress testing, you can ensure your risk models are working for your organization — not opening you up to more risk. How can risk modeling be used in the credit industry? Risk modeling isn't just for making credit decisions. For instance, you might model the risk of opening or expanding operations in an underserved country or the costs and benefits of an existing one that is underperforming. In information technology, a critical branch of virtually every modern organization, risk modeling helps security teams evaluate the risk of malicious attacks.Banking and financial services is one industry for which understanding and planning for risk is key, not only for business reasons but to align with relevant regulations. The mortgage lender mentioned above, for example, might use credit risk models to better predict risk, enhance the customer journey and ensure transparency and compliance.It's important to highlight that risk modeling is a guide, not a prophecy. Datasets can contain flaws or gaps, and human error can happen at any stage. It's also possible to rely too heavily on historical information, and while they say history repeats itself, they don't mean it repeats exactly. That's especially true in the face of novel challenges, such as the rise of artificial intelligence. Making the best use of risk modeling tools involves not just optimizing software and data but using expert insight to interpret predictions and recommendations so that decision-making comes from a place of breadth and depth. Why are risk models important for banks and financial institutions? In the world of credit, optimizing risk assessment has clear ramifications when meeting overall business objectives. By using risk modeling to better understand your current and potential clients, you are positioned to offer the right credit products to the right audience and take action to mitigate risk. When it comes to portfolio risk management, having adequate risk models in place is paramount to meet targets. And not only does implementing quality portfolio risk analytics help maximize sales opportunities, but it can also help you identify risk proactively to avoid costly mistakes down the road. Risk mitigation tools are a key component of any risk modeling strategy and can help you maintain compliance, expose potential fraud, maximize the value of your portfolio and create a better overall customer experience. Advanced risk modeling techniques In the realm of risk modeling, the integration of advanced techniques like machine learning (ML) and artificial intelligence (AI) is revolutionizing how financial institutions assess and manage risk. These technologies enhance the predictive power of risk models by allowing for more complex data processing and pattern recognition than traditional statistical methods.Machine learning in risk modeling: ML algorithms can process vast amounts of unstructured data – such as market trends, consumer behavior and economic indicators — to identify patterns that may not be visible to human analysts. For instance, ML can be used to model credit risk by analyzing a borrower’s transaction history, social media activities and other digital footprints to predict their likelihood of default beyond traditional credit scoring methods.Artificial intelligence in decisioning: AI can automate the decisioning process in risk management by providing real-time predictions and risk assessments. AI systems can be trained to make decisions based on historical data and adjust them as they learn from new data. This capability is particularly useful in credit underwriting where AI algorithms can make rapid decisions based on market conditions.Financial institutions looking to leverage these advanced techniques must invest in robust data infrastructure, skilled personnel who can bridge the gap between data science and financial expertise, and continuous monitoring systems to ensure the models perform as expected while adhering to regulatory standards. Challenges in risk model validation Validating risk models is crucial for ensuring they function appropriately and comply with regulatory standards. Validation involves verifying both the theoretical foundations of a model and its practical implementation. Key challenges in model validation Model complexity: As risk models become more complex, incorporating elements like ML and AI, they become harder to validate. Complex models can behave in unpredictable ways, making it difficult to understand why they are making certain decisions (the so-called "black box" issue).Data quality and availability: Effective validation requires high-quality, relevant data. Issues with data completeness, accuracy or relevance can lead to incorrect model validations. Best practices in model validation Regulatory compliance: With regulations continually evolving, maintaining compliance with risk models can be challenging. Different jurisdictions may have varying requirements, further complicating validation processes.Regular reviews: Continuous monitoring and periodic reviews help ensure that models remain accurate over time and adapt to changing market conditions.Third-party audits: Independent reviews by external experts can provide an unbiased assessment of the risk model’s performance and compliance.These practices help institutions maintain the reliability and integrity of their risk models, ensuring that they continue to function as intended and comply with regulatory requirements. How Experian can help Risk is inherent to business, and there's no avoiding it entirely. But integrating credit risk modeling into your operations can ensure stability and profitability in a rapidly evolving business landscape. Start with Experian's credit modeling services, which use expansive data, analytical expertise and the latest credit risk modeling methodologies to better predict risk and accelerate growth. Learn more
Model governance is growing increasingly important as more companies implement machine learning model deployment and AI analytics solutions into their decision-making processes. Models are used by institutions to influence business decisions and identify risks based on data analysis and forecasting. While models do increase business efficiency, they also bring their own set of unique risks. Robust model governance can help mitigate these concerns, while still maintaining efficiency and a competitive edge. What is model governance? Model governance refers to the framework your organization has in place for overseeing how you manage your development, model deployment, validation and usage.1 This can involve policies like who has access to your models, how they are tested, how new versions are rolled out or how they are monitored for accuracy and bias.2 Because models analyze data and hypotheses to make predictions, there's inherent uncertainty in their forecasts.3 This uncertainty can sometimes make them vulnerable to errors, which makes robust governance so important. Machine learning model governance in banks, for example, might include internal controls, audits, a thorough inventory of models, proper documentation, oversight and ensuring transparent policies and procedures. One significant part of model governance is ensuring your business complies with federal regulations. The Federal Reserve Board and the Office of the Comptroller of the Currency (OCC) have published guidance protocols for how models are developed, implemented and used. Financial institutions that utilize models must ensure their internal policies are consistent with these regulations. The OCC requirements for financial institutions include: Model validations at least once a year Critical review by an independent party Proper model documentation Risk assessment of models' conceptual soundness, intended performance and comparisons to actual outcomes Vigorous validation procedures that mitigate risk Why is model governance important — especially now? More and more organizations are implementing AI, machine learning and analytics into their models. This means that in order to keep up with the competition's efficiency and accuracy, your business may need complex models as well. But as these models become more sophisticated, so does the need for robust governance.3 Undetected model errors can lead to financial loss, reputation damage and a host of other serious issues. These errors can be introduced at any point from design to implementation or even after deployment via inappropriate usage of the model, drift or other issues. With model governance, your organization can understand the intricacies of all the variables that can affect your models' results, controlling production closely with even greater efficiency and accuracy. Some common issues that model governance monitors for include:2 Testing for drift to ensure that accuracy is maintained over time. Ensuring models maintain accuracy if deployed in new locations or new demographics. Providing systems to continuously audit models for speed and accuracy. Identifying biases that may unintentionally creep into the model as it analyzes and learns from data. Ensuring transparency that meets federal regulations, rather than operating within a black box. Good model governance includes documentation that explains data sources and how decisions are reached. Model governance use cases Below are just three examples of use cases for model governance that can aid in advanced analytics solutions. Credit scoring A credit risk score can be used to help banks determine the risks of loans (and whether certain loans are approved at all). Governance can catch biases early, such as unintentionally only accepting lower credit scores from certain demographics. Audits can also catch biases for the bank that might result in a qualified applicant not getting a loan they should. Interest rate risk Governance can catch if a model is making interest rate errors, such as determining that a high-risk account is actually low-risk or vice versa. Sometimes changing market conditions, like a pandemic or recession, can unintentionally introduce errors into interest rate data analysis that governance will catch. Security challenges One department in a company might be utilizing a model specifically for their demographic to increase revenue, but if another department used the same model, they might be violating regulatory compliance.4 Governance can monitor model security and usage, ensuring compliance is maintained. Why Experian? Experian® provides risk mitigation tools and objective and comprehensive model risk management expertise that can help your company implement custom models, achieve robust governance and comply with any relevant federal regulations. In addition, Experian can provide customized modeling services that provide unique analytical insights to ensure your models are tailored to your specific needs. Experian's model risk governance services utilize business consultants with tenured experience who can provide expert independent, third-party reviews of your model risk management practices. Key services include: Back-testing and benchmarking: Experian validates performance and accuracy, including utilizing statistical metrics that compare your model's performance to previous years and industry benchmarks. Sensitivity analysis: While all models have some degree of uncertainty, Experian helps ensure your models still fall within the expected ranges of stability. Stress testing: Experian's experts will perform a series of characteristic-level stress tests to determine sensitivity to small changes and extreme changes. Gap analysis and action plan: Experts will provide a comprehensive gap analysis report with best-practice recommendations, including identifying discrepancies with regulatory requirements. Traditionally, model governance can be time-consuming and challenging, with numerous internal hurdles to overcome. Utilizing Experian's business intelligence and analytics solutions, alongside its model risk management expertise, allows clients to seamlessly pass requirements and experience accelerated implementation and deployment. Experian can optimize your model governance Experian is committed to helping you optimize your model governance and risk management. Learn more here. References 1Model Governance," Open Risk Manual, accessed September 29, 2023. https://www.openriskmanual.org/wiki/Model_Governance2Lorica, Ben, Doddi, Harish, and Talby, David. "What Are Model Governance and Model Operations?" O'Reilly, June 19, 2019. https://www.oreilly.com/radar/what-are-model-governance-and-model-operations/3"Comptroller's Handbook: Model Risk Management," Office of the Comptroller of the Currency. August 2021. https://www.occ.treas.gov/publications-and-resources/publications/comptrollers-handbook/files/model-risk-management/pub-ch-model-risk.pdf4Doddi, Harish. "What is AI Model Governance?" Forbes. August 2, 2021. https://www.forbes.com/sites/forbestechcouncil/2021/08/02/what-is-ai-model-governance/?sh=5f85335f15cd
Learn about the differences between prescreen and prequalification and how these tools can help you increase ROI.
Risk management in banking is an approach used by financial institutions to manage risks associated with banking operations. Learn how to do it right.
Customer acquisition in banking: Discover expert strategies, innovative solutions, and insights to grow and retain clients.
View our interactive e-book for the latest economic and consumer trends and learn how to set your portfolio up to succeed in any economic cycle.
Learn three ways to analyze your mortgage portfolio to gain a more complete view of borrowers and maximize performance. Read more!
View our digital lending trends report for a full analysis on origination volume trends, delinquency trends, and consumer behavior insights. Read more!
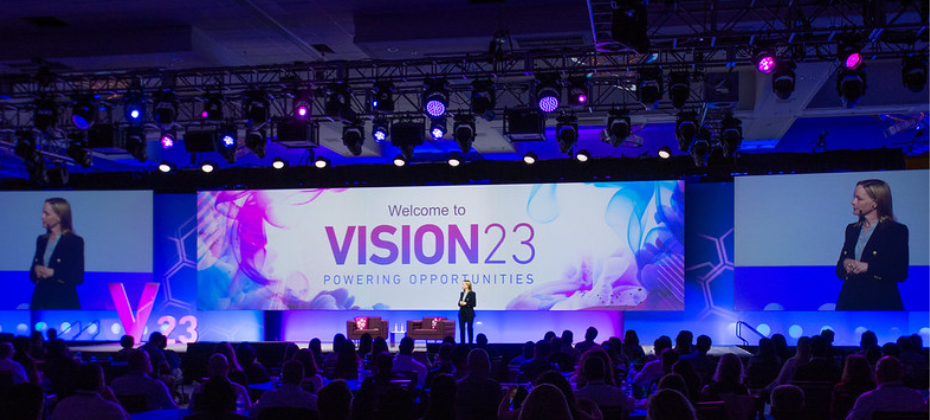
Jennifer Schulz, CEO of Experian, North America kicked off Experian’s annual Vision conference Tuesday morning pointing to data, analytics, technology and collective curiosity as the drivers for change and a more impactful tomorrow to more than 700 attendees. Keynote speaker: Jennifer Bailey Jennifer Bailey, Vice President of Apple Pay and Apple Wallet, spoke about the customer experience “ethos.” She explained how Apple takes a long-term view and values the single most important performance metric as customer experience. She said creating a seamless customer experience comes down to making things simple and understandable, and asking, “Are we solving a customer problem?” and “How are we making it easier for customers to enjoy and liver their lives. Bailey, who said of all apps she uses the weather app the most, also talked about innovation, and that both intent and making mistakes are important parts of the process. Apple’s products are known for their user-friendliness, and design is part of that. She encouraged the audience to give design teams room to create without bottom line pressures and not to be afraid to take well-considered risks. Keynote Speaker: Gary Cohn Gary Cohn, Vice Chairman of IBM, talked about the current economic climate, and while it’s a natural viewpoint to look to the past for guidance, the current environment is unlike any before. Cohn discussed regulatory compliance in the banking industry and prioritizing safety and soundness. While AI is topical and in numerous headlines recently, Cohn reminded the conference goers that AI isn’t new. He said what is new and important is that you can now teach models to find the information needed rather than having to feed all the information yourself. He believes AI is not the end of employment, but rather helps boost productivity, efficiency, and job satisfaction and provides organizations more data. As for advice for the audience, Cohn shared opportunities are in the uncomfortable zones and you have to be willing to fail in order to succeed. Session highlights – Day 1 The conference hall was buzzing with conversations, discussions and thought leadership. Overall themes that were frequently part of the conversation included seamless customer experiences, agility in face of economic changes and leveraging AI/ML into strategies. Fraud automation and preventing commercial fraud More businesses are opening than ever before and lenders and service providers need a way to determine risk from businesses who are less than a year old. There is no one-size-fits-all approach to fraud. A layered solution assesses risk and applies the correct friction to resolve the risk and pass or refer the applicant. Identity Today’s consumer wants a personalized experience and is privacy conscious. Additionally, regulators are also pushing for greater privacy. Clean rooms allow you and a partner to add data to a safe space and learn more about consumers without exposing data. The right data improves acquisition rates, identity verification and allows you to anticipate customer needs. Advanced scoring Data, models and strategy are the levers institutions are using to leverage responsible analytics to meet their objectives like safely growing existing portfolios, managing the “right” level of risk, and providing a seamless digital experience. However, the total value of a decisioning system is almost always constrained by its most rudimentary component. The panel of experts discussed their uses and goals for leveraging models and customer experience was at the top of their priorities. Recession preparedness Delinquency is on the rise and lending offers made continue to drop. Changes in the economic climate require frequent monitoring of portfolio and decisions, benchmarking against peers, updating credit models and decision strategies, and stress testing portfolio and models. Trends in credit risk management While AI at the hands of everyone is topical today, it ranked lowest on the list of trends attendees believed were impacting their business. At the top of the list? The growing demand for simpler, faster and seamless experiences. More insights from Vision to come. Follow @ExperianVision and @ExperianInsights to see more of the action.
Learn how Washington State Employees Credit Union increased their revenue and member satisfaction by implementing a digital prequalification process.
Download the ultimate guide for lenders to debunk popular buy now, pay later myths and how BNPL can benefit consumers and lenders.
With the right technologies and solutions, rental housing operators can manage risk and create better experiences for prospective renters.
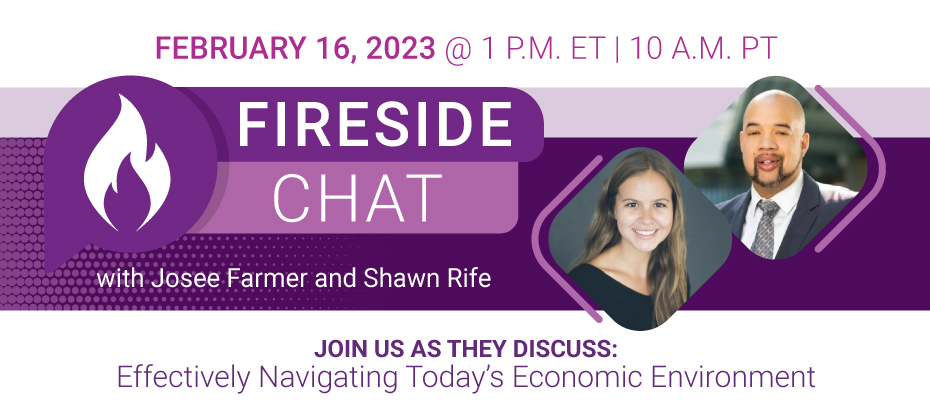
Join our fireside chat as Experian experts explore economic and market trends, their impact on consumers, and how financial institutions can adapt.
Learn how you can grow your portfolio and minimize risk by leveraging industry-leading alternative credit scoring models. Read more!