Credit Unions

The average credit union manages between 100-300 vendor relationships, and nearly a third have no dedicated staff managing them. What was supposed to drive efficiency is stunting growth and compromising the member experience. Application volume is continuing to rise, and consumers expect a loan decision at digital speed. But for credit unions, meeting that expectation isn't the only goal. They must also continue to make the right lending decisions while also prioritizing risk management. The institutions pulling ahead aren't the ones with the most tools. They're the ones that have turned credit, fraud and decisioning into a single, coordinated system. A single loan decision touches: Credit data Identity verification Fraud signals Decisioning logic Reporting Rarely does all of that live in one place. More often, it’s stitched together across separate platforms, each with its own contract and its own support line. When a credit view and a fraud view are generated separately, they must be reconciled instead of read together in the same instant. Every handoff is a place where a decision slows down and a signal gets missed. It's why a fraud pattern that would be obvious next to the credit file often surfaces only after the funds are already gone. Fragmentation also makes it harder to optimize lending strategies over time. When data, analytics and decisioning are disconnected, credit unions have less visibility into what's working, what's changing and where strategies need to be adjusted. An integrated decisioning ecosystem closes those seams by design, with credit, fraud and lending strategy running on one platform and accessed through a single Application Programming Interface (API). Identity and compliance capabilities can be an integrated decisioning flow. The data doesn't need to be reconciled after the fact because it was never separated in the first place. Stop overengineering, start removing friction When decisioning underperforms, the instinct is to build something more custom: a proprietary model, tighter segmentation, more configuration. Custom modeling has its place for institutions with the scale and data to justify it. But often, for small or mid-sized credit unions, the bigger opportunity is a flexible decisioning strategy that uses a strong, continuously refreshed model. This shouldn't be either/or. The right approach gives credit unions a strong decisioning strategy today, with the ability to introduce more customized analytics and modeling as their needs evolve. The same principle applies to strategy management: credit unions can gain greater control through self-service capabilities as they build a more sophisticated data science team. That kind of flexibility is important as credit unions modernize their decisioning infrastructure. Research surveying more than 2,000 senior credit risk and fraud decision-makers across 11 countries found that organizations investing in unified platforms and modern infrastructure are moving faster and realizing the greatest Return on Investment (ROI). As their needs evolve, credit unions can adjust decisioning strategies without introducing another layer of technology or relying on third parties to make every change. Until self-service is the right fit, choose a partner that understands what makes your credit union’s membership and risk appetite different from others. Same member, same afternoon, faster answer Consider a credit union growing its auto and personal loan originations. A member applies for an auto loan on Saturday afternoon. Credit data, identity and fraud signals are read together in a single real-time pass instead of separate reviews: Most applications resolve immediately, approved or declined based on a more comprehensive view of the applicant. A smaller number are flagged for quick step-up verification and cleared within minutes. Only genuinely ambiguous cases reach an underwriter, who is working from one complete picture instead of reconciling multiple signals. The member has an answer before the weekend is over. The credit union books the loan before competitors even open on Monday. Built to scale This kind of process holds up today. However, the better test is whether it holds up eighteen months from now when application volume has grown, new products are live and the data flowing through the system looks nothing like it does right now. Future-proofing isn't only about handling more volume. It's about having room to be nimbler and make adjustments as quickly as the market changes. A credit union that relies on standard models within a decisioning strategy may want more customized analytics and greater control over its strategies tomorrow. Connect with us With more than three decades of credit expertise and one of the industry's largest data footprints, Experian helps credit unions do more than solve this year's friction. We're helping to build a decisioning foundation that scales, so growth becomes something the system absorbs, rather than something it must be rebuilt around. Explore More
Learn how Members First Credit Union uses innovation and data-driven insights to better serve members and expand financial opportunity.
Discover how Union Credit and Experian help credit unions reach younger consumers through personalized digital lending experiences.
We're excited to announce a new digital onboarding portal for community lenders and credit unions to access Experian’s credit reports.
Lending hasn’t slowed down—but many decisioning processes have. Applications are coming in faster. Fraud is becoming more sophisticated. Borrowers expect near-instant responses. And yet, inside many organizations, decisions are still being made across fragmented systems, manual reviews, and rigid strategies that weren’t designed and aren’t optimized for today’s environment. That broadening gap isn’t just an operational issue but often stems from a lack of innovation as well. And it’s quietly costing lenders growth, efficiency, and competitive position. When decisioning falls behind, some symptoms are easy to recognize, like applications taking days to process, teams overloaded with manual reviews, and credit and fraud decisions happening in separate platforms. Others are not as obvious, but arguably more impactful, slipping bottom lines and fraud and therefore losses lurking in lenders’ portfolios. The root issue is a fragmented infrastructure. Experian has reported that while 79% of financial institutions surveyed globally want fewer vendors or more unified approaches, they typically use eight or more tools across credit, fraud and compliance. As most decisioning environments cannot integrate data, adapt strategies, and execute decisions in real time, lenders often have to make tradeoffs. Speed vs. accuracy; growth vs. risk; and automation vs. control are just some. Meanwhile, the market has moved on. Leading lenders are no longer optimizing individual steps. They’re rethinking decisioning as a connected, intelligent system. Gaps forming from status quo in 8 key decision areas Across the lending lifecycle, there are eight critical moments where decisioning can either accelerate growth or create friction. Pre-qualification: Pre-qualification should expand your funnel with confidence. But limited data access and static criteria often result in overly conservative targeting or missed opportunities. Additionally, the delay in acting on a pre-qualification funnel highlights a key area for opportunity among many lenders. Instant credit decisions: Customers expect real-time outcomes. When decisions rely on manual intervention or fragmented inputs, speed and conversions suffer. Prescreen and targeting: Disconnected data and rigid segmentation can lead to poorly aligned offers, reducing response rates and wasting acquisition spend. Credit line management: Without dynamic strategies, credit lines may be too restrictive (limiting growth) or too aggressive (increasing risk). Early delinquency management: Missed early signals and delayed interventions make it harder to prevent accounts from deteriorating. Mid- and late-stage delinquency: Strategies that don’t adapt to evolving borrower behavior reduce recovery effectiveness and increase losses. Collections and recovery: Manual, one-size-fits-all approaches limit recovery rates and increase operational cost. Ongoing strategy optimization: Perhaps the most overlooked gap: many lenders lack the ability to continuously test, learn, and refine decision strategies as conditions change. What these gaps are really costing you Individually, each of these breakdowns may seem manageable. Together, they can create systemic drag on performance. That shows up in four critical ways: Missed growth opportunities: Good borrowers are declined, abandoned, or never targeted in the first place. Credit offers fail to align with actual borrower potential. Higher operational costs: Manual reviews and disconnected workflows consume time and resources that could be spent on higher-value work. Increased fraud exposure and friction: Fraud is proliferating and becoming more expensive to manage. The Federal Trade Commission reported $12.5B were lost to fraud in the U.S. in 2024, a 25% increase over the prior year. For many financial institutions, the first reaction is often to add more steps to the decisioning process, which can impact good borrowers. Increased competitive pressure: Fintechs and modern lenders are focused on delivering faster, more personalized experiences, capturing share while traditional processes lag behind. 80% of banks and credit unions plan to increase their technology spending in 2026, yet many continue to fall short on planned system deployments, according to Cornerstone Advisors’ annual “What’s Going On in Banking” research report. What innovative decisioning leaders are doing differently Leading lenders are changing how decisions are made, creating a competitive advantage. Instead of stitching together point solutions, they’re adopting a more integrated approach that brings together: Comprehensive data – including both credit and fraud insights Optimized decision strategies – designed to balance growth and risk Real-time execution – enabling faster, more consistent outcomes Continuous optimization – adapting to changing market conditions Strategic partnerships – leveraging third-party industry expertise to augment their own This shift eliminates the need for tradeoffs and instead allows lenders to increase approvals while maintaining control, reducing manual effort while improving consistency, and responding faster without sacrificing confidence. The stakes are high and the competition for consumers is even higher, particularly against a backdrop of ever-evolving fraud risks, continuously increasing consumer expectations for seamless, digital-first experiences and often limited resources. Nearly half of banks and 59% of credit unions have already deployed generative AI, with more investing now, according to the Cornerstone Advisors’ report. Closing the innovation gap requires a more fundamental shift toward decisioning systems that are connected, scalable, and built for continuous change. A new foundation for decisioning This is where platforms like Experian Decisioning are changing the landscape. By bringing together credit and fraud insights, decision strategies, and a flexible technology architecture, lenders can move beyond fragmented processes and build a more unified, intelligent decisioning approach. One that fits within existing systems but also evolves with your needs. Where to start Impactful change doesn’t need to be an overhaul of everything at once for most organizations. The first step is understanding where your biggest gaps exist, and which decision areas are creating the most friction or missed opportunity. Once you can see where decisioning is not optimized, you can begin to redesign it in a way that’s faster and more adept for what lending has become. By making better decisions, faster, and with greater confidence, lenders can process applications more efficiently and also break away from the pack by leveraging decisioning as a strategic advantage. Learn more
Discover key insights into the consumer credit landscape and how credit unions stack up against other financial institutions.
Banks attract new deposits by offering competitive demand deposit accounts with digital banking and personalized financial solutions.
Discover how data and analytics can enhance deposit growth strategies, improve customer engagement, and drive financial wellness for banks and credit unions.
Here’s a step-by-step guide on how to create an effective credit union collection strategy. Read on to learn more.
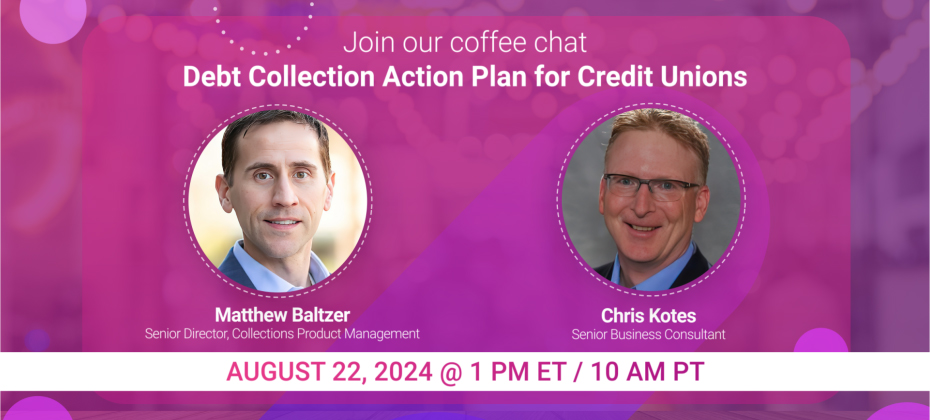
Grab a cup of coffee and join our experts for a conversation on credit union collection trends and successful account management strategies.
With the advent of AI and ML, optimizing credit prescreen campaigns has never been easier or more efficient.
Learn about the benefits of a fraud consortium and how Experian's solutions can help prevent fraud without inconveniencing consumers.
Using alternative data for credit underwriting is a modern and efficent approach to a risk-based credit approval strategy Read more!
Credit unions are working toward financial inclusion, but it's a process that requires establishing best practices, partnerships and engaging leadership.
With Experian’s Prospect Triggers, this credit union was able to pinpoint consumers that met their credit criteria & were likely to respond to their offers.