With Hispanic Heritage Awareness Month underway and strategic planning season in full swing, the topic of growing membership continues to take front stage for credit unions.
Miriam De Dios Woodward (CEO of Coopera Consulting) is an expert on the Hispanic opportunity, working with credit unions to help them grow by expanding the communities they serve.
I asked Miriam if she could provide her considerations for credit unions looking to further differentiate their offerings and service levels in 2019 and beyond.
There’s never been a better time for credit unions to start (or grow) Hispanic engagement as a differentiation strategy. Lending deeper to this community is one key way to do just that. Financial institutions that don’t will find it increasingly difficult to grow their membership, deposits and loan balances.
As you begin your 2019 strategic planning discussions, consider how your credit union could make serving the Hispanic market a differentiation strategy. Below are nine ways to start.
1. Understand your current membership and market through segmentation and analytics.
The first step in reaching Hispanics in your community is understanding who they are and what they need. Segment your existing membership and market to determine how many are Hispanic, as well as their language preferences. Use this segmentation to set a baseline for growth of your Hispanic growth strategy, measure ongoing progress and develop new marketing and product strategies. If you don’t have the bandwidth and resources to conduct this segmentation in-house, seek partners to help.
2. Determine the product gaps that exist and where you can deepen relationships.
After you understand your current Hispanic membership and market, you will want to identify opportunities to improve the member experience, including your lending program.
For example, if you notice Hispanics are not obtaining mortgages at the same rate as non-Hispanics, look at ways to bridge the gaps and address the root causes (i.e., more first-time homebuyer education and more collaboration with culturally relevant providers across the homebuying experience). Also, consider how you might adapt personal loans to meet the needs of consumers, such as paying for immigration expenses or emergencies with family in Latin America.
3. Explore alternative credit scoring models.
Many credit products accessible to underserved consumers feature one-size-fits-all rates and fees, which means they aren’t priced according to risk. Just because a consumer is unscoreable by most traditional credit scoring models doesn’t mean he or she won’t be able to pay back a loan or does not have a payment history. Several alternative models available today can help lenders better evaluate a consumer’s ability to repay. Alternative sources of consumer data, such as utility records, cell phone payments, medical payments, insurance payments, remittance receipts, direct deposit histories and more, can be used to build better risk models.
Armed with this information – and with the proper programs in place to ensure compliance with regulatory requirements and privacy laws – credit unions can continue making responsible lending decisions and grow their portfolio while better serving the underserved.
4. Consider how you can help more Hispanic members realize their desire to become homeowners.
In 2017, more than 167,000Hispanics purchased a first home, taking the total number of Hispanic homeowners to nearly 7.5 million (46.2 percent of Hispanic households). Hispanics are the only demographic to have increased their rate of homeownership for the last three consecutive years.
What’s more, 9 percent of Hispanics are planning to buy a house in the next 12 months, compared to 6 percent of non-Hispanics. This means Hispanics, who represent about 18 percent of the U.S. population, may represent 22 percent of all new home buyers in the next year. By offering a variety of home loan options supported by culturally relevant education, credit unions can help more Hispanics realize the dream of homeownership.
5. Go beyond indirect lending for auto loans.
The number of cars purchased by Hispanics in the U.S. is projected to double in the period between 2010 and 2020. It’s estimated that new car sales to Hispanics will grow by 8 percent over the next five years, compared to a 2 percent decline among the total market.
Consider connecting with local car dealers that serve the Hispanic market. Build a pre-car buying relationship with members rather than waiting until after they’ve made their decision. Connect with them after they’ve made the purchase, as well.
6. Consider how you can help Hispanic entrepreneurs and small business owners.
Hispanics are nine times more likely than whites to take out a small business loan in the next five years. Invest in products and resources to help Hispanic entrepreneurs, such as small business-friendly loans, microloans, Individual Taxpayer Identification Number (ITIN) loans, credit-building loans and small-business financial education. Also, consider partnering with organizations that offer small business assistance, such as local Hispanic chambers of commerce and small business incubators.
7. Rethink your credit card offerings.
Credit card spending among underserved consumers has grown rapidly for several consecutive years. The Center for Financial Services Innovation (CFSI) estimates underserved consumers will spend $37.6 billion on retail credit cards, $8.3 billion on subprime credit cards and $0.4 billion on secured credit cards in 2018.
Consider mapping out a strategy to evolve your credit card offerings in a way most likely to benefit the unique underserved populations in your market. Finding success with a credit-builder product like a secured card isn’t a quick fix. Issuers must take the necessary steps to comply with several regulations, including Ability to Repay rules.
Cards and marketing teams will need to collaborate closely to execute sales, communication and, importantly, cardmember education plans. There must also be a good program in place for graduating cardmembers into appropriate products as their improving credit profiles warrant. If offering rewards-based products, ensure the rewards include culturally relevant offerings. Work with your credit card providers.
8. Don’t forget about lines of credit.
Traditional credit lines are often overlooked as product offerings for Hispanic consumers. These products can provide flexible funding opportunities for a variety of uses such as making home improvements, helping family abroad with emergencies, preparing families for kids entering college and other expenses. Members who are homeowners and have equity in their homes have a potential untapped source to borrow cash.
9. Get innovative.
Hispanic consumers are twice as likely to research financial products and services using mobile apps. Many fintech companies have developed apps to help Hispanics meet immediate financial needs, such as paying off debt and saving for short-term goals. Others encourage long-term financial planning. Still other startups have developed new plans that are basically mini-loans shoppers can take out for specific purchases when checking out at stores and online sites that participate. Consider how your credit union might partner with innovative fintech companies like these to offer relevant, digital financial services to Hispanics in your community.
Next Steps
Although there’s more to a robust Hispanic outreach program than we can fit in one article, credit unions that bring the nine topics highlighted above to their 2019 strategic planning sessions will be in an outstanding position to differentiate themselves through Hispanic engagement.
Experian is proud to be the only credit bureau with a team 100% dedicated to the Credit Union movement and sharing industry best practices from experts like Miriam De Dios Woodward.
Our continued focus is providing solutions that enable credit unions to continue to grow, protect and serve their field of membership. We can provide a more complete view of members and potential members credit behavior with alternative credit data. By pulling in new data sources that include alternative financing, utility and rental payments, Experian provides credit unions a more holistic picture, helping to improve credit access and decisioning for millions of consumers who may otherwise be overlooked.
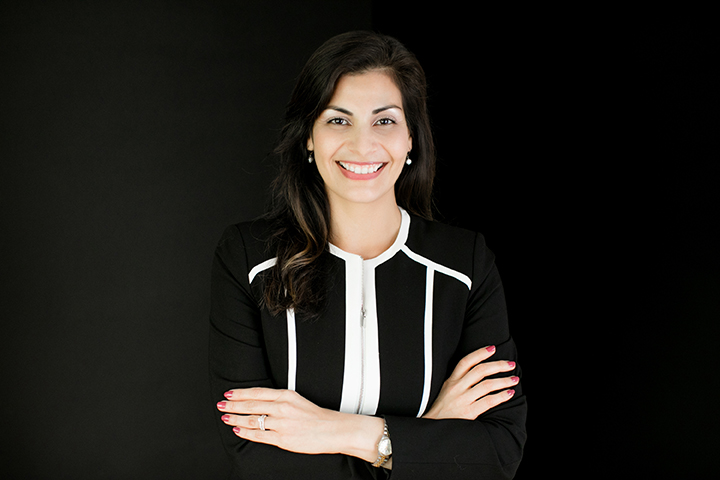 About Miriam De Dios Woodward
Miriam De Dios Woodward is the CEO of Coopera, a strategy consulting firm that helps credit unions and other organizations reach and serve the Hispanic market as an opportunity for growth and financial inclusion. She was named a 2016 Woman to Watch by Credit Union Times and 2015 Latino Business Person of the Year by the League of United Latin American Citizens of Iowa.
Miriam earned her bachelor’s degree from Iowa State University, her MBA from the University of Iowa and is a graduate of Harvard Business School’s Leading Change and Organizational Renewal executive program.