Electronic Signatures and layered authentication

by Guest Contributor 4 min read December 7, 2015

Electronic signatures and their emerging presence in our Internet-connected world
esralogoI had the opportunity to represent Experian at the eSignRecords 2015 conference in New York City last week. The concept of electronic signature, while not new, certainly has an emerging presence in the Internet-connected world — as evidenced by the various attendee companies that were represented, everything from home mortgages to automobiles.

Much of the discussion focused on the legal aspects of accepting an electronic signature in lieu of an in-person physical signature. The implications of accepting this virtual stamp of approval were discussed, as well as the various cases that already have been tried in court. Of course, the outcome of those cases shapes the future of how to properly integrate this new form of authorization into existing business processes.

Attendees discussed the basic concept of simply accepting a signature on an electronic pad as opposed to one written on a piece of paper. That act alone has many legal challenges even though it provides the luxury of in-person authentication through a face-to-face meeting.

The complexities and risk increase exponentially when these services are extended over the Internet. The ability to sign documents virtually opens up a whole new world of business opportunities, and the concept certainly caters to the consumer’s need for convenience. However, the anonymity of the Internet presents the everyday challenge of balancing consumer expectations of greater ease of use with necessary fraud prevention measures. Ultimately, it always comes back to understanding who is actually signing that document.

All of this highlights the need for robust authentication and security measures. As more and more legal documents and contracts are passed around virtually, the opportunity to properly screen and verify who has access to the documents gets more critical.

Many organizations still rely on the tried-and-true method of knowledge-based authentication (KBA), while many others have called for its end. KBA continues to soldier on as an effective way to ensure that people on the other end of the wire are who they say they are by asking questions that — presumably — only they know the answers to.

In most cases, KBA is viewed as a “check the box” step in the process to satisfy the lawyers. In certain cases, that’s all you need to do to ensure compliance with legal policy or regulatory requirements.

It starts to get tricky is when there’s more on the line than just “check the box” actions. When the liability of first- or third-party fraud, becomes greater than simple compliance, it’s time to implement tighter security, while at the same time limiting the amount of friction caused by the process.

Many in attendance discussed the need for layers of authentication based on the type of documents that are being processed and handled. This speaks directly to the point that one size does not fit all.

As the industry matures and acceptance of e-signatures increases, so too does the need for more robust, flexible options in authentication.

Another topic — that was quite frankly foreign to everyone we talked to — was the need for security around the concept of account takeover. When discussing this type of fraud, most attendees did not even consider this to be a hole in their strategy.

Consider this fictional scenario. I’m responsible for mergers and acquisitions for my publicly traded company. I often share confidential information via electronic means, leveraging one of the many electronic signature solutions on the market. I become a victim of a phishing attack and unknowingly provide my login credentials to the fraudster. The fraudster now has access to every electronic document that I have shared with various organizations — most of which have been targets for mergers and acquisitions.

Fraudsters are creative. They exploit new technologies — not because they’re trendsetters, but because oftentimes these new technologies fail to consider how fraudsters can benefit from the system.

If you are considering adopting e-signature as a formal process, please consider implementing:

If you haven’t considered implementing e-signature technology into your business process, you should — but be sure to have your fraud team present when considering the implementation.
Related Posts

New Data Available for MBS Investors: Current Credit Score 

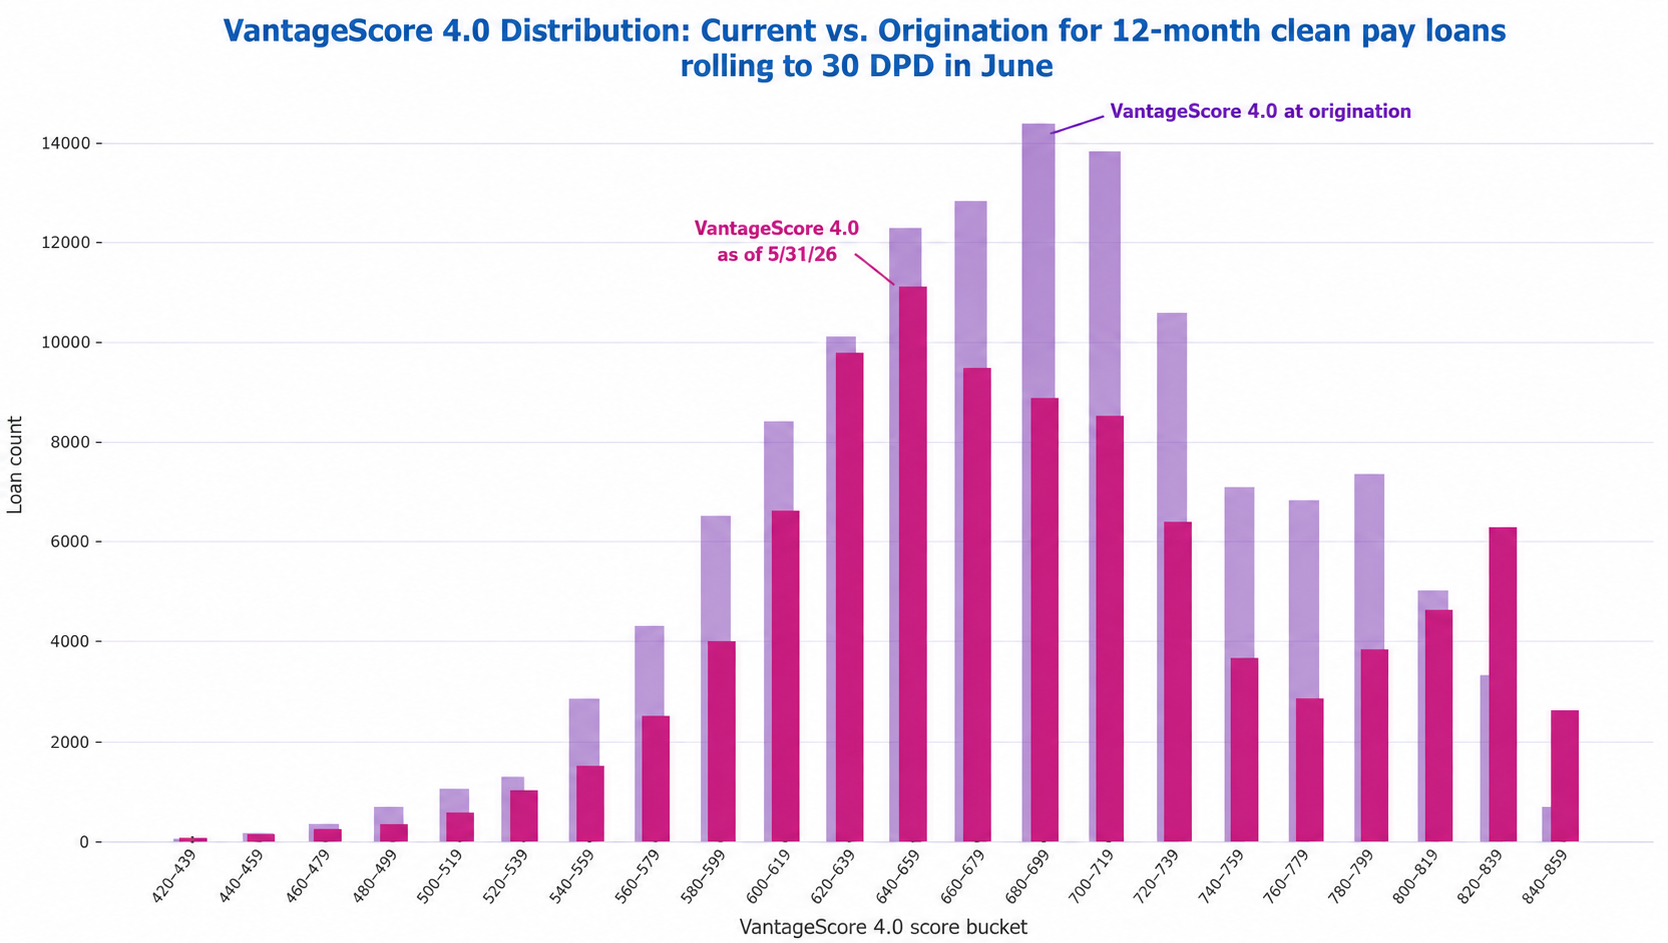
In a previous post, we described how every mortgage borrower’s financial situation and credit profile evolve over time.  After a borrower opens a loan, their financial status evolves—jobs are gained and lost; incomes can rise or fall, and financially stressful situations or windfalls can occur. These effects are often reflected in the consumer’s evolving credit score, which changes with the consumer’s payment behavior on open loans, credit inquiry activity, credit card utilization, and other revolving lines, among other things.    Even though MBS, whole loan, and MSR investors ultimately bear borrower credit risk, they may have access to less current borrower credit information than other participants in the mortgage ecosystem.   In securitized markets (both agency MBS and private-label MBS), updated scores are not provided in disclosure to bondholders, even as loans age year over year.  In whole loan and MSR markets, a single origination credit score is often provided at the time of bid, and after a successful bid, the investor may have a permissible purpose to pull individual scores on an owned portfolio. But until recently, there was no single loan-level dataset that included continuously refreshed credit scores across the U.S. mortgage market—the type of foundational dataset needed to build and tune credit and prepayment models.  A monthly-refreshed Current Credit Score field meets our three-pronged materiality standard for new data delivery to MBS markets:  New: Provides information not available in existing datasets (i.e., orthogonal to currently available data). Neither private-label MBS nor agency MBS standard market data includes a monthly-refreshed borrower credit score.  Material: Impacts a sizeable portion of the MBS universe. For the vast majority of loans in MBS, borrowers credit scores are available.  Significant: Differentiates collateral performance by a large enough margin to influence trading and risk management decisions.  A current credit score wraps all of a borrower’s credit-related behaviors into a single numerical value and has historically been associated with a borrower’s likelihood of becoming 60+ days past due on any obligation within the subsequent 24 months.    In fact, a current credit score is among the most informative indicators of near-term mortgage default risk, as shown in the image below, which depicts 30+ DPD rates by current credit score bands for the entire U.S. mortgage market, controlling for origination score <=650.    Without access to current credit scores, investors are limited to the score at origination—causing the four distinct performance trends shown here to appear as a single averaged line. In reality, score migration since origination reveals significant divergence in credit risk, with the lowest current-score bucket exhibiting a nearly 10 times higher 30+ DPD rate than the highest-score bucket in the latest period shown.  Source:  Experian Mortgage Loan Performance (MLP) dataset hosted on IVolatility DataDriven Platform  In this article, we’ll take a quick look at how score migration acts as an early predictor of a performing loan’s first roll into 30-day delinquent status.    MBS Investors’ Current Credit Score Blindspot: Solved   An MBS investor relying on standard market data and securitization remittance reports sees no sign of borrower stress until the subject mortgage loan in the securitization misses a payment and is reported at 30 days delinquent. Of course, in the vast majority of cases, a borrower begins struggling financially well before missing a mortgage payment:  The borrower may miss payments on other types of loans (credit card, auto loan, personal unsecured, or payday loans) as they prioritize their home and mortgage.  Outstanding balances on credit cards may grow as the borrower begins to make only minimum payments on revolvers.  The borrower may apply for additional credit cards, personal or payday loans   The borrower may apply to increase limits on existing credit cards as outstanding balance nears spending limit  All these stress-indicative behaviors result in a decreasing credit score, many months before the borrower misses their first mortgage payment. An MBS investor with access to each borrower’s current credit score, refreshed each month, can predict increased likelihood of default many months before the first missed mortgage payment—and is therefore at a major information advantage relative to the market generally.  Experian’s Mortgage Loan Performance (MLP) dataset contains thousands of fields describing mortgage performance from each borrower, loan, and property perspective, all refreshed monthly (including, amongst other things, new credit scores and refinance inquiry activity, loan performance on all types of debt, filed junior liens, and AVM values).   MLP is much more comprehensive than loan-level data provided by Freddie Mac, Fannie Mae, Ginnie Mae, and PLS data vendors in several ways:   Standard market datasets may not contain certain data elements that some market participants consider useful when evaluating mortgage prepayment or credit performance. Basic, critical fields such as the borrower’s current credit score and the current junior lien balance on the property are missing.    MLP contains borrower, loan, and property data fields spanning a broad portion of the mortgage universe, including Agency, Non-Agency, and Esoteric mortgage products (CES, HELOC, Reverse), including both securitized and non-securitized loans.   MLP enables full three-dimensional (borrower + loan + property) tracking with persistent keys for borrower (before and after refinancing), loan (in securities/deals even after exit due to payoffs or buyouts, including before and after MSR sales), and property.  This enables end-to-end analysis of each borrower’s (and property’s) mortgage experience throughout their credit lifecycle.  Is Downward-Trending Credit Score a Signal for Impending Delinquency?  MLP contains thousands of fields describing each loan, borrower, and property across all U.S. mortgages.  It allows for virtually unlimited segmentation and granular analysis.   For purposes of this illustrative article, we’ll take a high-level look at the entire U.S. mortgage market and perform a quick analysis to confirm intuition that a declining credit score provides a signal for higher likelihood of near-term mortgage delinquency.  Figure 1 illustrates the current pay status (as of 6/30) for the entire U.S. mortgage market, as contained in the MLP dataset, along with count, UPB and UPB-weighted Vantage 4.0 credit score for each bucket.  Figure 1  Source:  Experian Mortgage Loan Performance dataset  As illustrated in Figure 1, approximately 772,000 individual mortgage loans were reported to Experian as 30 days delinquent as of 6/30/2026.  Of the 772,000 30d delinquent loans in the June snapshot, approximately 426,000 were current in the prior (May) snapshot.  Some of these 426,000 loans were reperformers which had been bouncing from 30 DPD to current over the prior few snapshots. To remove reperformance score noise, we further parsed out the population which: 1) had rolled from current to 30 DPD from May to June; and 2) was consistently current for a full year prior to the 6/30 missed payment.  The population meeting both conditions totaled approximately 123,000 loans.  Figure 2 below shows, for this population of 123,000 “clean current” loans, the UPB-weighted average Vantage4 credit score for each of the 12 months leading up to the June missed payment, as well as the impact of the missed payment on the 6/30 score.  Figure 2  Source:  Experian Mortgage Loan Performance Dataset  Figure 2 reveals a rather slow and steady ~20-point deterioration of score in the 12 months prior to first missed payment – as well as the 80-point drop once the missed payment hits.  When we compare this cohort’s Vantage 4.0 score trend to the broader Current population across the entire dataset in Figure 3, we see a marked difference in both absolute value and trend:  Figure 3  Source:  Experian Mortgage Loan Performance Dataset  Not only is the cohort’s starting Vantage 4.0 score lower than the broader current population, but it also displays a dropping trend (with a notable 2 to 3x acceleration in monthly score drop the month before the first missed mortgage payment) while the broader Current population’s score (of which the isolated cohort is a subset) remains rock steady.  Lastly, we present Figure 4, a histogram comparing the distribution of at-origination and as-of 5/30 (i.e., the period just before the missed June mortgage payment) credit scores for the clean current population. The distribution appears to shift toward lower credit scores. To the extent credit scores are correlated with credit risk, this shift may indicate elevated credit risk relative to origination. Since this degradation occurs during a period of perfect mortgage pay performance, it is invisible to MBS investors who lack access to current borrower credit scores. Experian MLP provides monthly refreshed credit scores for mortgage borrowers contained within the MLP database.  Figure 4  Source:  Experian Mortgage Loan Performance Dataset 

September 22, 2026 by Michael Pyatski, Perry DeFelice
Ask the Expert: The Future of Lending Starts With Identity With Shawn Rife and Brian Cardona

Identity intelligence and alternative data can help lenders validate consumers and support more informed decisions across the customer lifecycle.

September 16, 2026 by Julie Lee
Financial Institutions Are Rethinking Customer Acqusition

Customer acquisition strategies are constantly evolving toward more precise targeting. From a marketing lens, you can track every step, optimize communication channels and still miss the person most likely to convert. Attribution can tell us which channels work and automation can make marketing spend more efficient. But both assume we know who is actually on the other end. Financial institutions are learning that finding audiences and targeting them is no longer the biggest challenge. As acquisition optimization marketing becomes more sophisticated, teams can measure and act on more signals than before. What they can't always know is whether the person on the receiving end is real. Customer acquisition has evolved into an identity problem. The challenge is not that every questionable signal represents malicious activity. It's that acquisition systems must make increasingly intelligent decisions with an imperfect understanding of who they're actually engaging. When identities are fragmented, duplicated, temporary or synthetic, optimization becomes a question of trust as much as targeting. When your signals don't reliably identify customers The customer journey often includes searching, filling out a form, creating an account, requesting a quote and subscribing. All of these signals work well when identity is relatively stable.  However, financial institutions are finding that these signals are becoming less reliable. A single person can operate across multiple personas, devices, browsers, aliases, accounts and intermediaries while several apparent “people” may actually represent one underlying actor. Financial instituions are finding: Fragmented customer signals Difficulty distinguishing an old account from a new one Different digital pathways associated with the same individual Signals that are generated by automation Real customers getting flagged because signals are too thin to evaluate confidently Legacy signals continue to be challenged Marketing has historically treated intent as a valuable signal because intent was relatively difficult to produce. A search required human intent. A form required someone to fill it out. An inquiry implied a meaningful amount of human effort. Financial institutions are already combating AI-enabled fraud, and now marketing teams are starting to face it on a massive scale. AI can mimic human behavior by researching products, comparing prices, filling out forms, creating accounts and signing up for services. A valid email address is no longer enough. Marketers need to know: How long has it existed? How recently has it been active? Does its activity appear consistent or suddenly anomalous? Has it gone dormant and returned? Is it associated with patterns that suggest stability or unusual behavior? How to build on your strongest signal Email remains one of the most persistent identifiers in digital commerce, following people across devices, platforms, transactions, subscriptions, accounts and years of activity. For over two decades, this has shaped how AtData thinks about identity. Now, as part of Experian, it’s shaping how an entire platform and team approach identity. A marketer doesn’t need every prospect to have existed online for twenty years. But understanding whether a newly acquired prospect has meaningful identity context can dramatically improve the quality of the decision being made around it. Better identity intelligence can help organizations reduce unnecessary friction by improving their ability to recognize legitimate customers. With a strong identity foundation, marketing teams can better address: Which audiences are more likely to convert? Which leads are high quality? Which channels are driving incremental growth? What do the best prospects look like? The value isn't simply having an email address. It's understanding the history and behavioral context associated with it. That context can provide a stronger digital identity signal, helping marketers understand how long they have been active, whether its behavior is consistent with that of a real person and whether current activity aligns with past patterns. It continues to be one of the most persistent identifiers in digital commerce. An infrastructure built for what's coming The acquisition of AtData by Experian reflects a fundamental shift in how identity infrastructure needs to work. Experian's scale and decisioning capabilities, combined with AtData's real-time email intelligence, create a strong platform. Read more about the why behind the acquisition and see how email works as an identity anchor for fraud prevention. Contact us to learn about our customer acquisition solutions

September 15, 2026 by Zohreen Ismail

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe