Does your risk model stand up against the test of time?

by Guest Contributor 1 min read March 6, 2014

Using a risk model based on older data can result in reduced predictive power. As consumer credit behaviors evolve, the predictive contribution of specific factors changes. For example, in recently developed models, payment history is 25 percent more relevant in terms of predictive contribution than in prerecession models. The following chart details the changes in key contributing factors over time.
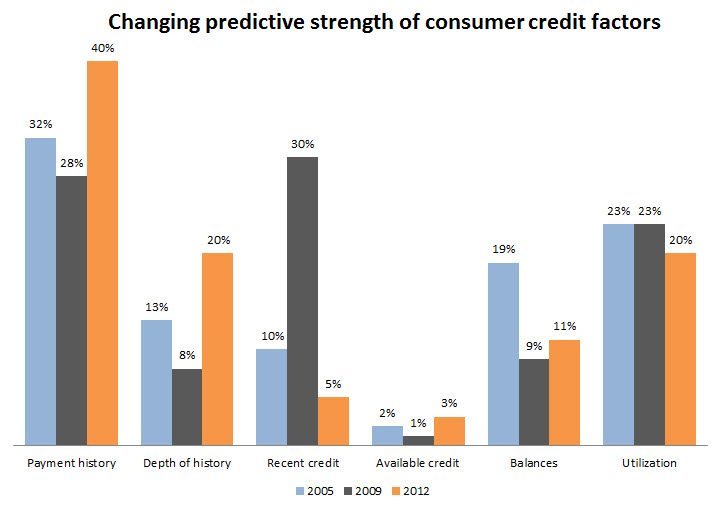
**Please click image to enlarge

Risk managers can stay ahead of these changes by regularly validating their risk models and by using scoring models developed on the latest consumer data available.

View the webcast: Implementing a new scoring model: Plug & Play

The Score, February 2014

VantageScore® is a registered trademark of VantageScore Solutions, LLC.
Related Posts

How Rental Data Is Expanding Financial Opportunity for Millions of Renters 

Discover how rental payment reporting can expand credit access, strengthen credit profiles and improve risk assessment for renters and housing providers.

October 8, 2026 by Manjit Sohal
From Innovation to Impact: Meet the 2026 Experian Vision Awards Winners

Four organizations show what’s possible when data, analytics, AI and technology are put to work against real business and consumer challenges.

October 8, 2026 by Stefani Wendel
Vision 2026: Day Two Recap 

From thought-provoking conversations on AI and the future of financial services, day two of Vision brought bold ideas and insights. 

October 7, 2026 by Sharis Rostamian

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe