Financial Services
Learn how you can use credit attributes to identify qualified prospects, set initial limits, manage credit lines and limit credit losses.
As card issuers go head-to-head in the battle to reach and connect with new consumers, they must implement more inclusive lending strategies.
Cryptocurrency scams are on the rise as digital currencies gain popularity. The decentralized nature of these currencies makes them equally attractive to both legitimate consumers and fraudsters. Businesses may find themselves in a difficult position as they seek to prevent cryptocurrency-related fraud and help protect consumers. What are cryptocurrency scams? Cryptocurrencies are virtual currencies often based on and secured by blockchain technology. However, this does not always translate into security for the individual consumer. Many individuals fall victim to either cryptocurrency investment scams or cryptocurrency theft. Cryptocurrencies are not yet well-regulated or backed by a sovereign entity, leaving consumers open to threats when purchasing funds. The deregulated nature of the currencies makes it easy for scammers to build what appear to be legitimate cryptocurrency projects before disappearing, similar to pump-and-dump stock schemes. Additionally, scammers will perpetrate romance or other relationship-based scams and convince the victim to send them funds in cryptocurrency form. Cryptocurrency theft follows a few traditional fraud patterns: The fraudster may use phishing or social engineering to steal credentials. A crime ring might leverage malware or keystroke loggers to do the same thing. A scammer might present a “reward” to an unsuspecting consumer and require access to their wallet in order to “gift” the reward. Scammers consistently find new ways to trick unsuspecting consumers, including a recent scam relying on QR codes to steal funds converted to cryptocurrency via an ATM. Other common scams utilize imposter websites, fake mobile apps, bad tweets, or scamming emails to steal information and funds. The impact of scams on consumers According to the FTC, investment cryptocurrency scam reports have skyrocketed, with nearly 7,000 people reporting losses totaling more than $80 million from October 2020 to March 2021, with a media loss of $1,900. In 2020 the Better Business Bureau Scam Tracker Risk Report ranked cryptocurrency scams as the seventh riskiest. In 2021, they jumped to the second riskiest scam. In Michigan alone 31 cryptocurrency scams were reported from January 2020 to March 2022, with reported loses from $350 all the way to $41,000. The impact of scams on businesses While the true impact of cryptocurrency scams on businesses is hard to measure, it’s easy to identify several areas for concern. First is the opportunity for the theft of personally identifiable information (PII) during a fraudulent cryptocurrency transaction. Once fraudsters have stolen funds, they may also funnel them through a legitimate business and turn them into a regulated form of currency for easy of use. Businesses with legitimate cryptocurrency interactions may also suffer from spoofed apps or websites, causing reputational damage when consumers are taken in by a scam. Preventing the fallout from scams As companies debate accepting cryptocurrency as a form of payment, it’s important to consider that funds may be stolen or accessed by a malicious party. One way to protect your organization is to have a strong device identification strategy that can help ensure the entity accessing an account and the funds within is the true owner. By layering in this protection with other fraud defenses, businesses can be better prepared as consumer payment preferences shift. Additionally, financial institutions and other organizations should keep consumers informed about how to protect their own data and signs of scams. To learn more about how Experian is helping businesses develop and maintain effective fraud and identity solutions, visit us or request a call. And keep an eye out for additional in-depth explorations of our Future of Fraud Forecast. Request a call Future of Fraud Forecast
Experian recently announced Experian Identity and published an advertorial in American Banker outlining the integrated approach to identity that recognizes the full breadth of the company’s authoritative data solutions that help businesses better connect with their consumers in more personalized, meaningful and secure ways. The efforts address the rapidly changing definition and landscape of identity and take on the importance and needs for identity which span across the entire customer journey. From marketing to a specific consumer’s needs, to facilitating a friction-right customer experience, to protecting personal information. As such, there’s a gap for single-partner providers to help businesses navigate this change, while also putting the needs of the consumer first. “Identity data sets are constantly growing with inputs from new interactions. Many future sources of data have yet to be even conceived or developed,” said Kathleen Peters, Chief Innovation Officer, Experian Decision Analytics. “Staying ahead of the identity market curve is vital, and it requires building and continually evolving an enterprise-scale identity solution that interconnects with your own unique data and systems to create attribute-rich profiles of your customers that work across any identity application. That’s Experian Identity.” Experian Identity underscores the need businesses have to respond to increasing identity needs with interconnected, scalable technology, products and services that optimize the consumer experience. While the integrated approach announcement is new, the capability is not. Experian has been trusted for decades to secure individuals’ identity around the most important decisions in their lives – think purchasing a car or home, being identified at the doctor’s office, and more. As such, consumers remain at the center of every action. Experian Identity offers identity resolution, verification, authentication and protection, and fraud management solutions that include first- and third-party fraud, account takeover, credit card verification, identity resolution and restoration, risk-based authentication, synthetic identity protection and more. Additionally, we’ve included a special blog post introducing Experian’s identity capabilities from Kathleen Peters on the Experian Global News Blog and additional coverage. Stay tuned for more updates. Experian Global News Blog - Making Identities Personal: Experian Helps Businesses Build Consumer Trust American Banker – Making Identities Personal: Building Trust and Differentiating Your Brand Experian White Paper - Making Identities Personal For more information about Experian Identity, visit www.experian.com/identity-solutions.
Experian’s latest Global Insights Report found that more than half of consumers have increased their online spending in the last three months, and 50% say it will increase in the next three months. Life online is here to stay, and consumer expectations have shifted, giving businesses and opportunity to sink or swim when building trust and gaining loyalty. This spring, Experian surveyed 6,000 consumers and 2,000 businesses across all industries to learn more about how, why, and where consumers are interacting with businesses online. Our research found that: Experience is top of mind, with 81% of consumers saying that a positive online experience makes them think more highly of a brand Digital payment options are on the rise with 62% of consumers using mobile wallets and 57% considering buy now, pay later as a replacement for their credit card Security is still a big factor, but 73% of consumers say the onus is on businesses to protect them online Download the report to get all the latest insights into consumer sentiment and how recent changes are impacting business priorities and investments. Download the report
When extending firm offers of credit, lenders have relied on direct mail to reach their intended audiences. But what if there are more ways to deliver a credit offer?
What goals should you set to make financial inclusion a reality? How can success be quantified? This checklist can help you become more inclusive.
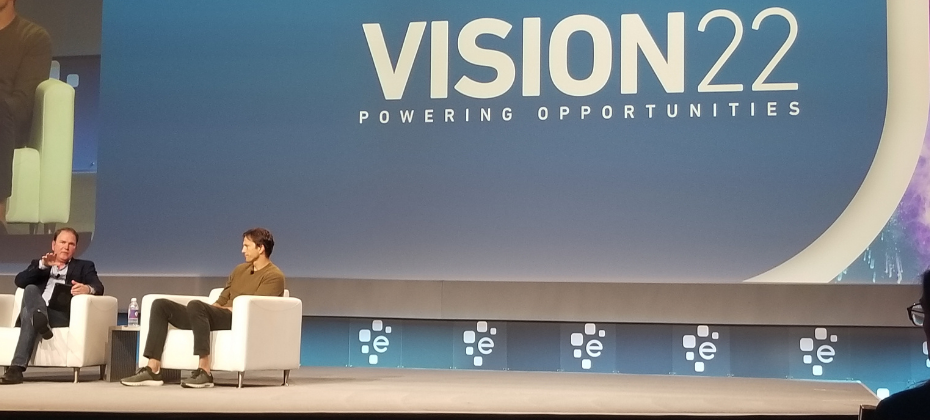
“I saw an opportunity to create change instead of asking for it.” Day 2 was charged up with new technology; new ideas; and new, clearer visions of where we can drive change across our industries. Jeff Softley, President, Direct to Consumer, Experian Consumer Services, illustrated how the consumer is at the center of Experian’s business with countless statistics and how our consumer advocacy drives our focus, growth and mission. Wil Lewis, Global Chief of Diversity, Equity and Inclusion; Hiq Lee, President of Business Information Services; and Alex Lintner, Group President, Consumer Information Services, engaged in a panel discussion centered on reimagining inclusion. Keynote: Allyson Felix Allyson Felix, five-time Olympian and most decorated Track & Field athlete, kicked off the day with an inspiring keynote touching on her athletic career, taking challenges head-on and using our platforms to make an impact. Felix, who is racing in the first race of her final season this weekend, is a tireless advocate, life-long learner, who seeks to empower others. “We can all start where we are,” she said. “Small things turn into big things.” Day 2 session highlights From the breakout sessions, the theme of disruption was evident. We dove into how prescreen and prequalification have evolved, a demand that many must adapt to deliver in the post-pandemic world. Financial inclusion was a topic covered across the board, as were the strategies to be enacted to bolster these financial inclusion drivers. One such area addressed was how the rapidly growing buy now, pay later industry advances financial access and inclusion efforts. And speaking of evolution, retention must evolve as well — we heard how retention, recapture and risk strategies are transforming, particularly in the mortgage servicing space. Rapid Model Development and Deployment - Feedback from businesses reflects organizations’ desires for flexible deployment options, flexible integration with existing tech stacks, open source technology and the ability to incorporate multiple data providers. Today’s solutions address that feedback as well as solve for the most rampant market challenges in new, innovative ways. Strategy optimization with Artificial Intelligence and Machine Learning - Over 50% of financial institutions surveyed are using AI/ML in at least one department. Challenges include data management, operation, evolving the analytics program. ML/AI starts with proper data management. For optimization, templatizing ML frameworks is a necessity. ID Verification, Authentication and Fraud - There were $56B in identity fraud losses in 2020, $13B of which were traditional identity fraud losses and $43B related to identity fraud scams. Leveraging strategies is necessary to maintain the critical balance required for identity verification and fraud – mitigating losses and risk exposure, drive optimal customer experience, maintain regulatory compliance. Maximizing Customer Value - The monthly data refresh is a thing of the past. When reimagining account review for risk and marketing purposes, remaining agile is key with increased data freshness for operational efficiency. Keynote: Ashton Kutcher The energy, insights and ideas have been reverberating throughout the venue for the past 48 hours, which set the stage for Ashton Kutcher’s closing keynote. The Chicago Bears fan talked about his career, how hard work wasn’t an option when he was growing up and how part of his assessment process for potential investments – determining whether they create efficiencies in the market – he sometimes thinks of a long-standing, personal benchmark – the air nailer. He talked about his philanthropy efforts, the mission behind his company Thorn, and the ability for people to impact change and achieve "a sense of agency" over the outcome of the future. “That’s the human spirit. That’s the spark that exists – that people understand that you can sit in despair, or you can do something,” he said. It has been an amazing two days – we can’t wait for Vision 2023!
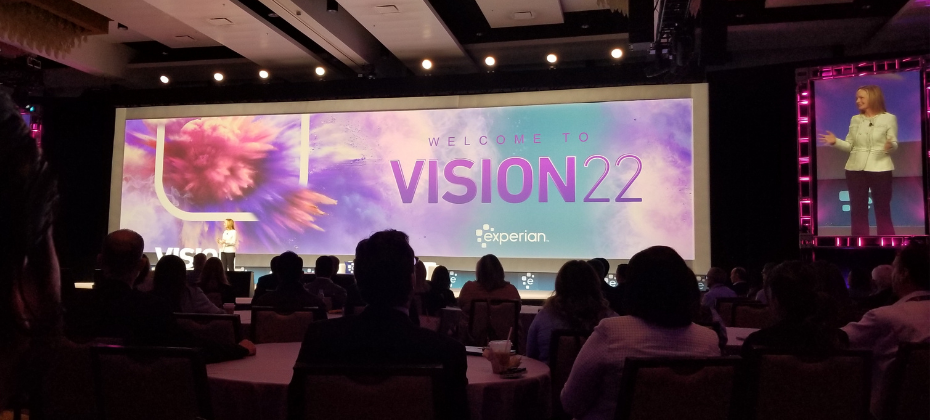
“Disruption has caused enormous amounts of innovation,” said Jennifer Schulz, CEO of Experian, North America. “We must continue to be the disruptors in our industry which takes effort, data, technology, bright minds and vision for what the future will be.” Schulz kicked off the 39th Vision conference with a future-focused keynote delivered to a crowd of more than 400 attendees. Alex Lintner, Group President, Experian Consumer Information Services, talked about the next phase of great, highlighting the digital transformation that has taken place in the generations of the past and the disruption and innovation happening today and in the future. Keynote speaker: Dr. Mohamed A. El-Erian Dr. Mohamed A. El-Erian, renowned economist and author, President of Queens’ College, Cambridge, Chief Economic Advisor at Allianz, Chair of President Obama’s Global Development Council and Former CEO and Co-Chief Investment Officer of PIMCO, spoke about the Fed, inflation, negative interest rates and the labor market, as well as the importance of inclusion. El-Erian, who said he reads the Financial Times religiously, acknowledged that we will make mistakes on the journey as we work to be even more inclusive. To navigate what’s ahead, he said we will need resilience, optionality and agility. “It’s important to connect with information, acknowledge the insecurity, in a language people understand, in order to connect,” he said. Session highlights – day 1 The conference hall was buzzing with conversations, discussions and thought leadership. Buy Now Pay Later A large audience was in attendance for a session that introduced Experian’s Buy Now Pay Later Bureau™ and explored how it’s the first and only solution of its kind — serving consumers, BNPL providers, financial institutions and regulators. Identity Identity is constantly evolving, and while biometrics and authentication may have become ubiquitous, there is much activity around the concepts of eIDs, identity wallets and identity networks. Experian is making identities personal and helping businesses to recognize, manage and connect customer identities in new ways using data, analytics and technology. Marketing In today’s hypercompetitive world, businesses need to engage the freshest data and increase velocity when it comes to time to market. An average of 120 days won’t cut it. Ascend Marketing speeds time to market and helps achieve higher ROI. Regulatory Landscape With so much happening at Capitol Hill, a panel of experts from DC discussed a number of topics and proposals (and their impacts), including the defense for risk-based pricing, the impact of suppressing negative data, and trending topics like Buy Now Pay Later and data portability. All the while, the tech showcase had a constant flow of attendees with demos ranging from data and decisioning to financial inclusion and technology. This is just the beginning. And as Schulz said, “There’s more to do.” More insights from Vision to come. Follow @ExperianVision to see more of the action.
Rewards are among the most appealing features of any credit card. While upfront benefits, like sign-up bonuses and cashback, are most influential in card acquisition, ancillary benefits, like fraud and identity protection, can amplify a card’s overall value.1 Credit card fraud ranked as the second most common form of identity theft in 2021,2 and is expected to become even more frequent as consumers continue to bank and shop online.3 42% of consumers are concerned for the safety of their banking and shopping transactions. With digital identity theft and fraud on the rise, it’s no surprise that safety measures are “very” or “extremely” important to consumers when deciding between different credit cards.4 In response, many card issuers have started to market their security and protection-related benefits more frequently to better capitalize on their cards’ value to consumers. The ways they’ve highlighted these benefits include: A fraud protection campaign From spotlighting their fraud protection benefits in card welcome kits to providing privacy tips on social media, credit card issuers have crafted compelling campaigns to demonstrate their commitment to protecting their customers from fraud and identity theft. In turn, issuers can differentiate their cards from the competition and improve response rates. Reminders about their fraud prevention efforts Issuers have also sent out ongoing reminders outlining the protections their credit cards offer, such as credit monitoring services 5 that notify cardholders of suspicious activity on their credit report. By consistently promoting their efforts to keep their customers’ accounts and data safe, issuers can earn their cardholders’ trust, build loyalty and drive card usage. While benefits like cashback and travel points can help with card acquisition, fraud and identity protection benefits can help drive long-term customer relationships, especially now that card fraud is becoming a growing concern.6 To learn more about how businesses have worked to meet the consumer demand for secure interactions, check out our 2021 Global Identity and Fraud Report. Learn more 1Jonathan O'Connor. "Most Consumers Aren't Aware of Their Credit Cards' Ancillary Benefits. How Does This Impact Card Acquisition and Usage?" TSYS, January 2019 2FTC. "Consumer Sentinel Network" Data Book, 2021 3April Berthene. "Coronavirus pandemic adds $219 billion to US ecommerce sales in 2020-2021" Digital Commerce 360, March 2022 4"Consumers Consider as Many as Six Factors When Choosing Credit Card" PYMTS.com, December 2021 5David McMillin. "Identity theft is a major problem, but these 5 credit card protection programs can help keep you safe" Business Insider, June 2021 6"New FICO Survey Finds Overconfidence Could Put US Consumers at Risk From Scams" Business Wire, February 2022
Learn how expanded FCRA-regulated data can be used to gain a more powerful and complete view of consumers' financial situations. Read more.
In today’s evolving and competitive market, the stakes are high to deliver both quantity and quality. That is, to deliver growth goals while increasing customer satisfaction. OneAZ Credit Union is the second largest credit union in Arizona, serving over 157,000 members across 21 branches. Wanting to fund more loans faster and offer a better member experience through their existing loan origination system (LOS), OneAZ looked to improve their decisioning system and long-standing underwriting criteria. They partnered with Experian to create an automated underwriting strategy to meet their aggressive approval rate and loss rate goals. By implementing an integrated decisioning system, OneAZ had flexible access to data credit attributes and scores, resulting in increased automation through their existing LOS – meaning they didn’t have to completely overhaul their decisioning systems. Additionally, they leveraged software that enabled champion/challenger strategies and the flexibility to manage their decision criteria. Within one month of implementation, OneAZ saw a 26% increase in loan funding rates and a 25% decrease in manual reviews. They can now pivot quickly to respond to continuously evolving conditions. “The speed at which we can return a decision and our better understanding of future performance has really propelled us in being able to better serve our members,” said John Schooner, VP Credit Risk Management at OneAZ. Read our case study for more insight on how automation and Experian Decisioning can move the needle for your organization, including: Streamlined strategy development and execution to minimize costly customizations and coding Comprehensive data assets across multiple sources to ensure ID verification and a holistic view of your prospect Proactive monitoring and real-time visibility to challenge and rapidly adjust strategies as needed Download the full case study
As more consumers apply for credit and increase their spending1, lenders and financial institutions have an opportunity to expand their portfolios and improve profitability. The challenge is ensuring they’re extending credit responsibly and inclusively. Millions of Americans, many of whom are creditworthy, lack access to mainstream credit options. This may be because they have limited or no credit history, negative information within their credit file, or are a part of a historically disadvantaged group. To say “yes” to consumers they otherwise couldn’t or wouldn’t lend to, lenders must gain a deeper understanding of an individual’s stability, ability and willingness to pay. That’s where expanded FCRA-regulated and trended data come in. While traditional credit data has long been the primary means of gauging creditworthiness, it doesn’t tell the full story of a consumer’s financial situation. Let’s explore how differentiated data can help lenders make more informed credit decisions. Using differentiated data for deeper lending Expanded FCRA-regulated data provides supplemental credit data to help lenders gain a more holistic view of their current and prospective customers. Some examples of expanded FCRA-regulated data include alternative financial services data from nontraditional lenders, consumer-permissioned account data, rental payments and full-file public records. Because this data drives greater visibility and transparency around inquiry and payment behaviors, lenders can more accurately determine a consumer’s ability to pay and distinguish between reliable and high-risk applicants. In turn, lenders can approve more creditworthy consumers, grow their portfolios and increase financial opportunities for underserved communities, all while preventing and mitigating risk. 89% of lenders agree that expanded FCRA-regulated data allows them to extend credit to more consumers. Trended data empowers lenders with predictive insights into consumers by providing key balance and payment data for the previous 24 months. This is important as lenders can determine if a consumer’s credit behavior has improved or deteriorated over time. In turn, lenders can: Identify creditworthy customers: Establish if a consumer has a demonstrated ability to pay, is consistently paying more than the minimum payment, or shows no signs of payment stress. Increase response rates: Match the right products with the right prospects. Determine upsell and cross-sell opportunities: Present relevant offers based on anticipated needs and behaviors. Limit loss exposure: Understand the direction and velocity of payment performance to effectively manage risk exposure. Trended data helps lenders better predict future behavior, manage portfolio risk and design the best marketing offers. Turning insights into action Together, trended and expanded FCRA-regulated data benefit lenders and consumers alike. With a more holistic view of their customers, lenders gain powerful insights to lend deeper, ultimately helping them to expand their portfolios and drive greater access to credit for underserved communities. Learn more 1 The Recovery of Credit Applications to Pre-Pandemic Levels, Consumer Financial Protection Bureau, 2021.
Lenders are increasingly under pressure to improve access to the financial system and help close the wealth gap in America. Read more!
Lenders and servicers should anticipate an influx of questions and possiby borrower deliquencies as student loan forbearance comes to an end. Read more.