 Perhaps more than ever before, technology is changing how companies operate, produce and deliver products and services to their customers. Similarly, technology is also driving a shift in customer expectation in how, when and where they consume products and services. But these changes aren’t just relegated to the arenas where tech giants with household names, like Amazon and Google, play. Likewise, financial institutions of every size are also fielding the changes brought on by innovations to the industry in recent years.
According to this report by PWC, 77% of firms plan on dedicating time and budgets to increase innovation. But what areas make the most sense for your business? With a seemingly constant shift in consumer and corporate focus, it can be difficult to know which technological advancements are imperative to your company’s success and which are just the latest fizzling buzzword. As you evaluate innovation investments for your organization in 2019 and beyond, here’s a list of four technology innovations that are already changing the financial sector or will change the banking landscape in the near future.
The APIs of Open Banking
Ok, it’s not a singular innovation, so I’m cheating a bit here, but it’s a great place to begin the conversation because it comprises and sets the stage for many of the innovations and technologies that are in use today or will be implemented in the future. Created in 2015, the Open Banking Standard defined how a bank’s system data or consumer-permissioned financial data should be created, accessed and shared through the use of application programming interfaces or APIs.
When financial institutions open their systems up to third-party developer partners, they can respond to the global trends driving change within the industry while greatly improving the customer experience. With the ability to securely share their financial data with other lenders, greater transparency into the banking process, and more opportunities to compare product offerings, consumers get the frictionless experience they’ve come to expect in just about every aspect of life – just not necessarily one that lenders are known for.
But the benefits of open banking are not solely consumer-centric. Financial institutions are able to digitize their product offerings and thus expand their market and more easily share data with partners, all while meeting clients’ individualized needs in the most cost-effective way.
Biometrically speaking…and smiling
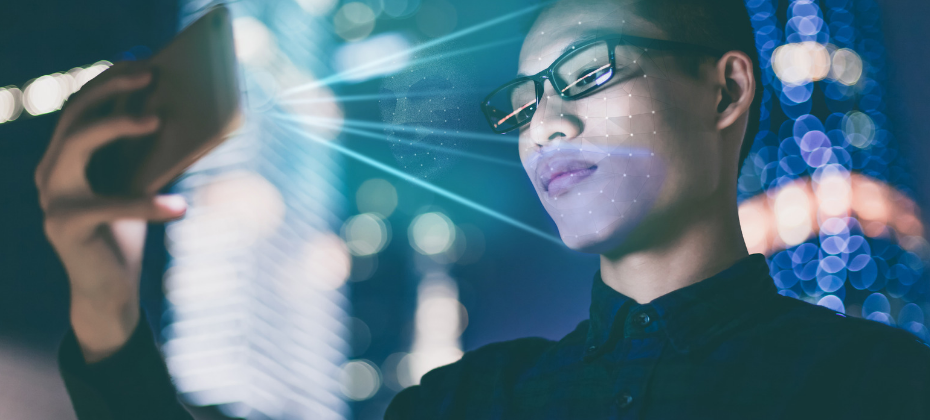
Verifying the identity of a customer is perhaps one of the most fundamental elements to a financial transaction. This ‘Know Your Customer’ (KYC) process is integral to preventing fraud, identity theft, money laundering, etc., but it’s also time-consuming and inconvenient to customers. Technology is changing that. From thumbprint and, now, facial recognition through Apple Pay, consumers have been using biometrics to engage with and authorize financial transactions for some time now. As such, the use of biometrics to authenticate identity and remove friction from the financial process is becoming more mainstream, moving from smartphones to more direct interaction.
Chase has now implemented voice biometrics to verify a consumer’s identity in customer service situations, allowing the company to more quickly meet a customer’s needs. Meanwhile, in the US and Europe, Visa is testing biometric credit cards that have a fingerprint reader embedded in the card that stores his or her fingerprint in order to authenticate their identity during a financial transaction. In China, companies like Alipay are taking this to the next level by allowing customers to bypass the phone entirely with its ‘pay with a smile’ service. First launched in KFC restaurants in China, the service is now being offered at hospitals as well.
How, when and where a consumer accesses their financial institution data actually creates a digital fingerprint that can be verified. While facial and vocal matching are key components to identity verification and protecting the consumer, behavioral biometrics have also become an important part of the fraud prevention arsenal for many financial institutions. These are key components of Experian’s CrossCore solution, the first open fraud and identity platform partners with a variety of companies, through open APIs discussed above.
Not so New Kid on the Block(chain)
The first Bitcoin transaction took place on January 12, 2009. And for a number of years, all was quiet. Then in 2017, Bitcoin started to blow up, creating a scene reminiscent of the 1850s California gold rush. Growing at a seemingly exponential rate, the cryptocurrency topped out at a per unit price of more than $20,000. By design cryptocurrencies are decentralized, meaning they are not controlled or regulated by a single entity, reducing the need for central third-party institutions, i.e. banks and other financial institutions to function as central authorities of trust. Volatility and regulation aside, it’s understandable why financial institutions were uneasy, if not skeptical of the innovation.
But perhaps the most unique characteristic of cryptocurrencies is the technology on which they are built: blockchain. Essentially, a blockchain is just a special kind of database. The database stores, validates, transfers and keeps a ledger of transfers of encrypted data—records of financial transfers in the case of Bitcoin. But these records aren’t stored on one computer as is the case with traditional databases. Blockchain leverages a distributed ledger or distributed trust approach where a full copy of the database is stored across many distributed processing nodes and the system is constantly checking and validating the contents of the database.
But a blockchain can store any type of data, making it useful in a wide variety of applications including tracking the ownership digital or physical assets or the provenance of documents, etc. From clearing and settlements, payments, trade finance, identity and fraud prevention, we’re already seeing financial institutions explore and/or utilize the technology. Santander was the first UK bank to utilize blockchain for their international payments app One Pay FX. Similarly, other banks and industry groups are forming consortiums to test the technology for other various uses. With all this activity, it’s clear that blockchain will become an integral part of financial institutions technology and operations on some level in the coming years.
Robot Uprising Rise in Robots
While Artificial Intelligence seems to have only recently crept into pop-culture and business vernacular, it was actually coined in 1956 by John McCarthy, a researcher at Dartmouth who thought that any aspect of learning or intelligence could essentially be taught to a machine. AI allows machines to learn from experience, adjust to new inputs and carry out human-like tasks. It’s the result of becoming ‘human-like’ or the potential to become superior to humans that creeps out people like my father, and also worries others like Elon Musk. Doomsday scenarios a la Terminator aside, it’s easy to see how the tech can and is useful to society. In fact, much of the AI development done today uses human-style reasoning as a model, but not necessarily the ultimate aim, to deliver better products and services.
It’s this subset of AI, machine learning, that allows companies like Amazon to provide everything from services like automatic encryption in AWS to products like Amazon Echo. While it’s much more complex, a simple way to think about AI is that it functions like billions of conditional if-then-else statements working in a random, varied environment typically towards a set goal. Whereas in the past, programmers would have to code these statements and input reference data themselves, machine learning systems learn, modify and map between inputs and outputs to create new actions based on their learning. It works by combining the large amounts of data created on a daily basis with fast, iterative processing and intelligent algorithms, allowing the program to learn from patterns in the data and make decisions. It’s this type of machine learning that banks are already using to automate routine, rule-based tasks like fraud monitoring and also drive the analytical environments used in their risk modeling and other predictive analytics.
Whether or not you’ve implemented AI, machine learning or bot technology into your operations, it’s highly likely your customers are already leveraging AI in their home lives, with smart home devices like Amazon Echo and Google Home. Conversational AI is the next juncture in how people interface with each other, companies and life in general. We’re already seeing previews of what’s possible with technologies like Google Duplex. This has huge implication for the financial services industry, from removing friction at a transaction level to creating a stickier, more engaging customer experience. To that end, according to this report from Accenture, AI may begin to provide in-the-moment, holistic financial advice that is in a customer’s best interest.
It goes without saying that the market will continue to evolve, competition will only grow more fierce, consumer expectation will continue to shift, and regulation will likely become more complex. It’s clear technology can be a mitigating factor, even a competitive differentiator, with these changing industry variables. Financial institutions must evolve corporate mindsets in their approach to prioritize innovations that will have the greatest enterprise-wide impact. By putting together an intelligent mix of people, process, and the right technology, financial institutions can better predict consumer need and expectation while modernizing their business models.