Tag: fraud
Manual processes are quietly expensive. Every handoff between teams, every file transfer waiting in a queue and every decision that sits on someone's desk adds cost, introduces risk and slows the customer experience. For financial institutions, those delays translate directly into lost revenue and eroded margins. That’s why workflow automation is becoming critical for financial institutions looking to stay competitive. Done well, it doesn't just make existing tasks faster. It reshapes how decisions get made across the entire customer lifecycle, from the first marketing touch to account servicing and beyond. What is workflow automation? Workflow automation is the use of technology to run a sequence of tasks, decisions and handoffs with minimal manual intervention. Instead of a person moving work from one step to the next — pulling data, applying a rule, routing an account and sending a communication — software executes those steps automatically based on defined logic and real-time data. For financial institutions, workflow automation usually combines four ingredients: Data Connecting to the internal and external data sources that inform a decision. Analytics Scores, models and attributes that turn raw data into insights. Decisioning A rules engine that determines the right action for each customer or account. Execution The operational layer that carries out the action, whether that's an offer, a credit line change or outreach. The benefits of workflow automation The value of automation goes well beyond "doing the same thing faster." The benefits financial institutions consistently see include:Greater efficiency and lower operating costsAutomation frees underwriters, analysts and agents to focus on exceptions and high-value work rather than repetitive processing. Faster, more consistent decisionsA credit application that once waited in a queue can be assessed in real time against consistent, auditable policies, improving both the applicant's experience and portfolio quality. Better customer experiencesAutomation enables financial institutions to personalize communications at the point of interaction and offer the self-service options that many people now prefer. Improved compliance and governanceReduce the risk of costly compliance failures with built-in controls, audit trails and guided workflows. ScalabilityRespond to changing volumes without sacrificing speed, consistency or the customer experience. Where workflow automation makes the biggest difference Workflow automation tends to deliver the most value where decisions are frequent, repeatable and informed by data. In financial services, those opportunities exist across the customer lifecycle. Onboarding Onboarding is a customer's first experience of your organization, and it's also where friction can cause customers to abandon the process and turn to another provider. Forty percent of U.S. consumers have considered walking away from opening a new account when the process felt burdensome.1 An automated onboarding workflow can bring together document verification, device intelligence, behavioral analytics, credit attributes and more, then orchestrate them into a single decision. The result is a lower-friction experience for the customer and a consistent, auditable process. Once customers are on the books, serving them well means making continuous, high-volume decisions: credit line changes, cross-sell and up-sell opportunities, risk monitoring and retention actions. Automation makes it practical to run these recurring decisions consistently across an entire portfolio, using a holistic view of each customer that draws on multiple scores and attributes. Lending The underwriting process is a great example of how workflow automation can help prevent applicants from waiting days for an answer. Loan origination and credit decisioning capabilities are designed to create a seamless review process across consumer and commercial lending. After automating originations with our solutions, Michigan State University Federal Credit Union cut application processing time to under 24 hours. Fraud Financial institutions are checking fraud at every touchpoint, and the standard for AI fraud detection continues to rise as fraudsters use AI to slip under the thresholds of any single detection tool. Rather than running fraud checks in isolation, an automated workflow can run multiple fraud and identity verification services in parallel and weigh signals together. A fraud decisioning platform connects signals across internal systems, Experian data and third-party services, allowing teams to stay on top of evolving threats. Build a strong foundation for workflow automation Workflow automation can connect these stages, creating a consistent decisioning framework. What ultimately separates good automation from great automation is the quality of the data and decisioning software underneath it. An automated workflow is only as good as the information feeding it. That's where our comprehensive credit, alternative and identity data with the tools financial institutions need to act on it. Learn more here FAQs How does automated decisioning improve credit decisions? Automated decisioning applies consistent logic to every account in real time or in bulk, enabling faster and more informed decisions, quicker responses to market and regulatory changes at the point of interaction. What is workflow automation in financial services? It's the use of software to execute sequences of data gathering, analysis, decisioning and action. Does workflow automation replace human judgment? No. The goal is to automate routine, high-volume decisions so skilled staff can focus on the exceptions and complex cases that genuinely require human judgment. For example, a sensitive collections conversation or a nuanced underwriting call. Are we still compliant with regulations if we use an automated workflow process? Well-designed platforms include built-in governance, audit trails and compliance controls that help institutions align with requirements like the Fair Credit Reporting Act (FCRA) and other regulatory guidelines improving compliance compared with manual processes. How long does it take to implement? It varies by solution and scope, but modern cloud-based platforms are designed for fast onboarding and limited IT involvement. 1Global Fraud Snapshot 2025: Opportunities and challenge in identity, fraud and financial crime
Fraudsters are getting surprisingly good at onboarding. Sometimes, better than your customers. Legitimate customers treat onboarding like an errand. They start an application between other tasks, get distracted, forget a password, switch devices, upload a document or come back later to finish. Their digital lives aren’t always linear, because real life isn’t either. Fraudsters approach onboarding differently. For them, opening an account is the objective. Every interaction is designed to increase the odds of success. The difference raises an uncomfortable question hanging over onboarding: What exactly are we rewarding? When smooth becomes suspicious Digital onboarding has traditionally rewarded experiences that feel smooth, consistent and complete. The challenge is that legitimate customers rarely behave that way. Most people approach onboarding somewhere between mildly distracted and mildly annoyed. They pause halfway through because dinner is burning. They reopen an old account only to realize everything is attached to an email they made in college and, somehow, still use for airline receipts. Digital life accumulates history unevenly, because ordinary life does too. Fraudsters have every reason to eliminate those inconsistencies. Applications may be rehearsed. Identity attributes are assembled deliberately. Contact points are prepared in advance. Every interaction is optimized to make the application appear credible. Ironically, the qualities organizations often associate with confidence — clean submissions, steady progression and few corrections — can also describe applications that have been carefully engineered to pass inspection. The challenge isn't that smooth onboarding is meaningless. It's that smooth onboarding, by itself, doesn't tell the whole story. Context changes interpretation A smooth onboarding experience should be the beginning of the evaluation, not the end. Behavior provides important context. How someone moves through an application can reveal whether the experience feels naturally human or unusually orchestrated. Do they interact naturally? Do they hesitate, correct mistakes or navigate in ways that resemble ordinary human behavior? Or does the session appear unusually scripted, automated or repetitive? Identity verification adds another layer. Matching information across trusted sources, validating identity details and strengthening confidence in account creation remain important, particularly when onboarding decisions carry financial, fraud or customer experience consequences. But verification largely answers a point-in-time question: Does this information match right now? A third layer comes from digital history. An inbox attached to years of airline receipts, loyalty accounts, subscription renewals, account recovery, financial notifications and familiar digital routines introduces a different kind of confidence. Legitimate digital identities leave behind patterns of persistence and engagement that develop gradually over time. Fraudsters can assemble convincing identity attributes, but creating years of ordinary digital life is much harder. Building confidence in an identity requires more than verifying information submitted during a single onboarding session. It requires understanding whether the identity reflects a broader history that supports what the application suggests. A multilayered approach builds stronger identity confidence No single signal can provide a complete view of identity risk. Organizations need multiple sources of confidence that reinforce one another. That's the thinking behind our approach: combining behavioral intelligence, identity verification and digital identity continuity into a more complete view of risk. We bring these complementary layers together through: • NeuroID adds behavioral context during onboarding and account creation, helping identify interaction patterns that may indicate automation, manipulation or coordinated fraud. • Precise ID® strengthens identity verification and resolution by comparing applicant information with trusted identity data. • AtData, recently added to our portfolio, contributes email-centered intelligence based on persistence, engagement and long-term digital history. Together, these capabilities help organizations move beyond evaluating a single moment in time to understanding whether an identity is supported by consistent behavior, trusted identity data and an established digital history. The future of fraud prevention isn't about rewarding the smoothest application. It's about recognizing the most trustworthy identity. Fraudsters can rehearse an application. They can optimize an onboarding journey. They can even assemble convincing identity attributes. What they can't easily manufacture is years of ordinary digital life. That's why digital identity continuity has become an important layer of modern fraud prevention. Combined with identity verification and behavioral intelligence, it helps organizations distinguish between identities that simply look convincing and those supported by a history that is much harder to fake. Learn more Contact us
Every retailer invests heavily to drive shoppers to its website during the holidays. But after months of planning and thousands to millions of dollars spent on marketing, every customer journey comes down to one critical moment: Checkout. Today, fraud prevention means protecting revenue by ensuring legitimate customers complete their purchase, not just stopping bad actors. That's becoming increasingly important as holiday shopping evolves. In 2025, U.S. online holiday spending reached a record $257.8 billion,1 with shoppers spreading their purchases across months rather than just Black Friday and Cyber Monday. Every approval and every false decline has a bigger business impact than ever. Trust is becoming a conversion strategy Consumers expect retailers to protect them from fraud, but they don't want that protection to slow them down. That's where a significant opportunity exists. Experian research found that 52% of consumers expect retailers to protect them online, yet only 19% trust them to do so.2 Meanwhile, payment providers enjoy a positive trust gap because security happens quietly in the background with minimal friction. The takeaway? Customers don't equate more authentication with more trust. Instead, they equate less friction with better experiences. Learn how retailers can improve approvals, reduce false declines and build customer trust through layered identity intelligence. Download the white paper Invisible security is the future of checkout Modern identity verification, behavioral analytics and account intelligence allow retailers to recognize trusted customers behind the scenes – reserving step-up authentication only for higher-risk transactions. Why does that matter? Because friction is measurable. Research from Experian and cited in our white paper, shows that 16% of online transactions encounter suspected fraud friction, and 70% of that friction is unnecessary.3 Meanwhile, 25% of consumers abandon the purchase after experiencing onboarding friction, choosing a competitor instead. Reducing unnecessary friction isn't just good customer experience; it's good business. One retailer that used Experian's account ownership verification and identity intelligence captured more than $8 million in additional monthly revenue by improving auto-approval strategies and reducing customer friction. Learn how to protect revenue, not just prevent fraud As holiday traffic ramps up, retailers have an opportunity to rethink checkout as more than a fraud control. It's a revenue engine. Our latest white paper explores how layered identity strategies can help retailers improve approvals, reduce false declines and deliver the frictionless experiences customers increasingly expect. Download the full white paper to learn how invisible security can help strengthen customer trust while maximizing holiday conversion. Download now
Every year, consumers say they'll spend less during the holidays. Every year, many do the opposite. Ahead of the 2025 holiday shopping season, 57% of consumers told Deloitte they expected the economy to weaken, the most pessimistic outlook recorded in the survey's history. Planned holiday spending was down 10%. Yet by the end of the season, online holiday sales reached a record $257.8 billion, up 6.8% year over year. Credit card balances climbed to $1.28 trillion, and Buy Now, Pay Later (BNPL) financing surpassed $20 billion during the holiday period. For lenders, the takeaway is to identify and engage the right consumers before the holidays were best equipped to capture that spending while effectively managing risk. As the 2026 holiday season approaches, Experian's latest market insights suggest that while credit performance appears relatively stable at the portfolio level, important shifts beneath the surface are changing how lenders should evaluate both opportunity and risk. Holiday shopping season 2026 Winning top of wallet before the holiday swipe Download the white paper now Holiday lending decisions happen long before the holidays It’s been observed that the holiday shopping season has expanded – beginning before Black Friday – over recent years. While Cyber Week continues to generate headlines, holiday spending is becoming more distributed throughout the quarter. For lenders, that means strategies must be in place before peak shopping begins. Credit line increases, portfolio reviews, acquisition strategies and risk segmentation completed in late summer often determine how much holiday spending an institution can safely capture. At the same time, early signs of credit deterioration are emerging faster than traditional portfolio metrics suggest reinforcing the importance of identifying emerging portfolio risk early rather than relying solely on broad portfolio performance indicators. Income is becoming a stronger predictor of credit performance One of the most notable shifts in today's lending environment is the growing relationship between income and future credit performance. Experian's data suggests the market is becoming increasingly polarized. The population earning more than $250,000 annually has more than doubled since 2023, but more than one-quarter of those consumers have since moved into lower income brackets, often following retirement or job loss. Meanwhile, consumers earning less than $50,000 annually show relatively little income mobility, with approximately 85% remaining in the same income band year-over-year. These trends highlight an important reality: a credit score alone may no longer provide a complete picture of borrower risk. Four priorities before peak holiday spending With only a short window before holiday borrowing accelerates, lenders have an opportunity to strengthen both growth and risk strategies. Key areas of focus include: Refine acquisition strategies Move beyond score-only targeting by incorporating verified income, cash flow and existing credit relationships to identify qualified borrowers. Optimize existing portfolios Identify customers demonstrating positive credit migration and proactively evaluate opportunities to increase credit lines before peak spending begins. Monitor emerging credit risks Use early-stage delinquency indicators and behavioral signals to identify potential performance issues before losses accelerate. Strengthen fraud management and prevention Seasonal account openings and increased transaction volumes create greater fraud exposure. Identity verification, synthetic identity detection and dormant account monitoring remain critical during high-volume acquisition periods. Preparing for the holiday shopping season ahead The 2025 holiday season demonstrated that consumer spending decisions don't always align with consumer sentiment. How does that translate for the 2026 shopping season? For lenders, success will depend less on reacting to spending trends in November and more on making informed credit decisions months earlier. As consumer financial behavior continues to evolve, combining traditional credit data with income, cash flow and alternative data can provide a more complete understanding of both opportunity and risk. Institutions that incorporate these broader insights into acquisition, portfolio management and fraud strategies will be better positioned to grow responsibly during one of the year's most active lending periods. Ready to learn more? Access the full white paper
Learn how ChexSystems and Experian help financial institutions strengthen consumer fraud monitoring and build customer trust.
Learn what agentic commerce is, why AI agents are transforming digital commerce and how Agent Trust builds trusted AI interactions.
Reduce first-party fraud and chargebacks with data-driven strategies that help merchants prevent disputes, protect revenue and improve customer trust.
Fraud is evolving faster than ever, driven by digitalization, real-time payments and increasingly sophisticated scams. For Warren Jones and his team at Santander Bank, staying ahead requires more than tools. It requires the right partner. The partnership with Santander Bank began nearly a decade ago, during a period of rapid change in the fraud and banking landscape. Since then, the relationship has grown into a long-term collaboration focused on continuous improvement and innovation. Experian products helped Santander address one of its most pressing operational challenges: a high-volume manual review queue for new account applications. While the vast majority of alerts in the queue were fraudulent and ultimately declined, a small percentage represented legitimate customers whose account openings were delayed. This created inefficiencies for staff and a poor first impression of genuine applicants. We worked alongside Santander to tackle this challenge head-on, transforming how applications were reviewed, how fraud was detected and how legitimate customers were approved. In addition to fraud prevention, implementing Experian's Ascend PlatformTM, with its intuitive user experience and robust data environment, has unlocked additional value across the organization. The platform supports multiple use cases, enabling collaboration between fraud and marketing teams to align strategies based on actionable insights. Learn more about our Ascend Platform
For lenders, the job has never been more complex. You’re expected to protect portfolio performance, meet regulatory expectations, and support growth, all while fraud tactics evolve faster than many traditional risk frameworks were designed to handle. One of the biggest challenges of the job? The line between credit loss and fraud loss is increasingly blurred, and misclassified losses can quietly distort portfolio performance. First-party fraud can look like standard credit risk on the surface and synthetic identity fraud can be difficult to identify, allowing both to quietly slip through decisioning models and distort portfolio performance. That’s where fraud risk scores come into play. Used correctly, they don’t replace credit models; they strengthen them. And for credit risk teams under pressure to approve more genuine customers without absorbing unnecessary losses, understanding how fraud risk scores fit into modern decisioning has become essential. What is a fraud risk score (and what isn’t it) At its core, a fraud risk score is designed to assess the likelihood that an applicant or account is associated with fraudulent behavior, not simply whether they can repay credit. That distinction matters. Traditional credit scores evaluate ability to repay based on historical financial behavior. Fraud risk scores focus on intent and risk signals, patterns that suggest an individual may never intend to repay, may be manipulating identity data, or may be building toward coordinated abuse. Fraud risk scores are not: A replacement for credit scoring A blunt tool designed to decline more applicants A one-time checkpoint limited to account opening Instead, they provide an additional lens that helps credit risk teams separate true credit risk from fraud that merely looks like credit loss. How fraud scores augment decisioning Credit models were never built to detect fraud masquerading as legitimate borrowing behavior. Consider common fraud scenarios facing lenders today: First-payment default, where an applicant appears creditworthy but never intends to make an initial payment Bust-out fraud, where an individual builds a strong credit profile over time, then rapidly maxes out available credit before disappearing Synthetic identity fraud, where criminals blend real and fabricated data to create identities that mature slowly and evade traditional checks In all three cases, the applicant may meet credit criteria at the point of decision. Losses can get classified as charge-offs rather than fraud, masking the real source of portfolio degradation. When credit risk teams rely solely on traditional models, the result is often an overly conservative response: tighter credit standards, fewer approvals, and missed growth opportunities. How fraud risk scores complement traditional credit decisioning Fraud risk scores work best when they augment credit decisioning. For credit risk officers, the value lies in precision. Fraud risk scores help identify applicants or accounts where behavior, velocity or identity signals indicate elevated fraud risk — even when credit attributes appear acceptable. When integrated into decisioning strategies, fraud risk scores can: Improve confidence in approvals by isolating high-risk intent early Enable adverse-actionable decisions for first-party fraud, supporting compliance requirements Reduce misclassified credit losses by clearly identifying fraud-driven outcomes Support differentiated treatment strategies rather than blanket declines The goal isn’t to approve fewer customers. It’s to approve the right customers and to decline or treat risk where intent doesn’t align with genuine borrowing behavior. Fraud risk across the credit lifecycle One of the most important shifts for credit risk teams is recognizing that fraud risk is not static. Fraud risk scores can deliver value at multiple stages of the credit lifecycle: Marketing and prescreen: Fraud risk insights help suppress high-risk identities before offers are extended, ensuring marketing dollars are maximized by targeting low risk consumers. Account opening and originations: Real-time fraud risk scoring supports early detection of first-party fraud, synthetic identities, and identity misuse — before losses are booked. Prequalification and instant decisioning: Fraud risk scores can be used to exclude high-risk applicants from offers while maintaining speed and customer experience. Account management and portfolio review: Fraud risk doesn’t end after onboarding. Scores applied in batch or review processes help identify accounts trending toward bust-out behavior or coordinated abuse, informing credit line management and treatment strategies. This lifecycle approach reflects a broader shift: fraud prevention is no longer confined to front-end controls — it’s a continuous risk discipline. What credit risk officers should look for in a fraud risk score Not all fraud risk scores are created equal. When evaluating or deploying them, credit risk officers should prioritize: Lifecycle availability, so fraud risk can be assessed beyond originations Clear distinction between intent and ability to repay, especially for first-party fraud Adverse-action readiness, including explainability and reason codes Regulatory alignment, supporting fair lending and compliance requirements Seamless integration alongside existing credit and decisioning frameworks Increasingly, credit risk teams also value platforms that reduce operational complexity by enabling fraud and credit risk assessment through unified workflows rather than fragmented point solutions. A more strategic approach to fraud and credit risk The most effective credit risk strategies today are not more conservative, they’re more precise. Fraud risk scores give credit risk officers the ability to stop fraud earlier, classify losses accurately and protect portfolio performance without tightening credit across the board. When fraud and credit insights work together, teams can gain a clearer view of risk, stronger decision confidence and more flexibility to support growth. As fraud tactics continue to evolve, the organizations that succeed will be those that can effectively separate fraud from credit loss. Fraud risk scores are no longer a nice-to-have. They’re a foundational tool for modern credit risk strategies. How credit risk teams can operationalize fraud risk scores For credit risk officers, the challenge isn’t just understanding fraud risk, it’s operationalizing it across the credit lifecycle without adding friction, complexity or compliance risk. Rather than treating fraud as a point-in-time decision, credit risk teams should assess fraud risk where it matters most, from acquisition through portfolio management. Fraud risk scores are designed to complement credit decisioning by focusing on intent to repay, helping teams distinguish fraud-driven behavior from traditional credit risk. Key ways Experian supports credit risk teams include: Lifecycle coverage: Experian award-winning fraud risk scores are available across marketing, originations, prequalification, instant decisioning and ongoing account review. This allows organizations to apply consistent fraud strategies beyond account opening. First-party and synthetic identity fraud intelligence: Experian’s fraud risk scoring addresses first-payment default, bust-out behavior and synthetic identity fraud, which are scenarios that often bypass traditional credit models because they initially appear creditworthy. Converged fraud and credit decisioning: By delivering fraud and credit insights together, often through a single integration, Experian can help reduce operational complexity. Credit risk teams can assess fraud and credit risk simultaneously rather than managing disconnected tools and workflows. Precision over conservatism: The emphasis is not on declining more applicants, but on approving more genuine customers by isolating high-risk intent earlier. This precision helps protect portfolio performance without sacrificing growth. For lenders navigating increasing fraud pressure, Experian’s approach reflects a broader shift in the industry: fraud prevention and credit risk management are no longer separate disciplines; they are most effective when aligned. Explore our fraud solutions Contact us
For many banks, first-party fraud has become a silent drain on profitability. On paper, it often looks like classic credit risk: an account books, goes delinquent, and ultimately charges off. But a growing share of those early charge-offs is driven by something else entirely: customers who never intended to pay you back. That distinction matters. When first-party fraud is misclassified as credit risk, banks risk overstating credit loss, understating fraud exposure, and missing opportunities to intervene earlier. In our recent Consumer Banker Association (CBA) partner webinar, “Fraud or Financial Distress? How to Differentiate Fraud and Credit Risk Early,” Experian shared new data and analytics to help fraud, risk and collections leaders see this problem more clearly. This post summarizes key themes from the webinar and points you to the full report and on-demand webinar for deeper insight. Why first-party fraud is a growing issue for banks Banks are seeing rising early losses, especially in digital channels. But those losses do not always behave like traditional credit deterioration. Several trends are contributing: More accounts opened and funded digitally Increased use of synthetic or manipulated identities Economic pressure on consumers and small businesses More sophisticated misuse of legitimate credentials When these patterns are lumped into credit risk, banks can experience: Inflation of credit loss estimates and reserves Underinvestment in fraud controls and analytics Blurred visibility into what is truly driving performance Treating first-party fraud as a distinct problem is the first step toward solving it. First-payment default: a clearer view of intent Traditional credit models are designed to answer, “Can this customer pay?” and “How likely are they to roll into delinquency over time?” They are not designed to answer, “Did this customer ever intend to pay?” To help banks get closer to that question, Experian uses first-payment default (FPD) as a key indicator. At a high level, FPD focuses on accounts that become seriously delinquent early in their lifecycle and do not meaningfully recover. The principle is straightforward: A legitimate borrower under stress is more likely to miss payments later, with periods of cure and relapse. A first-party fraudster is more likely to default quickly and never get back on track. By focusing on FPD patterns, banks can start to separate cases that look like genuine financial distress from those that are more consistent with deceptive intent. The full report explains how FPD is defined, how it varies by product, and how it can be used to sharpen bank fraud and credit strategies. Beyond FPD: building a richer fraud signal FPD alone is not enough to classify first-party fraud. In practice, leading banks are layering FPD with behavioral, application and identity indicators to build a more reliable picture. At a conceptual level, these indicators can include: Early delinquency and straight-roll behavior Utilization and credit mix that do not align with stated profile Unusual income, employment, or application characteristics High-risk channels, devices, or locations at application Patterns of disputes or behaviors that suggest abuse The power comes from how these signals interact, not from any one data point. The report and webinar walk through how these indicators can be combined into fraud analytics and how they perform across key banking products. Why it matters across fraud, credit and collections Getting first-party fraud right is not just about fraud loss. It impacts multiple parts of the bank. Fraud strategy Well-defined quantification of first-party fraud helps fraud leaders make the case for investments in identity verification, device intelligence, and other early lifecycle controls, especially in digital account opening and digital lending. Credit risk and capital planning When fraud and credit losses are blended, credit models and reserves can be distorted. Separating first-party fraud provides risk teams a cleaner view of true credit performance and supports better capital planning. Collections and customer treatment Customers in genuine financial distress need different treatment paths than those who never intended to pay. Better segmentation supports more appropriate outreach, hardship programs, and collections strategies, while reserving firmer actions for abuse. Executive and board reporting Leadership teams increasingly want to understand what portion of loss is being driven by fraud versus credit. Credible data improves discussions around risk appetite and return on capital. What leading banks are doing differently In our work with financial institutions, several common practices have emerged among banks that are getting ahead of first-party fraud: 1. Defining first-party fraud explicitly They establish clear definitions and tracking for first-party fraud across key products instead of leaving it buried in credit loss categories. 2. Embedding FPD segmentation into analytics They use FPD-based views in their monitoring and reporting, particularly in the first 6–12 months on book, to better understand early loss behavior. 3. Unifying fraud and credit decisioning Rather than separate strategies that may conflict, they adopt a more unified decisioning framework that considers both fraud and credit risk when approving accounts, setting limits and managing exposure. 4. Leveraging identity and device data They bring in noncredit data — identity risk, device intelligence, application behavior — to complement traditional credit information and strengthen models. 5. Benchmarking performance against peers They use external benchmarks for first-party fraud loss rates and incident sizes to calibrate their risk posture and investment decisions. The post is meant as a high-level overview. The real value for your teams will be in the detailed benchmarks, charts and examples in the full report and the discussion in the webinar. If your teams are asking whether rising early losses are driven by fraud or financial distress, this is the moment to look deeper at first-party fraud. Download the report: “First-party fraud: The most common culprit” Explore detailed benchmarks for first-party fraud across banking products, see how first-payment default and other indicators are defined and applied, and review examples you can bring into your own internal discussions. Download the report Watch the on-demand CBA webinar: “Fraud or Financial Distress? How to Differentiate Fraud and Credit Risk Early” Hear Experian experts walk through real bank scenarios, FPD analytics and practical steps for integrating first-party fraud intelligence into your fraud, credit, and collections strategies. Watch the webinar First-party fraud is likely already embedded in your early credit losses. With the right analytics and definitions, banks can uncover the true drivers, reduce hidden fraud exposure, and better support customers facing genuine financial hardship.
Discover why Experian’s unified fraud prevention platform, backed by decades of data stewardship and AI innovation, is the trusted choice for enterprises seeking scalable, compliant, and transparent identity verification solutions.
Learn how you can mitigate e-commerce fraud with identity verification and fraud prevention best practices.
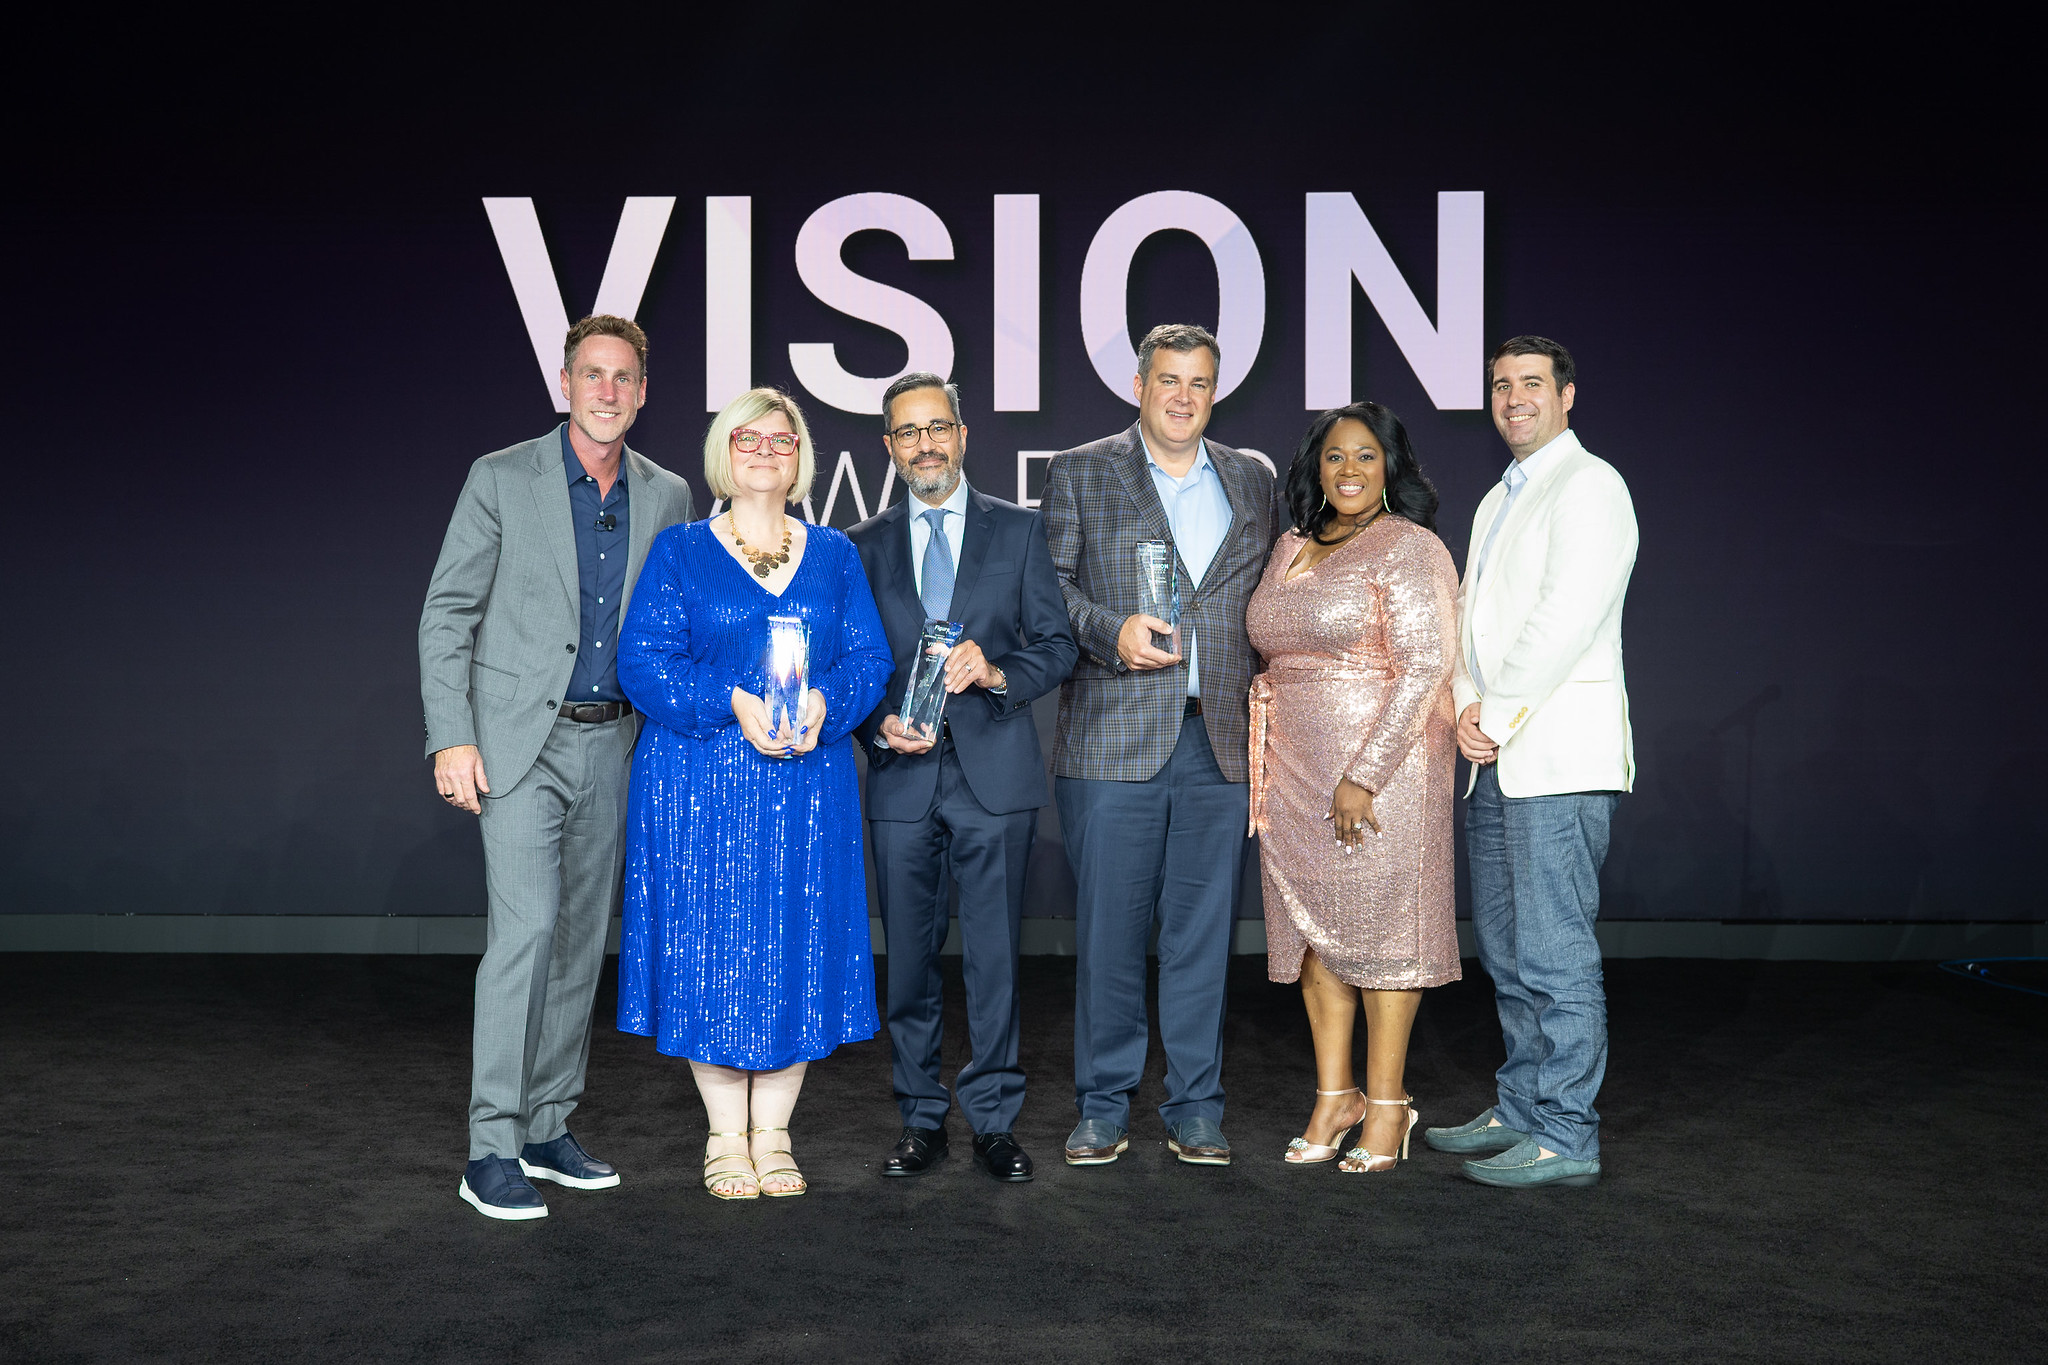
Three winners were announced at Experian’s inaugural Vision Awards ceremony held on Tuesday, October 7 in front of more than 800 attendees at Experian’s Vision Conference held in Miami, Fla. Figure, PREMIER Bankcard and Members First Credit Union were recognized for their work in artificial intelligence, innovation and financial empowerment. The four-day gathering provided a dynamic forum for exploring the latest innovations shaping the future of data-driven decisioning. “Our Vision Awards celebrate the unique impact financial industry leaders can have when data, technology and purpose align,” said Jeff Softley, CEO, Experian North America. “We are proud to recognize these three organizations with whom we collaborate to drive opportunities and help create change for society as a whole.” The Vision Awards recognize the achievements of organizations that accelerate action. These forward-thinking institutions leverage artificial intelligence, innovation and financial empowerment to drive opportunities and create actionable change for consumers, businesses and society. Recognizing Leaders in AI, Innovation, and Financial Empowerment A panel of interdisciplinary judges reviewed nominations from across industries across the regions, evaluating submissions based on rigor, originality, and impact. The 2025 winners reflect how organizations are leveraging data and technology to advance innovation and inclusion. Excellence in AI: Figure Figure’s submission showcased how it has redefined consumer lending outreach through an AI-driven targeting engine powered by more than 90 machine learning models and 5,000+ behavioral and financial features. By combining Experian’s prescreen data with proprietary insights, Figure delivers highly precise, cost-efficient firm offers of credit — helping it become one of the top three home equity line of credit lenders in the U.S. “This win reflects more than just a successful application of AI. It represents the broader innovative culture deeply embedded in our company’s DNA,” said Ruben Padron, Chief Data Officer at Figure. “Our work with Experian has been instrumental in helping us assess creditworthiness and predict borrower intent with greater precision.” Excellence in Innovation: PREMIER Bankcard PREMIER Bankcard continues to demonstrate how financial inclusion and innovation go hand in hand. From modernizing its technology to reimagining its product suite, PREMIER has made bold strides to serve the underserved and democratize access to credit. “This award affirms our belief that financial inclusion and innovation must go hand in hand,” said Chris Thornton, Senior Vice President of Credit at PREMIER Bankcard. “We’re committed to reaching those who need it most, and Experian has proven to be an exceptional partner in that mission.” With more than 30 million customers served, PREMIER has become a leader in first-time and second-chance credit, while also giving back more than $4 billion to charitable causes through its partnership with First PREMIER Bank and founder Denny Sanford. “We’re here to change lives,” Thornton added. “That’s how we measure success — and that’s ultimately what we’re investing in.” Excellence in Financial Empowerment: Members First Credit Union Members First Credit Union was honored for its commitment to inclusive lending and community development across Michigan. In 2024 alone, the credit union’s programs helped thousands of members access fair and affordable credit, supported 166 community organizations, and contributed nearly $230,000 in donations — backed by 2,000 volunteer hours from its employees. “Our impact demonstrates how mission-driven financial institutions can meaningfully expand access, strengthen communities, and foster long-term financial health,” said Carrie Iafrate, CEO/President at Members First Credit Union. “We’re honored to receive this recognition and inspired to continue helping individuals thrive financially.” Honoring the Judges Behind the Vision The 2025 Vision Awards were evaluated by a distinguished panel of judges representing both Experian and external associations and partners in the financial inclusion community, including: Lisa Cantu-Parks, Vice President of Resource Development, Unidos Jean Carlos Rosario Mercado, Juntos Avanzamos Program Officer, Inclusiv Ian P. Moloney, Senior Vice President, Head of Policy and Regulatory Affairs, American Fintech Council Marc Morial, President and CEO, National Urban League Kevin O’Connor, Senior Vice President, Membership and Sponsorship, Consumer Bankers Association Their expertise ensured that the winners reflect the industry’s highest standards of innovation, integrity, and impact. Ian P. Moloney, Senior Vice President, Head of Policy and Regulatory Affairs, American Fintech Council, and Rhonda Spears Bell, Senior Vice President and Chief Marketing Officer, National Urban League, were at the recognition session at Vision and shared about their organizations and experience serving as a judge. Video messages were also shared from Jean Carlos Rosario Mercado of Inclusiv and Kevin O’Connor of Consumer Bankers Association, who were unable to attend the live event. “I greatly appreciated the opportunity to participate as a judge in the Experian Vision Awards because it provided me a chance to look beyond my usual day-to-day, and understand the myriad of innovations and projects going on to help consumers and the industry,” Moloney said. “The award winners tonight showcase the best of our industry, and I appreciate the opportunity to take part in highlighting their success.” “I’m inspired by the outstanding organizations we’re celebrating tonight - each making a lasting impact in our country and globally,” Spears Bell said. “I want to take a moment to recognize Experian - not only as a valued corporate partner, but as a true ally in our mission to advance financial literacy, stability, and generational wealth.” Looking Ahead: Vision Awards 2026 Experian will continue to champion progress in financial services and across all industries, and the Vision Awards offers one of the avenues through which the industry can recognize organizations driving change through responsible innovation. Submissions for the 2026 Vision Awards open on June 1, 2026. To learn more about this year’s winners and how to apply for next year’s program, visit the Vision Awards page.
Day 1 of Vision 2025 is in the books – and what a start. From bold keynotes to breakout sessions and networking under the Miami sun, the energy and inspiration were undeniable. A wave of change: Jeff Softley opens Vision 2025 The day kicked off with a powerful keynote from Jeff Softley, Experian North America CEO, who issued a call to action for the industry: to not just adapt to change, but to lead it. “It isn’t a ripple – it’s a tidal wave of technology,” Jeff said. “Together we ride this wave with confidence.” His keynote set the tone for a day centered on innovation and the future of financial services – where technology, insight and trust converge to create lasting impact. Jeff continues this conversation in the latest Experian Exchange episode, where he explores three forces shaping the industry: the rise of AI, the demand for personalized digital experiences and the mission to expand credit access for all. Turning vision into action: Alex Lintner on agentic AI Building on Jeff’s message, Alex Lintner, CEO of Experian Software and Technology, took the stage to show how Experian is turning innovation into measurable results. His keynote explored how agentic and advanced AI capabilities are redefining financial services ROI and powering the next generation of the Ascend Platform™. For a deeper look into how Experian is reshaping the economics of credit and fraud decisioning, read the latest American Banker feature. Unfiltered insights from “Mr. Wonderful” The day’s highlight came from Kevin O’Leary, investor, entrepreneur and the always-candid “Mr. Wonderful.” With his trademark wit and honesty, Kevin shared sharp insights on thriving in a disruptive economy, offering candid advice on leadership, risk and opportunity. He even gave attendees a peek behind the Shark Tank curtain, revealing a few surprises and the mindset that drives his bold business decisions. Breakouts that inspired and informed The conference floor buzzed with energy as attendees joined breakout sessions on fraud defense, AI-driven personalization, regulatory trends and consumer insights. Sessions highlighted how Experian’s unified value proposition is fueling double-digit growth, how to future-proof credit risk strategies and how data and innovation are redefining customer engagement across the lifecycle. Hands-on innovation and connection The Innovation Showcase gave attendees an up-close look at Experian’s latest tools and technologies in action. Meanwhile, friendly competition kept the excitement high through the Vision mobile app leaderboard – with every check-in and connection earning points toward the top spot. Networking beyond the conference hall walls As the sun set, Vision 2025 shifted into high gear with unforgettable networking events across Miami – from golf at the Miller Course to art walks, brewery tours and a scenic cruise through Biscayne Bay. An evening to remember The day closed with the first-ever Vision Awards Dinner, celebrating standout leaders who are shaping the future of financial services. Up Next: Day 2 The momentum continues tomorrow as more keynote speakers take the stage. Stay tuned for more insights, innovation, and inspiration from Vision 2025.
Tenant screening fraud is rising, with falsified paystubs and AI-generated documents driving risk. Learn how income and employment verification tools powered by observed data improve fraud detection, reduce costs, and streamline tenant screening.