#ExperianVision 2018 Day 1 Recap

by Kerry Rivera 3 min read May 21, 2018

Alternative credit data. Enhanced digital credit marketing. Faster, integrated decisioning. Fraud and identity protections. The latest in technology innovation.

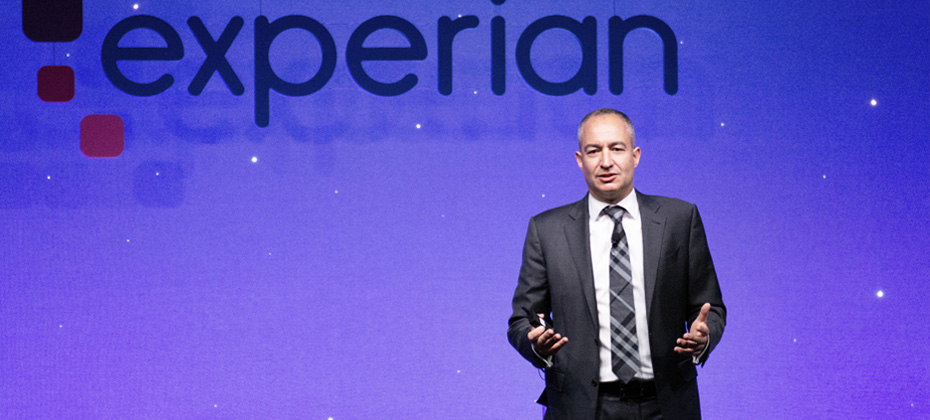
These were the themes Craig Boundy, Experian’s CEO of North America, imparted to an audience of 800-plus Vision guests on Monday morning.

“Technology, innovation and new sources of data are fusing to create an unprecedented number of new ways to solve pressing business challenges,” said Boundy. “We’re leveraging the power of data to help people and businesses thrive in the digital economy.”

Main stage product demos took the shape of dark web scans, data visualization, and the latest in biometric fraud scanning. Additionally, a diverse group of breakout sessions showcased all-new technology solutions and telling stats about how the economy is faring in 2018, as well as consumer credit trends and preferences.

A few interesting storylines of the day …

Regulatory

Under the Trump administration, everyone is talking about deregulation, but how far will the pendulum swing? Experian Sr. Director of Regulatory Affairs Liz Oesterle told audience members that Congress will likely pass a bill within the next few days, offering relief to small and mid-sized banks and credit unions. Under the new regulations, these smaller players will no longer have to hold as much capital to cover losses on their balance sheets, nor will they be required to have plans in place to be safely dismantled if they fail. That trigger, now set at $50 billion in assets, is expected to rise to $250 billion.

Fraud

Alex Lintner, Experian’s President of Consumer Information Services, reported there were 16.7 million identity theft victims in 2017, resulting in $16.8 billion in losses. Need more to fear? There is also a reported 323k new malware samples found each day. Multiple sessions touched on evolving best practices in authentication, which are quickly shifting to biometrics-based solutions. Personal identifiable information (PII) must be strengthened. Driver’s licenses, social security numbers, date of birth – these formats are no longer enough. Get ready for eye scans, as well as voice and photo recognition.

Emerging Consumers

The quest to understand the up-and-coming Millennials continues. Several noteworthy stats:

  • 42% of Millennials said they would conduct more online transactions if there weren’t so many security hurdles to overcome. So, while businesses and lenders are trying to do more to authenticate and strengthen security, it’s a delicate balance for Millennials who still expect an easy and turnkey customer experience.
  • Gen Z, also known as Centennials, are now the largest generation with 28% of the population. While they are just coming onto the credit scene, these digital natives will shape the credit scene for decades to come. More than ever, think mobile-first.
  • And consider this … it’s estimated that 25% of shopping malls will be closed within five years. Gen Z isn’t shopping the mall scene. Retail is changing rapidly!

Economy

Mortgage originations are trending up. Consumer confidence, investor confidence, interest rates and home sales are all positive. Unemployment remains low. Bankcard originations have now surpassed the 2007 peak. Experian’s Vice President of Analytics Michele Raneri had glowing remarks on the U.S. economy, with all signs pointing to a positive 2018 across the board. Small business loan volumes are also up 10% year-to-date versus the same time last year. Keynote presenters speculate there could be three to four rate hikes within the year, but after years of no hikes, it’s time.

Data

There are 2.5 quintillion pieces of data created daily. And 80% of what we know about a consumer today is the result of data generated within the past year. While there is no denying there is a LOT of data, presenters throughout the day talked about the importance of access and speed. Value comes with more APIs to seamlessly connect, as well as data visualization solutions like Tableau to make the data easier to understand.

More Vision news to come. Gain insights and news throughout the day by following #ExperianVision on Twitter.


Related Posts

How GenAI Fraud Bots Fly Under the Radar (and How to Ground Them Before It’s Too Late)

Today’s AI-powered fraud bots are exceptionally good at mimicking human behavior. Learn why a modern defense strategy is key.

November 18, 2026 by Laura Burrows
What Is Incident Response? Key Steps, Planning and Best Practices

Learn what incident response is, the key steps in the process and how to build and test an incident response plan for a data breach.

November 17, 2026 by Laura Burrows
Rethinking Charged-Off Portfolio Prioritization

Experian’s new Recovery Scores model turns portfolio intelligence into more focused recovery strategies, helping organizations improve returns, direct effort and accelerate speed to cash. The challenge isn’t simply working more accounts. Whether a debt buyer is evaluating an acquisition, an agency is deciding where to assign collector time or a lender is managing its own post-charge-off accounts, the question is similar: How can limited capacity be directed toward accounts with the greatest potential for recovery? Prioritizing accounts mainly by age, balance or when they were last worked may not show which ones are most likely to generate a recovery. With the new Recovery Scores model, organizations can rank charged-off accounts by expected collectability, providing a consistent signal to inform placement strategy and treatment decisions across the recovery lifecycle. Make collector capacity a strategic resource Working every account with the same level of attention isn’t always practical. The more useful question is: Where should teams focus first to protect speed to cash? Our model performance analysis found: 80% of recovered dollars come from the top 40% of accounts worked. The value isn’t simply a better ranking. It’s how organizations can use it for collections optimization. Score bands can inform different strategies for placement, outsourcing, auction and legal channel treatment rather than applying the same approach across an entire portfolio. For debt buyers: The scores can inform acquisition pricing and how a newly purchased portfolio is divided across internal collections, legal channels and resale. Expected collectability can shape debt portfolio analysis, including how a portfolio is valued and segmented before collection work begins. For agencies: Score bands can help teams focus collector resources on accounts with stronger recovery potential. For first-party lenders: Managing recovery internally, the scores provide another signal to help structure decisions about which accounts to work and in what order. Look beyond collectability alone Prioritization rarely comes down to a single variable. Consider two accounts that both rank highly for expected collectability, but one has a substantially larger balance. Their recovery likelihood may be similar, but the potential dollars recovered are not. The Recovery Scores model uses debt collections analytics by combining Experian’s bureau-based score with current balance information. This helps organizations consider both the likelihood of recovery and the potential dollars at stake, while sensitive balance information remains within the organization’s working environment. Monitor accounts as they change The first decision about an account is rarely the last. Teams continually make choices about treatment, placement and resource allocation as accounts move through the recovery process. Recovery Scores is also available as a trigger. When underlying information changes, teams can receive an update and reconsider an account’s placement without waiting for the next portfolio-wide re-score. An account that shows lower recovery potential today may have a different recovery outlook later. Turn recovery potential into a portfolio strategy When portfolios contain more accounts than teams can work at once, the question isn’t simply, “How many accounts can we work?” It is, “Where can our resources have the greatest impact?” The latest Recovery Scores model helps organizations sharpen placement and treatment decisions. It gives debt buyers a way to price and segment portfolios with greater confidence and gives lenders another tool to direct limited collector time across their own post-charge-off portfolios. Learn more about Experian Recovery Scores

November 10, 2026 by Zohreen Ismail

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe
