Financial Services

Effective fraud prevention is critical to balancing security and customer experience during onboarding. Learn more!
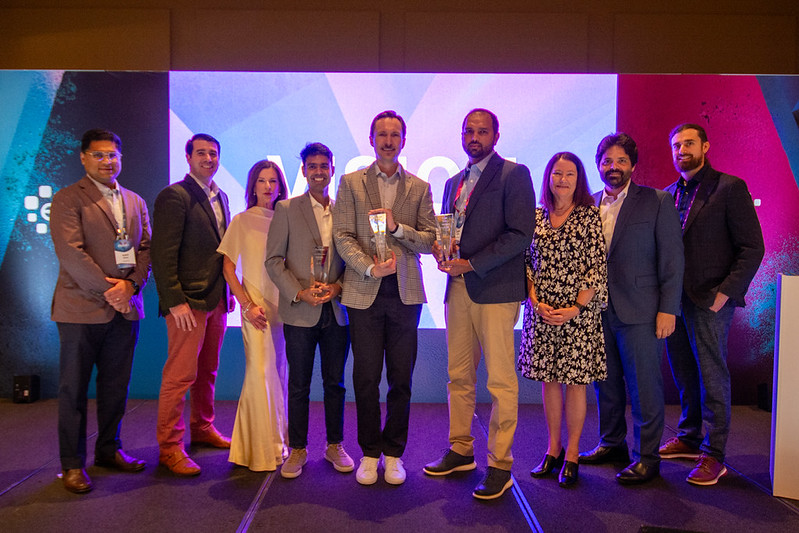
Four organizations show what’s possible when data, analytics, AI and technology are put to work against real business and consumer challenges.
Leaders from across the industry came together to explore the technologies, strategies and opportunities shaping what’s next.
Our Data Breach Response Guide provides guidance to help your organization prepare, respond and recover while protecting your customers.
AI, digital doppelgängers and growing consumer skepticism could reshape the data breach landscape in 2027. Here’s what to prepare for.
AI agents are changing the way consumers interact with businesses online. Learn how you can establish greater confidence in AI transactions.
Explore five common scam schemes, the signals to watch for and how fraud teams can enhance scam detection.
Discover how the National Urban League and Experian partner to expand financial literacy and create economic opportunity.
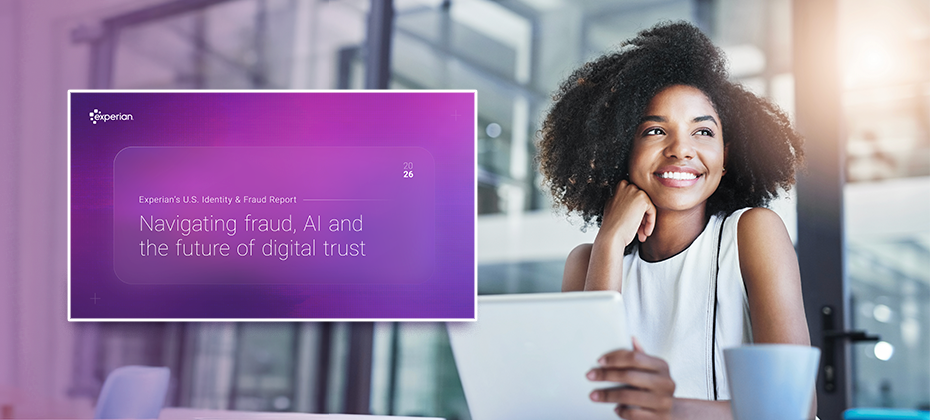
Explore key findings and insights from our newly released 2026 U.S. Identity and Fraud Report. Read more now!
Learn how ChexSystems and Experian help financial institutions strengthen consumer fraud monitoring and build customer trust.
ValidMind CEO Jonas Jacobi shares insights on AI, innovation and why Experian's partnership is helping shape the future of responsible AI.
Due to new federal student loan regulations, the families of undergrad and graduate students may look to private lenders to fill the gap.
Learn what agentic commerce is, why AI agents are transforming digital commerce and how Agent Trust builds trusted AI interactions.
Consumer visibility is changing Roughly 45 million Americans, or 1 in 5 consumers, are considered credit invisible or unscoreable.[1] They’re working, paying bills and participating in the economy, yet many are not fully visible during the lending process. That creates both a visibility challenge and a growth opportunity for lenders. In this Ask the Expert session, Corliss Hill, Senior Director, Inclusion and Belonging at Experian, joins Dr. Vaneesha Dutra, Endowed Professor of Finance at Morehouse College, to discuss how evolving consumer behaviors are reshaping conversations around financial inclusion and lending decisions. For lenders, visibility matters because confident decisions depend on reliable context and insight. Broader consumer signals can help institutions better understand repayment behaviors, financial stability and consumer capacity. “The benefit of banks using alternative data is that they capture a very significant and new consumer base. That's 20% of the population, 45 million Americans.”Dr. Vaneesha Dutra, Endowed Professor of Finance A more complete understanding of today’s consumers Today’s consumers often manage obligations across a wide range of payment types and financial channels, creating additional signals through cash flow activity, recurring payments and consumer-permissioned financial data. Rent, utilities, subscriptions and mobile phone payments can all provide meaningful insight into how consumers manage their financial lives. What’s changing isn’t the need for risk assessment. It’s the amount of consumer behavior lenders can now evaluate. For example, a consumer experiencing temporary financial disruption may fall behind on certain obligations while continuing to consistently pay rent, utilities and phone bills. Those recurring payment behaviors can provide important context into financial priorities and stability. “These are consumers that pay rent on time every month, pay utilities every month on time and meet many other financial obligations in a timely manner.”Dr. Vaneesha Dutra, Endowed Professor of Finance From visibility to more-informed decisioning Broader consumer insights may help lenders move from limited visibility to more informed decisioning. The conversation shifts when lenders move from asking: “Should we take a risk on this consumer?” to: “Do we have enough information to fully understand this consumer?” That broader context can help institutions: Strengthen risk assessment. Identify financially active consumers with strong repayment behaviors. Support more informed lending strategies. Alternative data isn’t about replacing established credit approaches. It’s about helping lenders build on trusted credit foundations with additional context and insight. Responsible lending starts with better context For lenders, the path forward is practical and actionable. As lenders evaluate broader consumer behaviors, three priorities become increasingly important: Modernize data strategies Incorporate broader consumer signals alongside existing credit data to create a more holistic view of repayment behavior and financial stability. Engage consumers earlier Earlier intervention may help lenders better support consumers before financial challenges become more severe. Create pathways to financial access Smaller lending opportunities can help consumers establish stronger financial profiles and demonstrate positive repayment behaviors over time. The institutions that lead will be the ones that can combine strong risk practices with a broader understanding of consumer behavior. Whitepaper: Bridging the credit divide: income, risk and inclusion in consumer finance Building on the themes discussed in this Ask the Expert session, Dr. Dutra explores how demographic shifts, evolving borrower behaviors and broader consumer visibility are reshaping lending strategies and what they mean for lenders seeking to balance growth, risk management and financial inclusion. Download whitepaper Explore alternative data with Experian Experian can help lenders combine broader consumer insights with trusted credit data to strengthen decisioning, improve risk assessment and support more-informed lending strategies. With solutions spanning identity, cash flow and advanced analytics, lenders can gain a more complete view of consumer behavior and expand access to credit with greater confidence. Learn more Watch episode 1 About our experts Corliss Hill Senior Director, Belonging Business Partner, Experian Corliss Hill is a collaborative leader well-versed in working with executive stakeholders, crossfunctional teams, external partners and community organizations to design and deliver initiatives and programs that create sustainable impact. With over 25 years of extensive experience in multicultural marketing, communications, PR and inclusion and belonging initiatives, she is dedicated to advancing equitable access to financial. Her mission is to drive impactful marketing initiatives that foster meaningful change and address systemic barriers to inclusion and the communities they serve.Hill has been a part of the Experian family since 2021, and resides in Atlanta with her daughter who is a rising 11-year-old entrepreneur. Vaneesha Dutra, Ph.D. Endowed Professor of Finance and Associate Dean, Morehouse College Vaneesha Dutra, Ph.D., serves as Associate Dean in the Division of Business and Economics. With more than 20 years of experience spanning higher education, banking and real estate, Dr. Dutra’s work focuses on the racial and gender wealth gap, financial literacy and financial decision-making. She is an active researcher and consultant whose work has earned numerous grants and fellowships, including serving as the inaugural Tracy A. Pruitt Visiting Research Faculty Fellow at the Wharton School of Business. Dr. Dutra has also been named a Research Faculty Fellow for both the Center for Black Entrepreneurship and the PNC Bank Center for Entrepreneurship. [1] Consumer Financial Protection Bureau, Expanding access to credit.
Learn how PREMIER Bankcard and Experian are helping expand financial access through data, technology and personalized decisioning.