Four organizations show what’s possible when data, analytics, AI and technology are put to work against real business and consumer challenges.
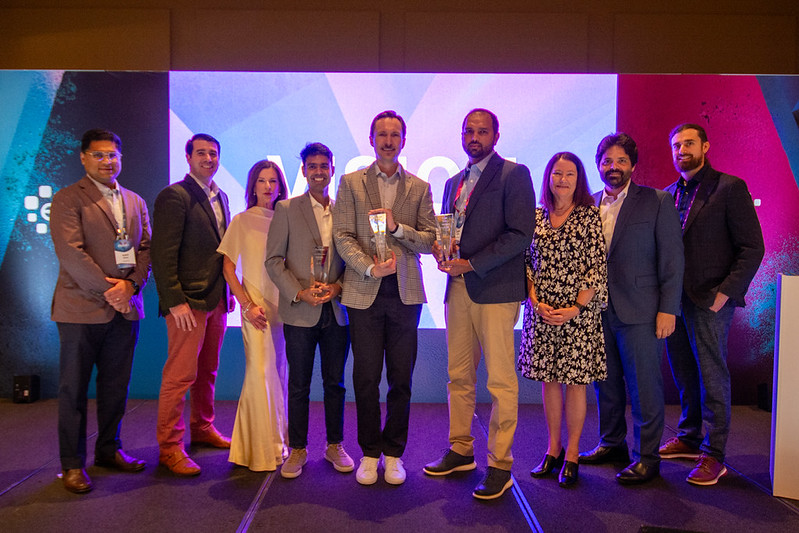
At Experian Vision 2026 in San Antonio, more than 700 senior leaders, data scientists and decision-makers came together to explore the technologies and ideas shaping the future. One of the highlights was recognizing four organizations that are already putting those ideas into action: Best Egg, Credit One Bank, Fundbox and Valley First Credit Union, the recipients of the 2026 Experian Vision Awards.
Selected by an independent panel of judges, this year’s winners were evaluated on demonstrated results, creativity, scalability and industry impact.
The room was filled with music from a live violinist and saxophonist, glimmering table adornments, and lots of excitement ahead of an evening of recognition and connection.
Four approaches to turning innovation into measurable outcomes
Although this year’s winners tackled very different challenges, their stories share an important theme: data and technology create the most value when they are connected to a clearly defined business or consumer need.
Here’s how each organization brought that principle to life.
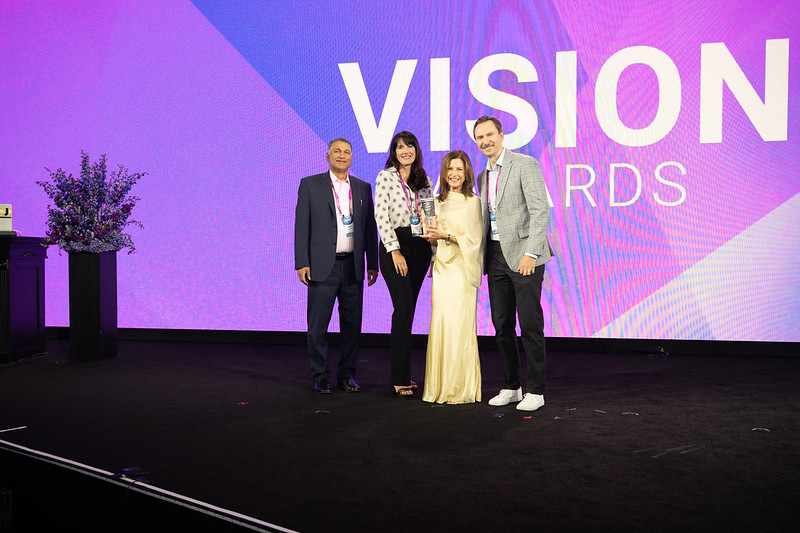
Credit One Bank: Excellence in Analytics
Advancing Underwriting through analytics
Credit One Bank rebuilt its custom underwriting model using Experian data and advanced machine learning techniques within the Experian Ascend Sandbox™. The enhanced model delivered nearly a 50% improvement in Kolmogorov-Smirnov score performance, strengthening underwriting precision and risk assessment capabilities. Credit One Bank expects the new approach will enable it to increase credit card offers by approximately 15% while maintaining current loss rates.
The results illustrate an increasingly important opportunity for lenders: improving risk assessment doesn’t necessarily have to mean choosing between portfolio performance and expanding access. Sophisticated analytics can help organizations identify opportunities that traditional approaches may miss while maintaining disciplined risk management.
Fundbox: Excellence in AI
Putting AI to work for small businesses
For small businesses, the time between applying for capital and receiving a decision can matter. Fundbox addressed that challenge with an AI-driven underwriting approach designed to enable platforms to embed access to capital into the experiences they provide to small businesses.
Its AI-powered underwriting engine combines banking, accounting and payment activity with Experian consumer and commercial credit data to evaluate businesses using real-time operating signals.
The result: credit decisions in less than 60 seconds, with 98% of applications requiring no human review. Since January 2024, the solution has approved more than 50,000 new customers and supported approximately $2 billion in originations.
Fundbox’s story offers a useful example of AI moving beyond experimentation and into operational workflows. Here, automation reduced friction, accelerated decisions and helped partners deliver access to capital within the experiences small businesses already use.
Valley First Credit Union: Excellence in Financial Empowerent
Expanding financial opportunity at the community level
Valley First Credit Union demonstrates what innovation can look like when financial institutions combine products, partnerships, education and community engagement to expand financial opportunity.
More than 70% of its lending is directed to low- and moderate-income communities across California’s Central Valley. In 2025, the credit union provided $239,000 in microloans, $390,000 in SBA commercial lending, $660,000 through the Modesto Loan Fund and $32,000 in first-time homebuyer assistance grants. Its financial education, counseling and free resources reached more than 4,200 community members and helped nearly 12,900 members improve their credit scores and strengthen their financial futures.
The work how both technology and data and partnerships and education are important elements for innovation and empowerment.
Best Egg: Excellence in Innovation
Innovating across fraud prevention and customer acquisition
Best Egg received the Excellence in Innovation award for two initiatives focused on fraud prevention and personalized offer experiences.
The company developed an adaptive fraud-prevention ecosystem combining Experian data with additional identity and risk signals. From July 2025 to date, the program reduced fraud losses and identified and prevented a significant amount of application volume associated with suspected fraudulent activity, while limiting additional friction for legitimate customers.
At the same time, Best Egg built a real-time personalized offer experience on top of its traditional prescreen process. The approach generated a 17% lift in application submissions, a 35% relative lift in application approval rate and a 32% relative lift in offer acceptance. Expansion to additional loan products also increased the number of customers eligible to receive a personalized offer by 37.5%.
Celebrating what’s possible – and what’s next
The Experian Vision Awards recognize organizations using data, analytics, software and financial empowerment initiatives to create measurable impact for consumers, businesses and communities.
This year’s winners show that meaningful innovation can take many forms. It can mean making a credit decision in seconds. Detecting fraud before it creates a loss. Finding new ways to responsibly extend credit. Or creating programs that help more people participate in the financial system.
What connects those efforts is the ability to turn ideas into action—and action into measurable impact.
Members from Credit One Bank received the Excellence in Analytics Award at Vision 2026.
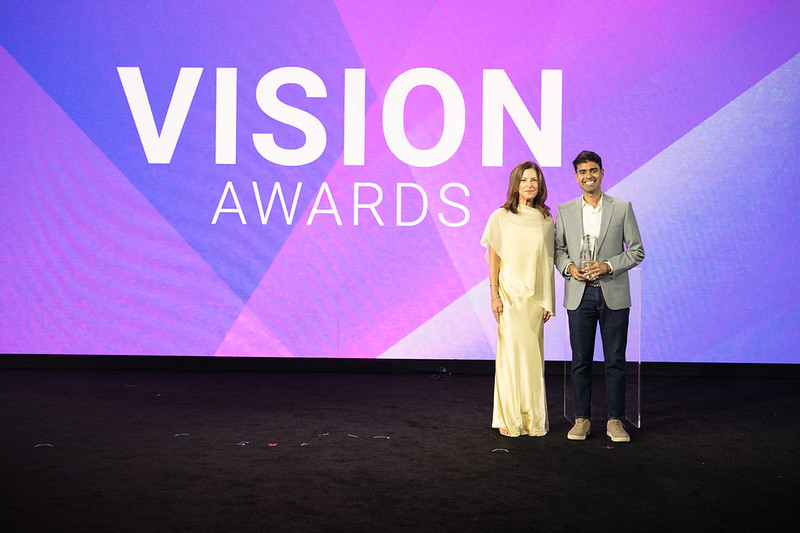
Fundbox received the Excellence in AI Award at Vision 2026.
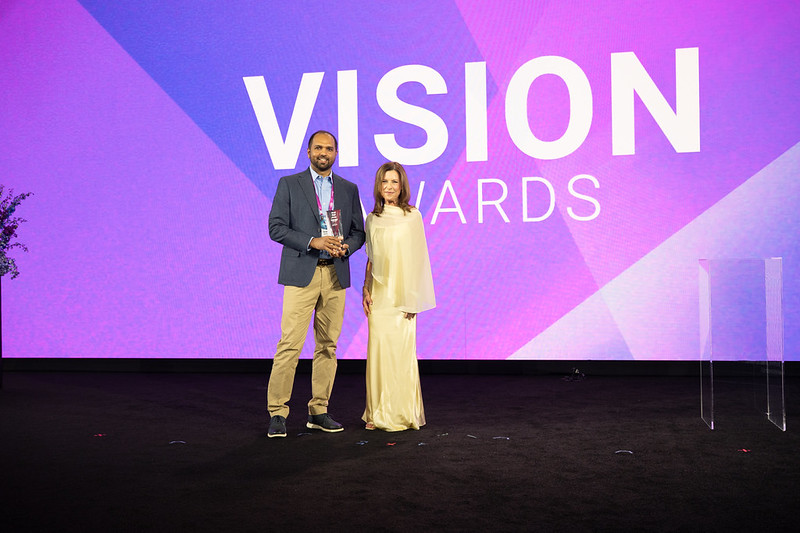
Best Egg received the Excellence in Innovation Award at Vision 2026.
Congratulations to Best Egg, Credit One Bank, Fundbox and Valley First Credit Union on their 2026 Experian Vision Awards.
The average credit union manages between 100-300 vendor relationships, and nearly a third have no dedicated staff managing them. What was supposed to drive efficiency is stunting growth and compromising the member experience.
Application volume is continuing to rise, and consumers expect a loan decision at digital speed. But for credit unions, meeting that expectation isn't the only goal. They must also continue to make the right lending decisions while also prioritizing risk management.
The institutions pulling ahead aren't the ones with the most tools. They're the ones that have turned credit, fraud and decisioning into a single, coordinated system.
A single loan decision touches:
Credit data
Identity verification
Fraud signals
Decisioning logic
Reporting
Rarely does all of that live in one place. More often, it’s stitched together across separate platforms, each with its own contract and its own support line.
When a credit view and a fraud view are generated separately, they must be reconciled instead of read together in the same instant. Every handoff is a place where a decision slows down and a signal gets missed. It's why a fraud pattern that would be obvious next to the credit file often surfaces only after the funds are already gone.
Fragmentation also makes it harder to optimize lending strategies over time. When data, analytics and decisioning are disconnected, credit unions have less visibility into what's working, what's changing and where strategies need to be adjusted.
An integrated decisioning ecosystem closes those seams by design, with credit, fraud and lending strategy running on one platform and accessed through a single Application Programming Interface (API). Identity and compliance capabilities can be an integrated decisioning flow. The data doesn't need to be reconciled after the fact because it was never separated in the first place.
Stop overengineering, start removing friction
When decisioning underperforms, the instinct is to build something more custom: a proprietary model, tighter segmentation, more configuration.
Custom modeling has its place for institutions with the scale and data to justify it. But often, for small or mid-sized credit unions, the bigger opportunity is a flexible decisioning strategy that uses a strong, continuously refreshed model. This shouldn't be either/or. The right approach gives credit unions a strong decisioning strategy today, with the ability to introduce more customized analytics and modeling as their needs evolve.
The same principle applies to strategy management: credit unions can gain greater control through self-service capabilities as they build a more sophisticated data science team.
That kind of flexibility is important as credit unions modernize their decisioning infrastructure. Research surveying more than 2,000 senior credit risk and fraud decision-makers across 11 countries found that organizations investing in unified platforms and modern infrastructure are moving faster and realizing the greatest Return on Investment (ROI).
As their needs evolve, credit unions can adjust decisioning strategies without introducing another layer of technology or relying on third parties to make every change. Until self-service is the right fit, choose a partner that understands what makes your credit union’s membership and risk appetite different from others.
Same member, same afternoon, faster answer
Consider a credit union growing its auto and personal loan originations.
A member applies for an auto loan on Saturday afternoon. Credit data, identity and fraud signals are read together in a single real-time pass instead of separate reviews:
Most applications resolve immediately, approved or declined based on a more comprehensive view of the applicant.
A smaller number are flagged for quick step-up verification and cleared within minutes.
Only genuinely ambiguous cases reach an underwriter, who is working from one complete picture instead of reconciling multiple signals.
The member has an answer before the weekend is over. The credit union books the loan before competitors even open on Monday.
Built to scale
This kind of process holds up today. However, the better test is whether it holds up eighteen months from now when application volume has grown, new products are live and the data flowing through the system looks nothing like it does right now.
Future-proofing isn't only about handling more volume. It's about having room to be nimbler and make adjustments as quickly as the market changes. A credit union that relies on standard models within a decisioning strategy may want more customized analytics and greater control over its strategies tomorrow.
Connect with us
With more than three decades of credit expertise and one of the industry's largest data footprints, Experian helps credit unions do more than solve this year's friction. We're helping to build a decisioning foundation that scales, so growth becomes something the system absorbs, rather than something it must be rebuilt around.
Explore More