Chipping Away at EMV Myths

by Keir Breitenfeld 3 min read November 16, 2015

What the EMV Shift means for you

I recently facilitated a Webinar looking at myths and truths in the market regarding the EMV liability shift and what it means for both merchants and issuers. I found it to be a very beneficial discussion and wanted to take some time to share some highlights from our panel with all of you. Of course, if you prefer to hear it firsthand, you can download the archive recording here.

Myth #1: Oct. 1 will change everything

Similar to the hype we heard prior to Y2K, Oct. 1, 2015, came and went without too much fanfare. The date was only the first step in our long and gradual path to EMV adoption. This complex, fragmented U.S. migration includes:

  • More than 1 billion payment cards
  • More than 12 million POS terminals
  • Four credit card networks
  • Eighteen debit networks
  • More than 12,000 financial institutions

Unlike the shift in the United Kingdom, the U.S. migration does not have government backing and support. This causes additional fragmentation and complexity that we, as the payments industry, are forced to navigate ourselves.

Aite Group predicts that by the end of 2015, 70 percent of U.S. credit cards will have EMV capabilities and 40 percent of debit cards will be upgraded.
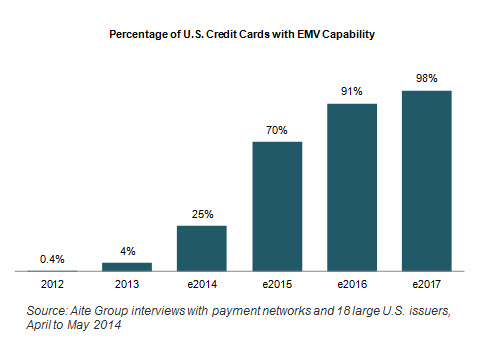
EMV Shift - US EMV Cards

So while Oct. 1 may not have changed everything, it was the start of a long and gradual migration.

Myth #2: Subscription revenues will plummet due to reissuances

According to Aite, EMV reissuance is less impactful to merchant revenues than database breaches, since many EMV cards are being reissued with the same pan. The impact of EMV on reoccurring transactions is exaggerated in the market, especially when you look at the Update Issuer provided by the transaction networks.

There still will be an impact on merchants, coming right at the start of the holiday shopping season. The need for consumer education will fall primarily on merchants, given longer lines at checkout and unfamiliar processes for consumers. Merchants should be prepared for charge-back amounts on their statements, which they aren’t used to seeing. Lastly, with a disparate credit and debit user experience, training is needed not just for consumers, but also for frontline cashiers.

We do expect to see some merchants decide to wait until after the first of the year to avoid impacting the customer experience during the critical holiday shopping season, preferring to absorb the fraud in the interest of maximizing consumer throughout.

Myth #3: Card fraud will decline dramatically

We can look to countries that already have migrated to see that card fraud will not, as a whole, decline dramatically.

While EMV is very effective at bringing down counterfeit card fraud, organized crime rings will not sit idly by while their $3 billion business disappears. With the Canadian shift, we saw a decrease in counterfeit card loss but a substantial increase in Card Not Present (CNP) fraud.

In Canada and Australia, we also saw a dramatic, threefold increase in fraudulent applications. When criminals can no longer get counterfeit cards, they use synthetic and stolen identities to gain access to new, legitimate cards.
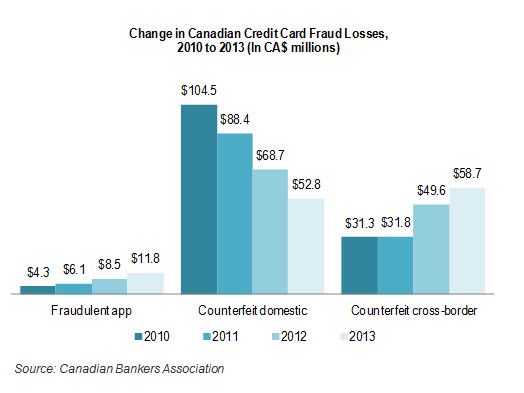
EMV shift - Canada Fraud Loss

In the United States, we should plan for increased account-takeover attacks, i.e., criminals using compromised credentials for fraudulent CNP purchases. For merchants that don’t require CVV2, compromised data from recent breaches can be used easily in an online environment.

According to Aite, issuers already are reporting an increase in CNP fraud. Fraudsters did not wait until the Oct. 1 shift to adjust their practices.

Myth #4: All liability moves to the issuer

EMV won’t help online merchants at all. Fraud will shift to the CNP channel, and merchants will be completely responsible for the fraud that occurs there.

We put together a matrix to illustrate where actual liability shifts and where it does not.

Payments liability matrix
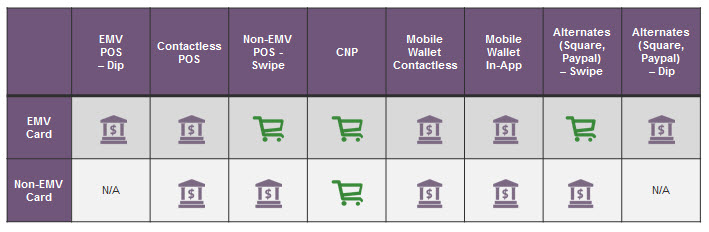
EMV shift - EMV Liability

Note: Because of the cost and complexity of replacing POS machines, gas stations are not liable until October 2017.

For more information, or if you’d like to hear the full discussion, click here to view the archive recording, which includes a great panel question-and-answer session.


Related Posts

Building for Bots in the AI Age: Separating Legitimate Agents From Fraudsters

See how NeuroID helps businesses distinguish legitimate AI agents from fraud bots, while Agent Trust verifies agent-initiated transactions.

October 29, 2026 by Laura Burrows
2026 Retail Banking Identity and Fraud Report 

Learn how banks can convert rising fraud investment into protection customers recognize, value and feel in our recent report. Read more!

October 28, 2026 by Laura Burrows
One Platform, Fewer Handoffs, Faster Decisions

The average credit union manages between 100-300 vendor relationships, and nearly a third have no dedicated staff managing them. What was supposed to drive efficiency is stunting growth and compromising the member experience. Application volume is continuing to rise, and consumers expect a loan decision at digital speed. But for credit unions, meeting that expectation isn't the only goal. They must also continue to make the right lending decisions while also prioritizing risk management. The institutions pulling ahead aren't the ones with the most tools. They're the ones that have turned credit, fraud and decisioning into a single, coordinated system. A single loan decision touches: Credit data Identity verification Fraud signals Decisioning logic Reporting Rarely does all of that live in one place. More often, it’s stitched together across separate platforms, each with its own contract and its own support line. When a credit view and a fraud view are generated separately, they must be reconciled instead of read together in the same instant. Every handoff is a place where a decision slows down and a signal gets missed. It's why a fraud pattern that would be obvious next to the credit file often surfaces only after the funds are already gone. Fragmentation also makes it harder to optimize lending strategies over time. When data, analytics and decisioning are disconnected, credit unions have less visibility into what's working, what's changing and where strategies need to be adjusted. An integrated decisioning ecosystem closes those seams by design, with credit, fraud and lending strategy running on one platform and accessed through a single Application Programming Interface (API). Identity and compliance capabilities can be an integrated decisioning flow. The data doesn't need to be reconciled after the fact because it was never separated in the first place. Stop overengineering, start removing friction When decisioning underperforms, the instinct is to build something more custom: a proprietary model, tighter segmentation, more configuration.  Custom modeling has its place for institutions with the scale and data to justify it. But often, for small or mid-sized credit unions, the bigger opportunity is a flexible decisioning strategy that uses a strong, continuously refreshed model. This shouldn't be either/or. The right approach gives credit unions a strong decisioning strategy today, with the ability to introduce more customized analytics and modeling as their needs evolve.  The same principle applies to strategy management: credit unions can gain greater control through self-service capabilities as they build a more sophisticated data science team.   That kind of flexibility is important as credit unions modernize their decisioning infrastructure. Research surveying more than 2,000 senior credit risk and fraud decision-makers across 11 countries found that organizations investing in unified platforms and modern infrastructure are moving faster and realizing the greatest Return on Investment (ROI).   As their needs evolve, credit unions can adjust decisioning strategies without introducing another layer of technology or relying on third parties to make every change. Until self-service is the right fit, choose a partner that understands what makes your credit union’s membership and risk appetite different from others.  Same member, same afternoon, faster answer Consider a credit union growing its auto and personal loan originations.  A member applies for an auto loan on Saturday afternoon. Credit data, identity and fraud signals are read together in a single real-time pass instead of separate reviews:  Most applications resolve immediately, approved or declined based on a more comprehensive view of the applicant. A smaller number are flagged for quick step-up verification and cleared within minutes. Only genuinely ambiguous cases reach an underwriter, who is working from one complete picture instead of reconciling multiple signals. The member has an answer before the weekend is over. The credit union books the loan before competitors even open on Monday. Built to scale This kind of process holds up today. However, the better test is whether it holds up eighteen months from now when application volume has grown, new products are live and the data flowing through the system looks nothing like it does right now. Future-proofing isn't only about handling more volume. It's about having room to be nimbler and make adjustments as quickly as the market changes. A credit union that relies on standard models within a decisioning strategy may want more customized analytics and greater control over its strategies tomorrow. Connect with us With more than three decades of credit expertise and one of the industry's largest data footprints, Experian helps credit unions do more than solve this year's friction. We're helping to build a decisioning foundation that scales, so growth becomes something the system absorbs, rather than something it must be rebuilt around. Explore More

October 21, 2026 by Zohreen Ismail

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe
