Topics
Check out these four trends that speak to how Americans are doing when it comes to money management and overall financial literacy.
We’re excited to announce Family Account Management: a new feature that makes it easy to extend identity protection to family and friends.
Good job, check. Shared interests, check. Chemistry, check. He seems like a perfect 10. Both of you enjoy your first date and while getting ready for the second, you dare to imagine that turning into another and another, and possibly happily ever after. Then one decidedly unromantic question comes to mind: What is his credit score? Reviewing a potential partner’s credit score and report is important to many singles who are looking for lasting love. According to Bankrate.com, 42 percent of Millennials said that knowing someone’s credit score would affect their desire to date them, slightly more than 40 percent of Gen Xers and 41 percent of Baby Boomers. They may be on to something. Research shows that knowing someone’s credit history and sense of financial responsibility could save people time – and potential heartache. A UCLA study about money and love shows a very strong link between high credit scores and long-lasting relationships. People with drastically different credit scores may experience more financial stress down the road, placing a burden on a relationship. An Experian report reveals 60 percent of people believe it’s important for their future spouse to have a good credit score, and 25 percent of people from the UCLA study were willing to leave a partner with poor credit before marriage so they aren’t held back. While that three-digit number doesn't tell a person’s whole financial story, it can reveal financial habits that could impact your life. Banks are wary of making loans to borrowers with tarnished scores, typically 660 and below. A low score could quash dreams of buying a home, and result in steep interest rates, up to 29 percent, for credit cards, car financing and other unsecured loans. A mid-range credit score can also hurt an application for an apartment and drive up the cost of mobile phone plans and auto insurance. Eight states have passed laws limiting employers’ ability to use credit checks when assessing job candidates, yet 13 percent of employers surveyed by the Society of Human Resource Management performed credit checks on all job applicants. Talking spending styles and revealing credit scores sooner rather than later in a relationship isn’t necessarily comfortable. But it may help you decide whether you have compatible financial outlooks and practices.
Personal loans have been booming for the past couple of years with double-digit growth year-over-year. But the party can’t last forever, right? In a recent Experian webinar, experts noted they have seen originations leveling off. In fact, numbers indicate it’s gone from leveled off to a slight year-over-year decline. They projected the first quarter of calendar year 2017 may also be down, but then we’ll see a peak again in the second quarter, which is typical with the seasonality often associated with personal loans. The landscape is changing. A recent data pull revealed a 9-point shift in the average VantageScore® credit score for originations from Q3 to Q4 of 2016. Lenders are digging deeper in order to keep their loan volumes up, and it is definitely a more competitive marketplace. The days where lenders were once able to grow their personal loan business with little effort are gone. Kelley Motley, Experian’s director of analytics, noted some of the personal loan origination volume shifts may be due to the rebound in the housing market and increased housing values, enabling super-prime and prime consumers to now also consider home equity loans and lines of credit, in lieu of personal loans. Still, the personal loan market is healthy. Lenders just need to be smart about their marketing efforts and utilize data to improve their response rates, expand their risk criteria to identify consumers trending upward in the credit ranks, and then retain them as their cash-flow and financial situations evolve. In the presentation, experts revealed a few interesting stats: 67% of those that open a personal installment loan had a revolving trade with a balance >$0 5% of consumer that close a personal loan reopen another within a few months of the original loan closure 68% of consumers that re-open a new personal loan within a short timeframe of closing another personal loan do so with the same company Together, these stats illustrate that individuals are largely leveraging personal loans to consolidate debt or perhaps fund an expense like a vacation or an unexpected event. Once the consumer comes into cash, they’ll pay off the loan, but consider revisiting a personal loan again if their financial situation warrants it. The calendar year Q2 peak has been consistent since the Great Recession. For many consumers, after racking up holiday debt and end-of-year expenses, the bills start coming in during the first quarter. With the high APRs often attached to revolving cards, there is a sense of urgency to consolidate and lock in a more reasonable rate. Others utilize the personal loan to fund weddings, vacations and home improvement projects. Kyle Matthies, a senior product manager for Experian, reminded participants that most people don’t need your product, so it’s essential to leverage data find those that do. Utilizing propensity score and attributes, as well as tools to dig into ability-to-pay metrics and offer alignment can really fine-tune both an organization’s marketing and retention strategies. To learn more about the current state of personal loans, access our free webinar How lenders can capitalize on the growth in personal loans.
The holidays are behind us, the presents are unwrapped, resolutions have been made and may already be broken. For many, it’s the most depressing time of the year as the reality of holiday spending settles in. According to the American Consumer Credit Council the average American spends $935 on gifts each holiday season. A recent report by Mintel showed the average consumer held $16,000 in debt at the end of 2015. Now is the time to reach out to consumers who may be suffering from a financial hangover; an Experian study revealed consumers typically look to personal loans for help with credit card debt in the second quarter of each year. What’s the best way to reach these consumers? Direct mail is still one of the most successful paths. Here are four keys to securing new personal loan customers via direct mail marketing: Focus on education: Some of the most successful direct mail campaigns for personal loans in 2015 focused on educating consumers about personal loans first, and then showing options for debt consolidation. Consumers are weary of trusting new lenders, according to Mintel, with 50% viewing them as riskier than banks and credit unions. Marketplace and online lenders should take the extra step of introducing their brand and showing their product as a safe option. Highlight the use of the loan: Consumers generally have a negative attitude toward debt, with 72% feeling uncomfortable holding any type of debt. Stressing that personal loans are a responsible tool for consolidating debt is critical. Some effective campaigns listed the top three reasons to choose a personal loan, while others used customer testimonials to show how a personal loan was used and how they benefited. Provide a competitive comparison: Another way to highlight the benefits of personal loans is by comparing the fixed rates and payments of a personal loan to credit cards. Many consumers consolidate credit card debt to one card immediately after the holidays, according to the Experian study. Simply showing the long-term benefit of a personal loan versus credit card is often enough to trigger action. Personalize the offer: Lenders are delivering more personal, relevant offers that are tailored to the interests of each recipient through the use of the latest personalization technology. For example, highlight the recipient’s specific qualifying loan amount or the qualifying loan rate for which they are eligible. Unsecured loans have experienced growing popularity in the last several years, and originations are poised for a seasonal peak in the coming months. Are you ready?
Experian shares five trends and twists coming over the next 12 months, that could push new boundaries and in many cases improve the customer experience as it pertains to the world of credit and finance.
Regardless of personal political affiliation or opinion, the presidential election is over, and the focus has shifted from debate to the impact the new administration will have on the regulatory landscape for banks. While many questions remain regarding the policy direction of a Trump administration, one thing is near certain: change is on the horizon. While on the campaign trail, Trump took aim at banking regulation: “Dodd-Frank has made it impossible for bankers to function. It makes it very hard for bankers to loan money…for people with businesses to create jobs. And that has to stop.” And in his first post-election interview, Trump outlined named financial industry deregulation to allow “banks to lend again” as a priority. Before Election Day, Experian surveyed members of the financial community about their thoughts on regulatory affairs. An overwhelming majority—85 percent—believed the election outcome would impact the current environment. Most surveyed are also feeling the weight of financial regulations established by the Obama administration in the wake of the severe financial crisis of 2008. Five out of six respondents feel current regulations have placed an undue burden on financial institutions. Three-quarters believe the regulations reduce the availability of credit. And less than half believe the regulations are positive for consumers. According to our survey, complying with Dodd-Frank and other regulations has a financial impact for most, with 76 percent realizing a significant increase in spend since 2008. Personnel and technology spend top the list, with an increase of 78 percent and 76 percent, respectively. Top regulations that require the most resources to ensure compliance: the Dodd-Frank Act (70 percent), Fair Lending Act (55), Bank Secrecy Act/Anti-Money Laundering (47) and Fair Credit Reporting Act (42). Specifically, the Dodd Frank and TILA-RESPA Integrated Disclosure were the two most frequently mentioned regulations requiring additional investment, followed by the Military Lending Act and Bank Secrecy Act/Anti-Money Laundering. What lies ahead? It’s difficult to determine how the Trump administration will tackle banking regulations and policy, but change is in the air.
Experian Data Breach Resolution releases its fourth annual Data Breach Industry Forecast report with five key predictions on the 2017 data breach landscape
The mortgage meltdown and Great Recession have translated into big shifts as it relates to financial services regulations. What's to come with a new administration coming soon?
Unfortunately, identity theft can happen to anyone and has far-reaching consequences for its victims. According to the US Department of Justice (DOJ)’s most recent study, 17.6 million people in the US experience some form of identity theft each year. This includes activities such as fraudulent credit card transactions or personal information being used to open unauthorized accounts. The most obvious consequence that identity theft victims encounter is financial loss, which comes in two forms: direct and indirect. Direct financial loss refers to the amount of money stolen or misused by the identity theft offender. Indirect financial loss includes any outside costs associated with identity theft, like legal fees or overdraft charges. The DOJ’s study found that victims experienced a combined average loss of $1,343. In total, identity theft victims lost a whopping $15.4 billion in 2014. Beyond money lost, identity theft can negatively impact credit scores. While credit card companies detect a majority of credit card fraud cases, the rest can go undetected for extended periods of time. A criminal’s delinquent payments, cash loans, or even foreclosures slowly manifest into weakened credit scores. Victims often only discover the problem when they are denied for a loan or credit card application. Last year, Experian found that these types of fraud take the longest time to resolve. Identity theft doesn’t just impact victims financially; it also often takes a significant emotional toll. A survey from the Identity Theft Research Center found that 69 percent felt fear for their personal financial security, and 65 percent felt rage or anger. And, almost 40 percent reported some sleep disruption. These feelings increased over time when victims were unable to settle the issue on their own, according to the report, which can result in problem as work or school, and add stress to relationships with friends and family. Thankfully, consumers are getting smarter about the best ways to protect their information, like using monitoring services or following security best practices. How are you protecting yourself against identity theft? Learn more about our Identity Protection Services
With HELOC end of draw peaking, lenders must consider best practices and actions to take to manage and optimize their portfolios.
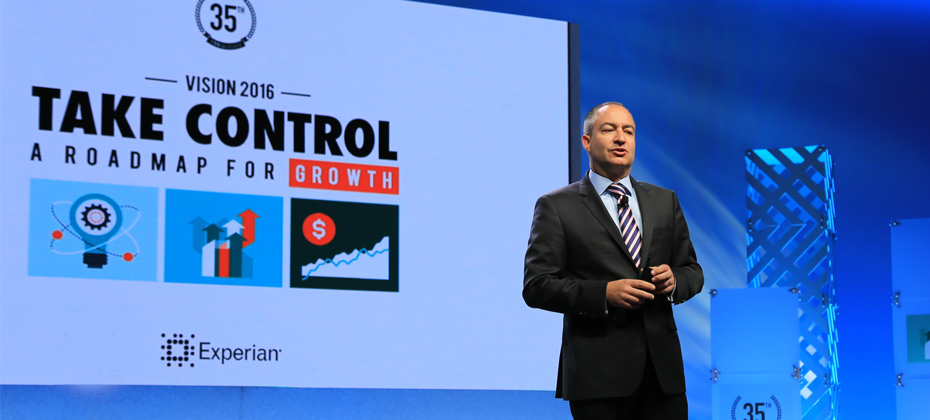
It’s impossible to capture all of the insights and learnings of 36 breakout sessions and several keynote addresses in one post, but let’s summarize a few of the highlights from the first day of Vision 2016. 1. Who better to speak about the state of our country, specifically some of the threats we are facing than Leon Panetta, former Secretary of Defense and Director of the CIA. While we are at a critical crossroads in the United States, there is room for optimism and his hope that we can be an America in Renaissance. 2. Alex Lintner, Experian President of Consumer Information Services, conveyed how the consumer world has evolved, in large part due to technology: 67 percent of consumers made purchases across multiple channels in the last six months. More than 88M U.S. consumers use their smartphone to do some form of banking. 68 percent of Millennials believe within five years the way we access money will be totally different. 3. Peter Renton of Lend Academy spoke on the future of Online Marketplace Lending, revealing: Banks are recognizing that this industry provides them with a great opportunity and many are partnering with Online Marketplace Lenders to enter the space. Millennials are not the largest consumers in this space today, but they will be in the future. Sustained growth will be key for this industry. The largest platforms have everything they need in place to endure – even through an economic downturn.In other words, Online Marketplace Lenders are here to stay. 4. Tom King, Experian’s Chief Information Security Officer, addressed the crowds on how the world of information security is growing increasingly complex. There are 1.9 million records compromised every day, and sadly that number is expected to rise. What can businesses do? “We need to make it easier to make the bad guys go somewhere else,” says King. 5. Look at how the housing market has changed from just a few years ago: Inventory continues to be extraordinarily lean. Why? New home building continues to run at recession levels. And, 8.5 percent of homeowners are still underwater on their mortgage, preventing them from placing it on the market. In the world of single-family home originations, 2016 projections show that there will be more purchases, less refinancing and less volume. We may see further growth in HELOC’s. With a dwindling number of mortgages benefiting from refinancing, and with rising interest rates, a HELOC may potentially be the cheapest and easiest way to tap equity. 6. As organizations balance business needs with increasing fraud threats, the important thing to remember is that the customer experience will trump everything else. Top fraud threats in 2015 included: Card Not Present (CNP) First Party Fraud/Synthetic ID Application Fraud Mobile Payment/Deposit Fraud Cross-Channel FraudSo what do the experts believe is essential to fraud prevention in the future? Big Data with smart analytics. 7. The need for Identity Relationship Management can be seen by the dichotomy of “99 percent of companies think having a clear picture of their customers is important for their business; yet only 24 percent actually think they achieve this ideal.” Connecting identities throughout the customer lifecycle is critical to bridging this gap. 8. New technologies continue to bring new challenges to fraud prevention. We’ve seen that post-EMV fraud is moving “upstream” as fraudsters: Apply for new credit cards using stolen ID’s. Provision stolen cards into mobile wallet. Gain access to accounts to make purchases.Then, fraudsters are open to use these new cards everywhere. 9. Several speakers addressed the ever-changing regulatory environment. The Telephone Consumer Protection Act (TCPA) litigation is up 30 percent since the last year. Regulators are increasingly taking notice of Online Marketplace Lenders. It’s critical to consider regulatory requirements when building risk models and implementing business policies. 10. Hispanics and Millennials are a force to be reckoned with, so pay attention: Millennials will be 81 million strong by 2036, and Hispanics are projected to be 133 million strong by 2050. Significant factors for home purchase likelihood for both groups include VantageScore® credit score, age, student debt, credit card debt, auto loans, income, marital status and housing prices. More great insights from Vision coming your way tomorrow!
It’s one of our favorite times of year. Yes, spring is in the air, and we’re delighted to spend a few days away from the office in picturesque Scottsdale, Arizona. But what really has us excited is the opportunity to connect with a diverse network of industry leaders from across the country at our 35th annual Vision Conference. We have a full agenda, featuring sessions on advanced data analytics, market trends, fraud and identity, regulatory hot topics and more. And our theme for this year is geared toward giving participants the tools and insights they need to take control of their respective businesses to grow new markets, increase existing customer bases, reduce fraud and increase profits. In addition to 70-plus breakout session, guests will be treated to several keynote addresses: Leon Panetta, former U.S. Secretary of defense and former Director of the CIA James W. Paulsen, Chief Investment Strategist, Wells Capital Management Jay Leno, Television Host, Author and Comedian Listen to Experian North America CEO Craig Boundy’s welcome message, and start your Vision three-day event with the goal of meeting and engaging with as many old and new contacts as possible. For individuals not attending this year’s Vision, stay tuned for learnings and insights that will be shared in the coming weeks. Attendees and non-attendees alike can also follow updates on Twitter and via #vision2016.
Businesses are looking to international markets to fuel growth, but meeting regulatory requirements across the globe poses significant challenges. Changes in Anti-Money Laundering (AML) and Know Your Customer (KYC) requirements are evolving at break-neck speed. In the past few years, financial institutions and corporations have incurred billions of dollars in fines, reputation damage, and even the possibility of criminal prosecution for not enforcing adequate regulatory controls. KPMG found that 70 percent of its respondents had received a regulatory visit within the past year focused on KYC and total investment in AML had increased by an average rate of 53 percent. As large as this additional investment may seem, there may be an even bigger cost to doing regulatory compliance the right way. For many businesses the customer experience is the biggest casualty of implementing a robust KYC program. In their Vision 2016 breakout session “Know your customer, meeting commercial requirements in a global marketplace,” Greg Carmean, Experian senior product manager, will be joined by Adel Shrufi, software development manager at Amazon Transaction Risk Management Systems. They will discuss: • How to streamline compliance to optimize the client experience • How to evaluate and select the best vendors to reduce compliance costs and operational vulnerabilities • What businesses need to consider to ensure successful launches in new international markets Watch our session preview video below: We’ll look forward to seeing you as we provide a road map for growth at this year’s Vision conference.
Basically, a blockchain is a permissionless, distributed database that maintains a growing list of records in a linear, chronological ledger.