All posts by Jonathan.Reese@experian.com
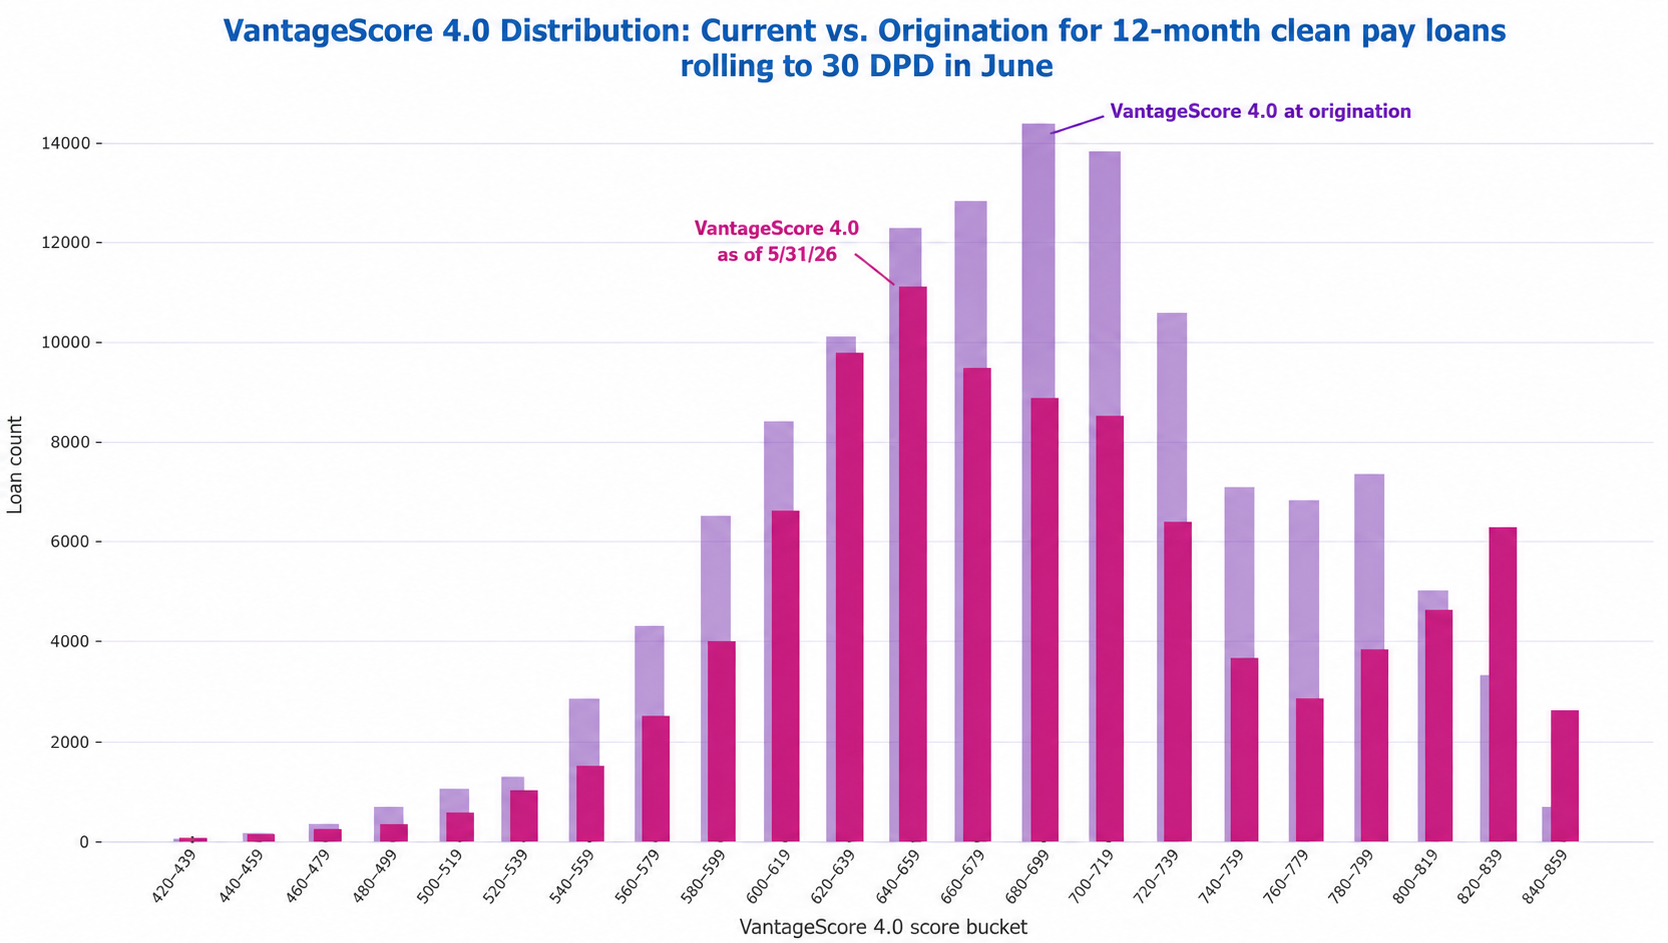
In a previous post, we described how every mortgage borrower’s financial situation and credit profile evolve over time. After a borrower opens a loan, their financial status evolves—jobs are gained and lost; incomes can rise or fall, and financially stressful situations or windfalls can occur. These effects are often reflected in the consumer’s evolving credit score, which changes with the consumer’s payment behavior on open loans, credit inquiry activity, credit card utilization, and other revolving lines, among other things. Even though MBS, whole loan, and MSR investors ultimately bear borrower credit risk, they may have access to less current borrower credit information than other participants in the mortgage ecosystem. In securitized markets (both agency MBS and private-label MBS), updated scores are not provided in disclosure to bondholders, even as loans age year over year. In whole loan and MSR markets, a single origination credit score is often provided at the time of bid, and after a successful bid, the investor may have a permissible purpose to pull individual scores on an owned portfolio. But until recently, there was no single loan-level dataset that included continuously refreshed credit scores across the U.S. mortgage market—the type of foundational dataset needed to build and tune credit and prepayment models. A monthly-refreshed Current Credit Score field meets our three-pronged materiality standard for new data delivery to MBS markets: New: Provides information not available in existing datasets (i.e., orthogonal to currently available data). Neither private-label MBS nor agency MBS standard market data includes a monthly-refreshed borrower credit score. Material: Impacts a sizeable portion of the MBS universe. For the vast majority of loans in MBS, borrowers credit scores are available. Significant: Differentiates collateral performance by a large enough margin to influence trading and risk management decisions. A current credit score wraps all of a borrower’s credit-related behaviors into a single numerical value and has historically been associated with a borrower’s likelihood of becoming 60+ days past due on any obligation within the subsequent 24 months. In fact, a current credit score is among the most informative indicators of near-term mortgage default risk, as shown in the image below, which depicts 30+ DPD rates by current credit score bands for the entire U.S. mortgage market, controlling for origination score <=650. Without access to current credit scores, investors are limited to the score at origination—causing the four distinct performance trends shown here to appear as a single averaged line. In reality, score migration since origination reveals significant divergence in credit risk, with the lowest current-score bucket exhibiting a nearly 10 times higher 30+ DPD rate than the highest-score bucket in the latest period shown. Source: Experian Mortgage Loan Performance (MLP) dataset hosted on IVolatility DataDriven Platform In this article, we’ll take a quick look at how score migration acts as an early predictor of a performing loan’s first roll into 30-day delinquent status. MBS Investors’ Current Credit Score Blindspot: Solved An MBS investor relying on standard market data and securitization remittance reports sees no sign of borrower stress until the subject mortgage loan in the securitization misses a payment and is reported at 30 days delinquent. Of course, in the vast majority of cases, a borrower begins struggling financially well before missing a mortgage payment: The borrower may miss payments on other types of loans (credit card, auto loan, personal unsecured, or payday loans) as they prioritize their home and mortgage. Outstanding balances on credit cards may grow as the borrower begins to make only minimum payments on revolvers. The borrower may apply for additional credit cards, personal or payday loans The borrower may apply to increase limits on existing credit cards as outstanding balance nears spending limit All these stress-indicative behaviors result in a decreasing credit score, many months before the borrower misses their first mortgage payment. An MBS investor with access to each borrower’s current credit score, refreshed each month, can predict increased likelihood of default many months before the first missed mortgage payment—and is therefore at a major information advantage relative to the market generally. Experian’s Mortgage Loan Performance (MLP) dataset contains thousands of fields describing mortgage performance from each borrower, loan, and property perspective, all refreshed monthly (including, amongst other things, new credit scores and refinance inquiry activity, loan performance on all types of debt, filed junior liens, and AVM values). MLP is much more comprehensive than loan-level data provided by Freddie Mac, Fannie Mae, Ginnie Mae, and PLS data vendors in several ways: Standard market datasets may not contain certain data elements that some market participants consider useful when evaluating mortgage prepayment or credit performance. Basic, critical fields such as the borrower’s current credit score and the current junior lien balance on the property are missing. MLP contains borrower, loan, and property data fields spanning a broad portion of the mortgage universe, including Agency, Non-Agency, and Esoteric mortgage products (CES, HELOC, Reverse), including both securitized and non-securitized loans. MLP enables full three-dimensional (borrower + loan + property) tracking with persistent keys for borrower (before and after refinancing), loan (in securities/deals even after exit due to payoffs or buyouts, including before and after MSR sales), and property. This enables end-to-end analysis of each borrower’s (and property’s) mortgage experience throughout their credit lifecycle. Is Downward-Trending Credit Score a Signal for Impending Delinquency? MLP contains thousands of fields describing each loan, borrower, and property across all U.S. mortgages. It allows for virtually unlimited segmentation and granular analysis. For purposes of this illustrative article, we’ll take a high-level look at the entire U.S. mortgage market and perform a quick analysis to confirm intuition that a declining credit score provides a signal for higher likelihood of near-term mortgage delinquency. Figure 1 illustrates the current pay status (as of 6/30) for the entire U.S. mortgage market, as contained in the MLP dataset, along with count, UPB and UPB-weighted Vantage 4.0 credit score for each bucket. Figure 1 Source: Experian Mortgage Loan Performance dataset As illustrated in Figure 1, approximately 772,000 individual mortgage loans were reported to Experian as 30 days delinquent as of 6/30/2026. Of the 772,000 30d delinquent loans in the June snapshot, approximately 426,000 were current in the prior (May) snapshot. Some of these 426,000 loans were reperformers which had been bouncing from 30 DPD to current over the prior few snapshots. To remove reperformance score noise, we further parsed out the population which: 1) had rolled from current to 30 DPD from May to June; and 2) was consistently current for a full year prior to the 6/30 missed payment. The population meeting both conditions totaled approximately 123,000 loans. Figure 2 below shows, for this population of 123,000 “clean current” loans, the UPB-weighted average Vantage4 credit score for each of the 12 months leading up to the June missed payment, as well as the impact of the missed payment on the 6/30 score. Figure 2 Source: Experian Mortgage Loan Performance Dataset Figure 2 reveals a rather slow and steady ~20-point deterioration of score in the 12 months prior to first missed payment – as well as the 80-point drop once the missed payment hits. When we compare this cohort’s Vantage 4.0 score trend to the broader Current population across the entire dataset in Figure 3, we see a marked difference in both absolute value and trend: Figure 3 Source: Experian Mortgage Loan Performance Dataset Not only is the cohort’s starting Vantage 4.0 score lower than the broader current population, but it also displays a dropping trend (with a notable 2 to 3x acceleration in monthly score drop the month before the first missed mortgage payment) while the broader Current population’s score (of which the isolated cohort is a subset) remains rock steady. Lastly, we present Figure 4, a histogram comparing the distribution of at-origination and as-of 5/30 (i.e., the period just before the missed June mortgage payment) credit scores for the clean current population. The distribution appears to shift toward lower credit scores. To the extent credit scores are correlated with credit risk, this shift may indicate elevated credit risk relative to origination. Since this degradation occurs during a period of perfect mortgage pay performance, it is invisible to MBS investors who lack access to current borrower credit scores. Experian MLP provides monthly refreshed credit scores for mortgage borrowers contained within the MLP database. Figure 4 Source: Experian Mortgage Loan Performance Dataset
Explore how the Experian Verify™ preview report helps mortgage lenders reduce unnecessary verification costs, avoid overbuying records, and make smarter VOIE decisions with greater visibility before they purchase.
Explore how Experian Verify™ and Mezzo’s Centro orchestration engine are helping mortgage lenders modernize income and employment verification, reduce workflow complexity, and make faster, more confident lending decisions at scale.
In our previous post, we described the Current Second Lien Balance field, which is one of over 2,000 fields in the new Experian Mortgage Loan Performance (MLP) dataset. We showed that the Current Second Lien Balance field meets our three-pronged materiality standard for new data delivery: New: Provides information not available in existing datasets (i.e., orthogonal to currently available data). Material: Impacts a sizeable portion of the MBS universe. Significant: Differentiates collateral performance by a large enough margin to influence trading and risk management decisions. In this article, we discuss another field that satisfies the above criteria: Student Loan Balance. We evaluate this field in the context of these criteria. First, however, we provide a summary of the MLP dataset and how it compares to standard GSE loan-level data available today. Standard GSE Data vs. Experian Mortgage Loan Performance (MLP) Data The MLP dataset contains thousands of fields describing mortgage performance from each borrower, loan, and property perspective, all refreshed monthly (including, amongst other things, new credit scores and refinance inquiry activity, loan performance, filed junior liens, and AVM values). MLP differs from loan-level data provided by Freddie Mac, Fannie Mae, and Ginnie Mae, which the vast majority of market participants solely rely on, in a number of ways: Standard data provided by the GSEs and GNMA does not contain all the information necessary for accurate forecasting of mortgage prepayment and credit performance. Basic, critical fields like borrower’s current credit score and current junior liens on the property are missing. The new Mortgage Loan Performance (MLP) dataset from Experian contains borrower, loan, and property data fields covering the entire mortgage universe, including Agency, Non-Agency, and Esoteric mortgage products (CES, HELOC, Reverse), both securitized and non-securitized. MLP enables full three-dimensional (borrower + loan + property) tracking with persistent keys for borrower (before and after refinancing), loan (in securities/deals even after exit due to payoffs or buyouts, including before and after MSR sales), and property. This enables end-to-end analysis of each borrower’s (and property’s) mortgage experience throughout their credit lifecycle. New, Material and Significant Field: Student Loan Debt MLP contains a number of fields describing each mortgage borrower’s student debt load, including amounts in repayment, forbearance and collections; estimated interest rate, time remaining until forbearance expiration, and more. In the interest of simplicity, for this article we’ll focus on a single student loan-related field within MLP: Student Loans Balance, which is defined as the total balance on open non-deferred student trades reported in the last 3 months. Is Information Regarding Student Loans New to Markets? Standard loan-level data disclosed by the GSEs and GNMA contain no student-loan-specific fields. Theoretically, fields related to DTI at origination might capture some aspect of student loan debt. So, in the best-case scenario for an investor relying solely on standard disclosure, a DTI value as of origination is provided -- yet is never updated as the loan seasons and the borrower’s debt and income change (see more here). But in the case of federal student loan debt attached to mortgages originated from early 2020 to late 2023, the level of detail provided by disclosure may be even more unknown due to COVID-era repayment and reporting moratoriums. The student loan repayment moratorium was a temporary federal policy that paused required payments, set interest rates to 0%, and suspended collections on most federally-held student loans. The moratorium began in March 2020, with payments resuming in October 2023, making it approximately 3.5 years in duration—the longest consumer credit payment pause in U.S. history. (Source: NCUA ) During the moratorium, student loan-related debt loads may have been understated as federal loans were in a temporary state of $0 repayment. As an alternative to leaving student loan debt completely out of DTI calculations, an imputed payment equal to only 0.50% of the outstanding balance was often used as a placeholder for a borrower’s DTI calculation. Standard data only reports information related to the primary mortgage and does not include any details on the borrower’s other debts, with the exception of DTI at origination, which is never updated throughout the life of the loan. In contrast, MLP provides a comprehensive view of the borrower’s full credit profile, including other obligations such as credit cards, mortgages on other properties, student loan balances, and much more. Is Student Loan debt material to the residential mortgage market? Approximately $11 trillion of residential mortgage loans were originated during the student loan payment moratorium (Source: Experian MLP Dataset), a period marked by historically low mortgage rates during the COVID era. As discussed above, DTI data contained in standard market disclosure may be particularly inaccurate for these loans. As the Wall Street Journal recently reported, a new report from the Federal Reserve of New York shows a rise in student loan default rates by age group. Student loan delinquencies have been broadly trending higher across all age groups. Also, the average age of a borrower in default has risen to 40, and borrowers aged 50 and older are now at a higher risk of default than younger groups. This 40 to 50-year-old age group represents prime home ownership years. Defaulted borrowers are also struggling to make other debt payments, too. The same report stated that almost 40% of past due student loan borrowers with auto loans are past due, 56% have at least one credit card past due, and 20% have a past due mortgage. In addition to increased delinquency risk on their mortgage, borrowers with student loan debt also have fewer mortgage refinance options, as their elevated DTI may prevent qualification for a refinance, or increase the offered rate of a refinance and thereby reduce their incentive. These dampening effects of student loan debt on mortgage CPR are clearly evident in the data, as described further below. Of today’s $13 trillion in outstanding mortgage debt, more than 10% of that debt ($1.5 trillion) is associated with borrowers who carry student loan debt. For these borrowers, the average amount of student loan debt outstanding is approximately $50,000, versus a mortgage balance of approximately ~$289,000. In other words, the average student loan debt balance is almost 20% of the mortgage balance for the average borrower who carries both. For this set of borrowers, the average monthly payment is approximately $400 for student loan vs. approximately $2,200 for 1st lien mortgage—so that monthly student loan payments are a significant debt load, approximately 20% of the monthly mortgage payment. (Source: Experian MLP Dataset) Is the effect of student loan debt a significant driver of performance? Figure 1 illustrates prepayments by student loan balance for a sample of loans drawn from MLP. The chart illustrates that borrowers with larger student loan balances prepay much more slowly, likely because some are effectively locked out of refinancing once student loan payments resume due to elevated DTI. The debt-to-income (DTI) ratio calculated using actual student loan payments may be significantly higher than the DTI calculated during the moratorium, in some cases exceeding GSE eligibility thresholds. As illustrated in Figure 1, for in-the-money (ITM) collateral, the differential between loans with material student loan balances (greater than $200,000) and loans with no student debt can reach up to 5 CPR. Notably, even for out-of-the-money (OTM) collateral, loans with student debt prepay 1 to 3 CPR slower, likely reflecting reduced mobility due to tighter financing constraints when purchasing a new home. Pools with otherwise similar prepayment characteristics may exhibit different prepayment behavior depending on the distribution of student loan exposure within their collateral. In addition, because loans with student debt tend to prepay more slowly, this effect increases over time due to burnout: loans without student debt prepay and exit the pools more quickly, leaving a higher concentration of slower-paying loans behind. Given that 10% of the $13 trillion outstanding mortgage market is associated with borrowers who have student loans (Source: Experian MLP dataset)—and that student loans have a meaningful impact on prepayments—many pools issued between March 2020 and October 2023 may be subject to this student loan debt CPR throttle, and therefore mispriced by investors relying exclusively on standard market data. Fig 1. Prepayment S-Curve: Student Loans Balance Source: Experian MLP dataset hosted on IVolatility Data-Driven Platform _____________________________________________________ Michael Pyatski advises MBS traders, portfolio managers, quants, risk managers, loan originators, and technology professionals on making informed, data-driven business decisions that drive revenue growth, enhance risk management, and reduce trading costs. With more than 15 years of experience as an Agency RMBS trader—including serving as Head of the Proprietary Trading Desk at BNP Paribas—Michael developed and successfully implemented relative-value, data-driven profitable trading strategies to capture market opportunities embedded in data but not fully priced by the market. His trading experience, combined with a Ph.D. in econometrics, led him to found the Data-Driven Portal (https://datadrivenportal.com/), a platform that provides advanced technology for MBS trading and risk management. The platform’s No-Model Data-Driven technology leverages big data, econometric analysis, and AI to help traders identify relative-value opportunities in RMBS markets and generate above-market, risk-adjusted returns. _____________________________________________________
Lenders who want to outperform peers in today’s housing market should embrace a data-driven playbook. These four strategic pillars—borrower insights, efficiency, geography, and refinance readiness—define the path forward.
Discover how Experian’s Rent Bureau and Observed Data can transform your mortgage lead strategy by predicting income, risk, and readiness earlier in the funnel—improving targeting and reducing acquisition costs.
With the Fed initiating rate reductions, the housing market is entering a new phase. Learn what mortgage lenders must know about affordability, borrower behavior, and emerging opportunities.
Direct mail is reshaping mortgage and home equity lending in 2025. See why prescreen targeting, data-driven personalization, and market exits are creating new growth opportunities for lenders.
Addressing where renters struggle mostRental affordability is diverging fast across the U.S. See which states and cities face the biggest rent increases, rising rent-to-income ratios, and shifting renter pressure.
With the Fed initiating rate reductions, the housing market is entering a new phase. Learn what mortgage lenders must know about affordability, borrower behavior, and emerging opportunities.
Experian's 2025 housing update shows how softening credit, refinance growth and prescreen tools help lenders manage risk and capture demand.
See how borrower credit, DTI, income, and insurance costs shift after origination, and how EES delivers the visibility lenders need to refine credit and prepay risk.