Innovation
At Experian, we are continually innovating and using technology to find solutions to global issues, modernize the financial services industry and increase financial access for all. Read about our latest innovation news below:
Phishing attacks have become more sophisticated and personal. We are all busy with life – work, family, commute, and dinner plans, along with keeping up on the latest news cycle. Virtually anyone could be inclined to quickly click on a link stating there is an issue with their recent order. But there's more to phishing attacks than just baiting businesses and consumers. During a recent #ExperianLive event, Mike Gross, Head of Global Identity and Fraud Product Innovation, discussed what businesses can do to protect themselves and their customers. Q: You say that phishers would make good digital marketers. What do you mean by that? Mike: Like a great marketer, a good phisher understands people and their tendencies; they know how to get people to take action on their message. Take my most recent “almost phishing" incident. During the holidays, I received an email from a top online retailer stating there was a “problem with my recent order." I knew that any delay would jeopardize my holiday gift delivery. I was just about to click the “Login" button and then stopped. Thankfully, I double-checked the sender and it wasn't my favorite shopping site after all – just a really good fake email from a "phishy" sender. Like a digital marketer, phishers understand how to specifically target the things that people care about. This is why phishing attempts focused around the holidays, tax season, natural disasters, and hot news topics are often so successful. Q: Are phishers counting on the relationship and roles people have in an organization? Mike: Yes. That's the whole nature behind one of the biggest phishing attacks over the past several years – business email compromises. As a phisher, I'm sending you an email that looks like I work with you, say a vendor with a message that reads, “I changed the account that you use to pay me; please update your payment to this new account." If there is urgency behind it, it is taken seriously - for example, to avoid being late on paying a vendor. Human nature is being helpful and reacting, especially in this fast-paced, hyper-connected world – and that's why these scams continue to work. Q: What other phishing trends are you seeing? Mike: They've evolved over time. Take the simple phishing email; it's not so simple anymore. Nowadays, attacks are personalized to both the business and specific person – and phishers are taking advantage of automation and targeting tools so they can get the most reward for their effort. “Smishing" is variant of phishing focused on the phone channel, where attackers target victims with an SMS-based attack; you've probably seen them. You get a text and link from what you think is your friend saying something like “Check out this funny video!" But it isn't legitimate; it's a fraudster that is spoofing your friend's phone number. Then there is “vishing" which is a voice-based attack. This is where a fraudster pretends to be someone they're not (like a consumer's financial institution) and tries to obtain personal information or take over an existing account. Q: Wow! Phishing fraud is sophisticated. What has led to that? Mike: We've seen a tremendous leap in technology used. There is a great example of that last year with a U.K. bank. Their customers expect that if there is an out-of-place transaction, the bank will call them. In this particular vishing scheme, vishers used compromised accountholder usernames and passwords to log into customer accounts and set up money transfers. Knowing that this would alert accountholders to the attempted transfer using the SMS one-time passcode, phishers called legitimate customers, impersonated the bank, and stated that since the customer was a recent fraud attack victim, the bank needed confirmation that they were the accountholder. The vishers told customers they would receive a passcode. While the customer confirmed the code, the vishers submitted the fraudulent transfer. Q: What trends and techniques are you seeing? Mike: Two of the big trends we're seeing is around Artificial Intelligence (AI), machine learning, and SMS to find victims. A big part of phishing is what we call “spear phishing." This targets individuals with access to an organization's financial accounts or internal systems. Another term is “whaling" which targets a specific high-profile individual. The phishers are no longer just sending out blanket lottery scam and Nigerian prince emails with misspellings to millions of people. It's very focused – and phishers can easily do this using machine learning and AI. Q: Do you notice any seasonality, or spikes in phishing based on a certain time of year? Mike: The holidays are one because so many people go to their favorite shopping sites and buy items that are completely out of pattern based on what they usually do online. Another good example is tax season. We saw phishers impersonate top tax and financial management software providers, allowing consumers to “quickly and easily submit their tax forms online." What's worse is that phishers use the knowledge you have about phishing against you. Things like “How do you protect yourself? Click on this link to learn more" or “Click this link to download software and protect your devices." Also, fraudsters pay attention to the news, so whether it's a natural disaster or the cathedral fire that happened in Paris last April, phishers see those as opportunities to prey on victims simply trying to donate to a worthy cause. Q: What advice do you have for businesses and consumers to protect themselves against phishing attacks? Mike: My advice for businesses is to focus on technology and training. Strong technology solutions must be in place at all businesses to block phishing emails that are coming from suspicious sites – and for the most part, large organizations do a great job of that. Smaller businesses can also take advantage of technology solutions from their internet providers. Businesses can implement web blocking software for less secure Internet sites and filter what types of content employees can have access to on business devices. A lot of companies hire outside consultants to talk about the different types of phishing attacks with employees. These are helpful, but the key is to not allow training to become static because attackers evolve so quickly. Both businesses and consumers can use the email filtering option that is available through nearly every email provider. Don't click on any attachments that even remotely look suspicious - especially if they've been texted to you from someone you either don't know or the message appears out of character for someone you know. Q: What activities is your group taking on that will help businesses and their customers fight phishing attacks? Mike: There are several things we're doing that impact businesses and consumers offline and digitally. We help businesses recognize their customers and authenticate them, whether that's helping customers with a new bank account, enabling easy checkout at a favorite retailer app, or protecting account logins. 99% of people trying to access accounts are the legitimate account holder; it's that 1% though that causes a lot of friction for good customers. So, we're trying to make it easier for those consumers to quickly pass through all of the controls so authentication is easier. That translates into consumer loyalty for brands. Q: And that's what it's really all about? Mike: It is. We help businesses recognize their customers and also ensure that they are catching fraudsters on the back end. But we also strive to make that recognition or user experience as seamless as possible, with the right scrutiny for the risk level of that business. Mike Gross leads product innovation strategy for Global Identity and Fraud at Experian. Check out the entire podcast and video on how to protect your business from phishing here.
We are delighted to announce our investment in bonify, a German fintech start-up dedicated to giving consumers better insights into their creditworthiness. bonify gives its 500,000 customers easy access to their creditworthiness and financial data, offering them a number of financial management tools to help analyse and optimise their financial situation. At Experian, we believe very deeply in the power of data to help improve people’s lives. That’s why we’re so excited by bonify’s continued goal to improve its users’ financial lives, and the steps it is taking to help people in Germany understand and benefit from their financial information. We are delighted to join a number of investors in supporting the growth of this innovative start-up. Charles Butterworth, Managing Director Experian UK, Ireland and EMEA, said: "We are excited by the way bonify is helping people in Germany understand, engage with and improve their credit scores. We look forward to supporting the team as an investor and partner in their future growth.“ Founder and CEO of bonify, Dr. Gamal Moukabary, said: “Experian's investment shows that we are on the right track. It rewards our achievements and our unique value proposition. Experian is an ideal investor and partner for us to support the next growth phase. Our goal is to expand our operations into other European countries.” Manuel Silva Martínez, Partner and Head of Investments, Santander InnoVentures, added: “We are delighted to welcome Experian Ventures to bonify. Experian will add tremendous value and technical expertise to bonify’s product roadmap. We are thrilled to support bonify as we accelerate growth and help more and more people across Germany and Europe with taking control of their finances in a sound and responsible way.
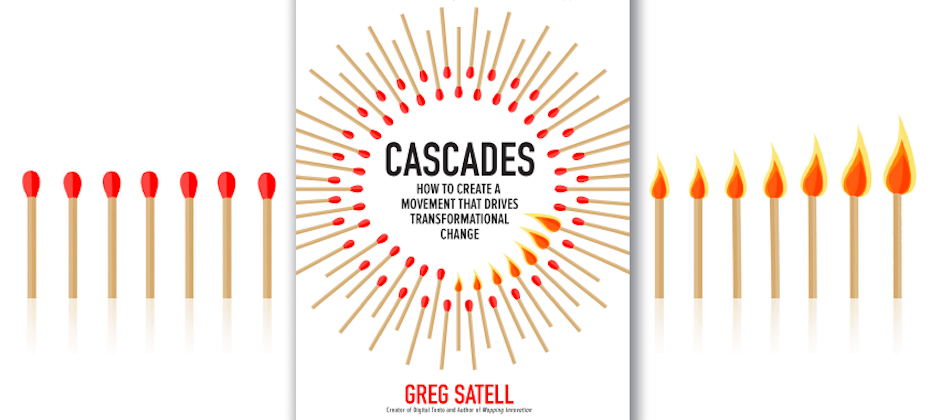
Technology revolutionizes the way businesses operate, but implementing change within a company is often challenging. Company-wide support is vital to successfully undergo a transformation. At Experian, in 2015, we underwent the task of moving from a traditional computing architecture to the cloud. This is a monumental transformation with our massive digital infrastructure and significant global reach, but it enables us to provide customers with real-time access to data. This journey is featured in the new book, Cascades: How to Create a Movement that Drives Transformational Change, by Greg Satell. Last year Satell’s first book shone a light on Experian’s innovation story. In his latest book he talks about the power of cascades - small groups, united with a common purpose - to drive transformational change within businesses. He gives examples of how some companies succeed, while others fail. Satell uses Experian as a case study and highlights how changes to our culture, organizational structure and skills is allowing us to adopt new technologies quicker, in better collaboration with our customers, to get cutting-edge, innovative products to market faster. At Experian, we believe in the culture of inclusion, which brings a culture of innovation with the added diversity perspective that empowers our people to continue to evolve and create valuable additions to the company during this transformation. Our philosophy is about advancing a culture that not only respects differences, but also actively celebrates them. In Cascades, Satell writes about the idea of small groups, loosely connected, but united by a common purpose. We asked the author for his thoughts about Experian’s technology journey, which he refers to as our digital transformation, and why he’s used Experian as a success story in his book. Q. What are your thoughts about Experian’s digital transformation so far? Satell: What attracted me to the Experian story was how closely it tracked with so many of the social and political movements I researched for my book. Senior leadership at Experian didn’t just try to push its digital transformation through. Rather, they identified those who were already enthusiastic and empowered them to bring others into the fold and they, in turn, could bring others in. That's how you create a cascade that leads to transformational change. Q. What has impressed you the most about Experian’s digital transformation, from both technology and human perspectives? Satell: What I found most impressive is that Experian is able to break free from decades of legacy and build a new future for itself. That's a very hard thing to do. You have all this infrastructure that served the business so well for so long. I mean you're talking about decades of investment. Still, the company leadership was able to step back and say, ‘That's our past and we're proud of it, but it's not our future’, and move forward from there. Q. Have you seen any examples of how our digital transformation is driving innovation within Experian? Satell: Well I think it has driven a lot. Things like Experian’s Analytical Sandbox, the Ascend platform and much of the current work around Artificial Intelligence (AI) wouldn't be possible without moving to more of a cloud infrastructure.
Fraud attacks continue to increase, and businesses and consumers alike are recognizing the need for more effective preventative measures. In June 2016, we launched the industry’s first open platform designed to catch fraud faster, improve compliance, and enhance the customer experience. Experian CrossCoreTM has put more control in the hands of fraud teams and it continues to receive global recognition for its impact in the industry. We are proud to announce that CrossCoreTM has been named a market leader for fraud prevention by Cyber Defense Magazine’s 7th Annual InfoSec Awards. Judged by an independent panel of certified security professionals, the InfoSec Awards recognize the best ideas, products and services in the information technology industry. In the past year, the platform was also named best fraud prevention innovation by Cybersecurity Breakthrough and as best cybersecurity initiative of the year by CIR Magazine. Since 2016, Experian has been proud to serve organizations looking for better ways to get more out of their existing fraud and identity systems and to more effectively deploy new products and offers, while improving the customer experience and minimizing risk. According to Experian’s 2019 Global Identity & Fraud Report, 55% of businesses reported an increase in online fraud-related losses over the past 12 months, predominantly around account origination and account takeover attacks. Our study shows that consumers value security and convenience. They also expect to be recognized and met with a personalized experience. Businesses can deliver both security and convenience, but to do so, they need to apply the right tools and relevant information. CrossCoreTM is helping fraud teams around the world accomplish this by adapting and deploying strategies that keep up with the pace of fraud while reducing burdens on IT and data science teams. Learn more about CrossCore.
As digital transformation follows its course, ubiquitous data and new technologies are dramatically changing the way consumers interact with businesses. The Amazons and Googles of the world are redefining customer experience on a daily basis and setting the bar higher for the rest of industries to catch up. This ‘customer-first’ era calls for innovative ways to achieve sustainable growth and market leadership. Aimed at understanding this new reality, we commissioned Forrester Consulting to survey senior executives and decision makers about how they tackle the challenges and opportunities surrounding digital transformation. What we found is that the key to succeed in today’s highly competitive and fast paced environment is creating a comprehensive, unified view into their customers and their needs. And that although businesses are committed to keeping up with the pace of change to stay relevant, there are still trying to figure out how to execute their ‘customer-first’ vision. Businesses from all over the world wonder how they can attract and retain new customers, or what are the tools they need to quickly act on insights and make consistent, relevant decisions about what matters the most to their customers. Our research shows that the early beneficiaries of digitalisation such as fintech companies and e-commerce brands have been quick to understand younger, tech savvy and convenience-hungry consumers. Both industries have leveraged decades of technology developments to meet their customers’ expectations, setting the bar high. They have evolved from one-time transactions to building relationships, creating loyal followers and facilitating repeat purchases. Financial services and other sectors can find inspiration in how customer strategies focused on relevance and personalisation deliver the curated experiences consumers demand. When you put the customer first, the opportunities to create more value from your customer relationships are endless. We believe the future is bright for the business which remains nimble and willing to evolve their business models, using technology to meet the needs of tomorrow’s customer. Key findings 81% of executives believe traditional business models will disappear over the next five years due to digital transformation. 79% of key decision makers believe their customers can seamlessly interact with their organisations across mobile, web, and in-person channels – and are generally positive about the progress they are making. Two thirds of executives believe their profitability would improve if they were able to create that single, comprehensive view of the customer. Knowing and understanding customers better than anyone else is paramount to consistently assisting them how, when and where they need it. Businesses must ensure that they offer appropriate products that their customers can afford and benefit from now and in the future, regardless of market conditions or changing personal circumstances. Six out of ten executives believe sharing their data with third parties and tapping into additional data will help them create frictionless customer experiences. But there are some challenges they need to overcome before achieving that. For example, 40 percent of executives globally still feel they cannot easily share their data. They also need to make sense and find meaning from all the data they have. They are currently investing in new technologies to make sense of their data, but these efforts are not going far enough. 53% of businesses worldwide struggle to make consistent customer decisions. Part of it due to the gathering of inconsistent data from one channel to the next. The better businesses get at managing different points of interaction, the more insight they can obtain within a given customer’s experience. Using advanced analytics helps unlock the value latent in different points of interaction along the entire relationship with your customers. 77% of executives set aside budget for advanced analytics and decision-management systems. To turn strategic priorities into action, businesses have set aside budget to invest in analytics and digital decisioning. Thanks to innovative analytical tools, businesses can deliver improved, personalised experiences when they matter, better protecting consumers and complying with regulations. Download the full report.
Financial exclusion is a global issue with an estimated 1.7 billion adults currently ‘unbanked’ . Experian’s core mission is to help bring financial inclusion to every adult in the world. There are currently millions of ‘thin file’ consumers and SMEs in sub-Saharan Africa. These are consumers with limited information on a traditional credit bureau or have no information at all, so-called ‘invisibles’, who find themselves excluded from mainstream finance. They often face more difficulty – or higher costs - when applying for financial products or services. That’s why we are proud to announce today the launch of a ground-breaking new smartphone app, GeleZAR, in South Africa, which aims to bring more micro-entrepreneurs into the mainstream economy and ensure they get the credit score they deserve.. Using the expertise of our global innovation hubs, we have developed a unique financial education and credit scoring mobile app. GeleZAR is designed to educate entrepreneurs and individuals on how to manage their finances, budget and credit score in a fun, entertaining and digestible way. It can also advise individuals on how to maintain a good credit health and recommends remedial actions where needed. In partnership with a local South African consumer and fintech developer, Experian designed the app specifically for entry-level smartphones. We are also working with one of the largest low-cost mobile phone retailers in Africa to trial the app which has been pre-installed on a range of its entry-level smartphones.. The intention is to extend the rollout and make the app accessible for free on more than six million devices annually. Working with alternative data that an individual user consents to share on the app, GeleZAR will be able to assess an individual’s stability, build a credit profile and potentially improve their credit score. This in turn could enable them to access a broader range of financial products at more affordable interest rates. This is a great example of how Experian is innovating to find new ways to empower our customers while uplifting societies. It also fulfils our passion for financial inclusion and the accurate assessment of affordability. Experian’s cutting edge technological capabilities enable us to use the power of data to transform lives, businesses and economies for the better. Through our pioneering work in this space we hope to help consumers around the world on their credit journey. GeleZAR is just one of the ways we are delivering on our mission to build and improve the credit files of millions of people in South Africa and beyond.
Digital commerce has changed the way consumers interact with businesses. More people are transacting online versus going into retail stores, and more than half of banking is done via mobile channels. Yet both businesses and consumers still want convenience and security, without increased fraud risk. And as interactions have become more anonymous in an online space, trust is based on businesses protecting consumers from fraud while still providing a great customer experience. So, what does it take to build trusted relationships online? New research from our 2019 Global Identity and Fraud Report shows that 74% of consumers see security as the most important element of their online experience, followed by convenience. In the past, businesses have often invested in one at the expense of the other, and our research suggests that consumers can expect both security and convenience without the trade-off. The availability of information consumers share with businesses make this possible, and consumers are willing to share more personal information if they believe it means greater online security and convenience. In fact, our research found that 70 percent of consumers are willing to share more personal data, particularly when they see a benefit. However, this value exchange of more personal information for a better online experience is the same information that puts consumers at a greater risk for fraud. Instead, businesses need to demand more from the information they already have access to and use more sophisticated authentication strategies and advanced technologies to better identify their customers and deliver tailored, streamlined experiences without increasing their risk exposure. Findings from the study reveal that consumers and business leaders agree that security methods enabled by new technologies and advanced authentication methods instill online trust. In fact, consumer confidence grew from 43 percent to 74 percent when physical biometrics was used to protect their accounts. The report also found that businesses are beginning to embrace the changing technology, while half of organizations globally reported an increase in their fraud management budget over the past twelve months. And lastly, the report looked at transparency and how that impacts consumer trust. In order to create even more trust online, many businesses are proactively sharing with customers how they use their personal information. The report found that nearly 80 percent of consumers say the more transparent a business is about the use of their information, the greater trust they have in that business. And the good news is that 56 percent of businesses plan to invest more in transparency-inspired programs such as – consumer education, communicating terms more concisely, and helping consumers feel in control of their personal data. Fraud remains a constant threat and it should come as no surprise that nearly 60 percent of consumers worldwide have experienced online fraud at some point. However, both business and consumers are getting smarter about how they manage fraud and it comes down to the important theme of trust. In order for consumers to trust businesses, they need to feel secure. And by adopting better security measures, businesses can embrace the important role of protecting customers and giving them the experience they want and deserve. Download the new Experian 2019 Fraud & Identity report here.
In an article published by Bloomberg this week, Brian Cassin, Experian CEO, discusses the transformation of the business from a credit bureau to an innovative, global information services firm. The story highlights some of the remarkable work Experian does with high-profile clients including Coca-Cola and Fannie Mae, using data to inform marketing and strategy decisions. The article also references recent product innovations including Ascend, which offers analytics on demand, and PowerCurve, our market-leading decision analytics platform. Worth mentioning is that Experian’s strong financial performance also comes through in the article, which notes that the company’s stock price has doubled since 2015 while the FTSE 100 index has stagnated. Check out the full article.
We recently participated in Finovate Fall, where we joined top fintechs and financial institutions from around the world to debate about the current state of the financial services industry and more importantly, its future. A future where the so-called ‘experience economy’ will unfold and those putting the customer at the center of their innovation will thrive. But, how to get there and remain relevant in an ever-challenging environment? Committing to a culture of technology and innovation that transforms interactions between businesses and consumers is the first step. Take financial institutions and fintechs, for example. Despite their different approaches to what it takes to serve their customers better, both traditional and non-traditional industry players agree that technologies such as artificial intelligence (AI) and machine learning play a pivotal role in their respective digital transformation strategies. But with the change comes the challenge: most of organizations recognize they still struggle to fully operationalize the output of their advanced predictive analytics. To be true to our own commitment to technology and innovation and help businesses execute machine learning models within their decision processes, we have launched a new release of our flagship decisioning platform. The latest PowerCurve release integrates machine learning to deliver a faster and better analysis of data. These actionable insights will help our clients identify the opportunities presented by each of their customers quicker and more easily. Leveraging today’s technology to sustain tomorrow’s growth We believe that enabling businesses to leverage their current technology investments to support future growth is key to ensure they get the full benefit of their commitment to innovation. The latest PowerCurve capabilities allow custom plug-ins to be added at any time to support the next generation of technology and decision-making strategies while ensuring consistent, precise and personalized experiences that satisfy consumers’ demands over time. This enhanced flexibility means that businesses can get value of their current data and technology investments today and keep at pace with the latest and most effective decision management strategies across the entire customer life cycle. In addition, PowerCurve will continue to satisfy compliance requirements and provide the necessary governance and explainability that is essential in today’s market. With the updates to our decisioning platform and incorporation of machine learning capabilities, businesses will be able to make the right decisions today, resting reassured that those decisions will remain precise and relevant in the future.