It’s been a dynamic several weeks and I’ve finally had a chance to reflect on some of the conversations, collaborations and developments that have made this such an exciting time.
From meaningful progress on modern credit scoring to new innovations and important conversations about expanding access to homeownership, it’s become increasingly clear that changes the housing industry has discussed for years are finally taking shape.
Experian has long advocated for more modern credit scoring and better data in mortgage lending. What feels different now is that we’re seeing real movement. VantageScore 4.0 is now available to lenders approved by Fannie Mae and Freddie Mac, and it’s been particularly exciting to see more large lenders embracing modern scores.
We’re moving from a conversation about what could change to taking meaningful steps to put that change into action.
That matters because a score is only as useful as the information behind it, and a thin credit file does not necessarily mean a thin financial life. I’ve been saying this for a while now, so it’s both validating and encouraging to see that same message being used by others in the industry. The reality is that many consumers have rich financial histories that simply haven’t been reflected in traditional credit files, and it’s exciting – and flattering – to see more organizations acknowledging that truth.
 Information such as rent and utility payment history can help fill in parts of the picture, giving lenders a fuller view of consumers whose financial lives may not be fully reflected in traditional mortgage models. Better information can help lenders make more informed decisions while recognizing more qualified consumers on the path to homeownership.
I talked about the industry’s shift toward modern scoring in a recent podcast with leaders from the other nationwide credit reporting agencies. We revisited a conversation we first had a year ago, when the industry was still preparing for modern scores to enter the mortgage market. This time, we could talk about what has changed, including the move from policy into practice, the growing choices available to lenders and our shared responsibility as an industry to support accurate, well-informed decisions.
That same focus on turning progress into practical solutions is behind our recent Power Profile Plus for Mortgage enhancements, announced ahead of the MBA Annual Convention and Expo.
The enhancements are designed to lower early-stage costs and give lenders more score flexibility. Now, lenders can obtain an initial full Experian credit profile with VantageScore 4.0 through a soft inquiry, then request eligible follow-up soft inquiries during the application and qualification period without another Experian credit-profile charge.
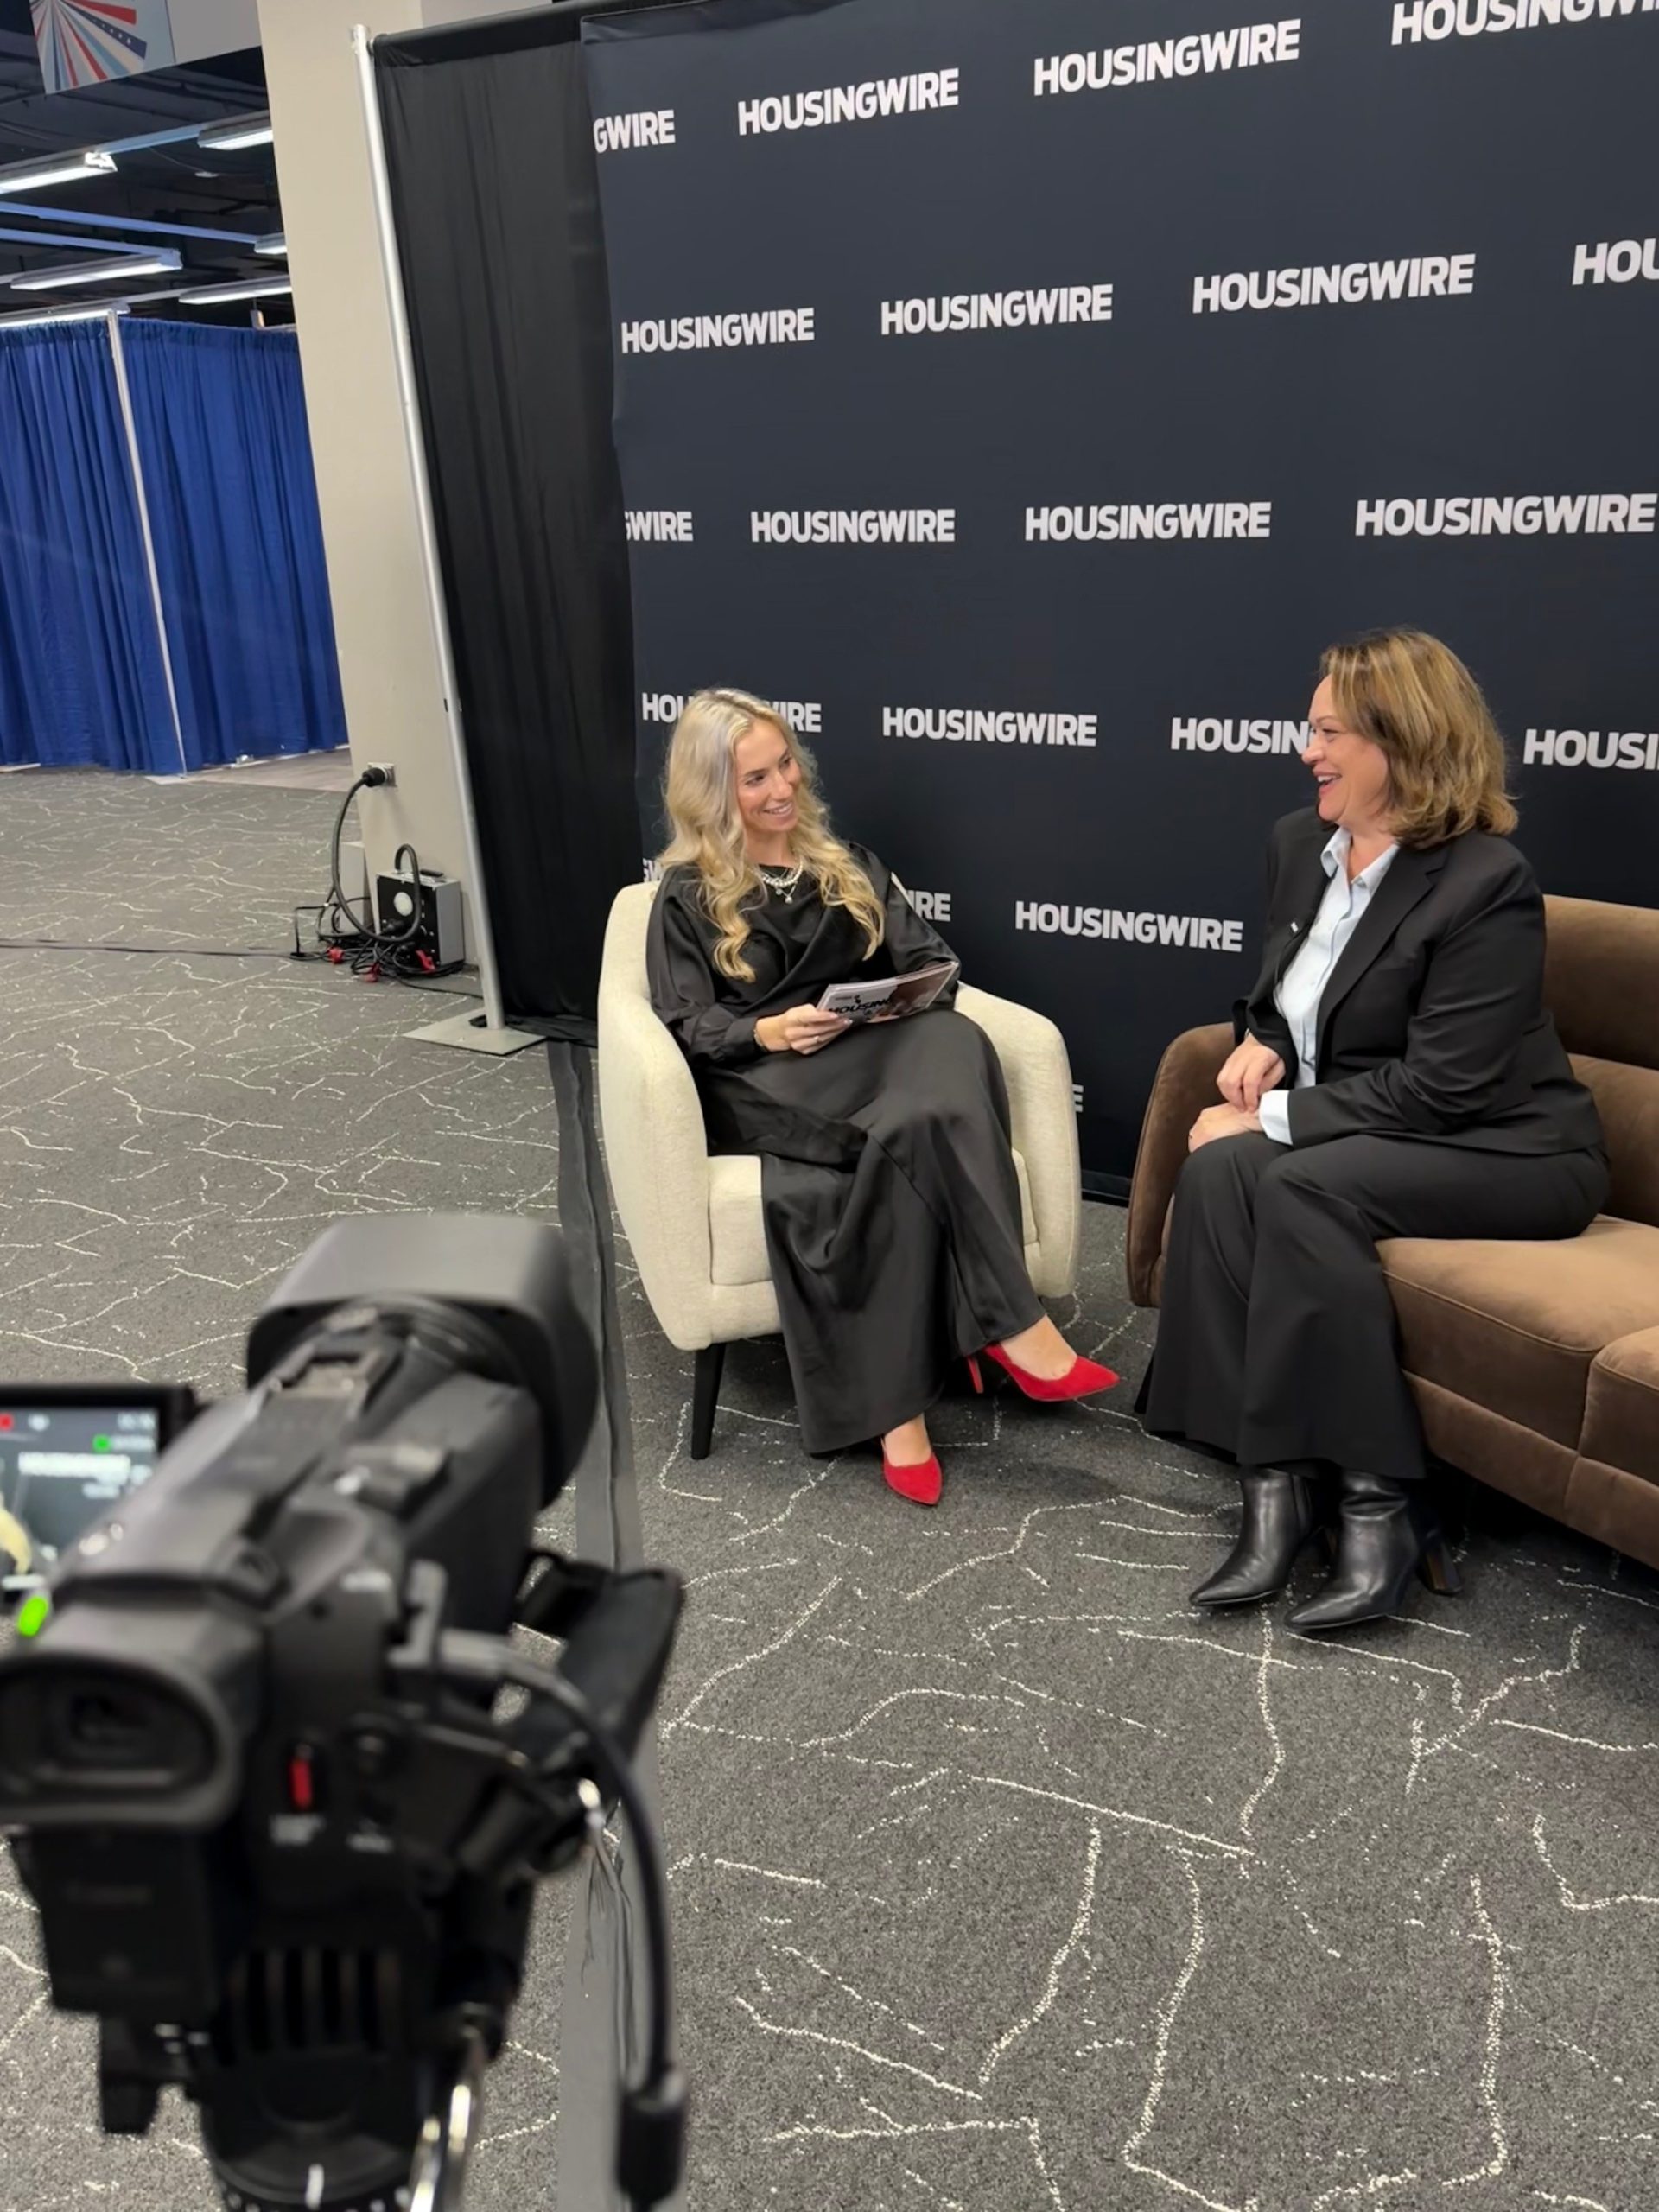
I also dug into these ideas further in my conversation with Allison LaForgia from HousingWire, including how modern scores are moving into underwriting, why lenders need the right data at the right time, and how new tools can help make the mortgage process work better for more people.
But as important as these advancements are, the question I keep coming back to is how we can help lenders make sound decisions while ensuring more consumers are fully seen.
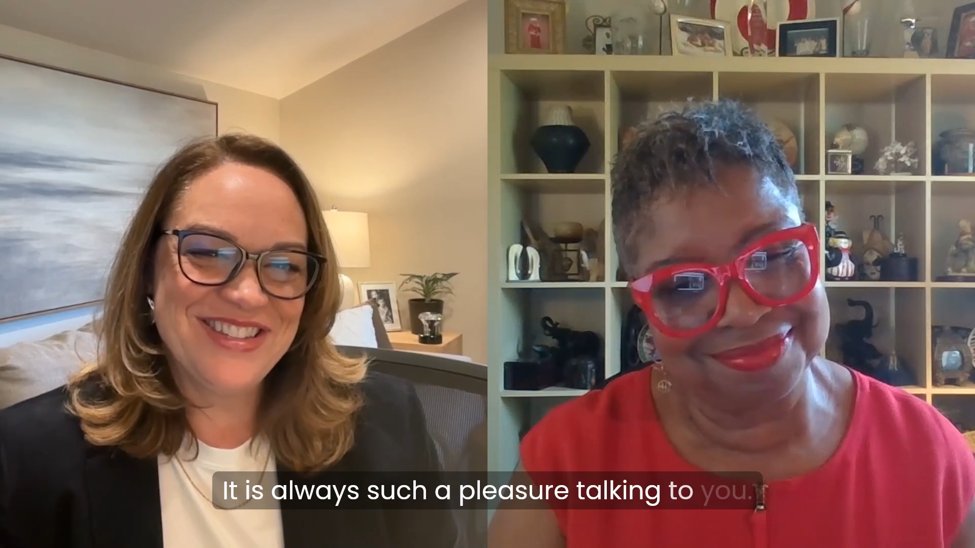
On this note, with my good friend Gwen Garnett from HomeFree-USA, we launched Experian’s Forward Focus program, which brings together different perspectives around timely issues impacting our industry today.
Gwen and I spoke about what affordability looks like from the perspective of real people, misconceptions that can keep people from exploring homeownership, and how organizations can work together to help more people on their journey.
You can watch our full conversation here or read more about our perspective in this HousingWire article.
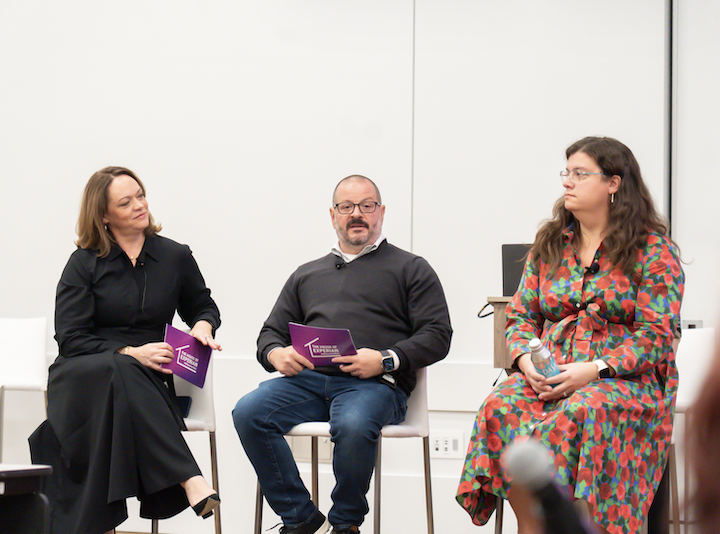
At the Out & Equal Summit, my colleagues Aaron Ricci and Emil Anderson and I discussed the distinct challenges LGBTQ+ individuals can face in their pursuit of homeownership, and how better information, financial education and access to the right tools can help address those challenges.
I also had an opportunity to step back and look at these issues through a broader lens during a conversation with Trish McFarlane on the HR Happy Hour podcast, recorded at the HR Technology Conference.
We talked about how data and technology are transforming everything from employment and income verification to mortgage underwriting, and why it’s important not to lose sight of the people behind those decisions.
Our recent integration with Workday is a great example. By making more employment and income information available through Experian Verify, we’re helping support important moments in people’s lives, whether they’re applying for a mortgage, renting a home or pursuing another financial opportunity. It’s a reminder that behind every verification is a real person trying to move something in their life forward.
Listen to our full conversation on HR Happy Hour.
While these conversations covered different topics, they kept bringing me back to the people behind the decisions. Someone working toward homeownership, pursuing a financial opportunity or taking another important step. Each person’s financial story goes beyond a single number.
That idea is at the heart of Experian’s new Beyond the Numbers campaign. We’ve spent years investing in expanded data and advanced analytics to help lenders build a more complete picture of consumers’ financial lives. Better information can help lenders make more informed decisions and recognize more of each consumer’s financial story. This campaign brings that story into focus.
Looking back on the past several weeks, I’m energized and optimistic about what’s ahead. There’s still a lot of work to do, but I’m encouraged by the progress we’re making.
Through advocacy, partnership and practical innovation, we can keep moving toward a mortgage system that works for more people.