As we enter May, a month dedicated to recognizing our U.S. Armed Forces, it’s only fitting to think about how we are honoring this special group of people.
Yes, there will likely be car deals, coupons, and even a few beautiful ceremonies, but as both lawmakers and leaders have recognized, these individuals and their families deserve protections every day. Especially in the financial services universe.
There should be no exorbitant fees. No excessively high interest rates. And when they are called to active-duty, they should have avenues to ease their financial commitments and/or exit out of lease agreements.
Thankfully, the Servicemembers Civil Relief Act (SCRA) and a strengthened Military Lending Act (MLA) were introduced to help.
In fact, we are in year one of the enhanced MLA Final Rule in which compliance was mandated by Oct. 3, 2016. The extended MLA protections include a 36% Military Annual Percentage Rate (MAPR) cap to a wider range of credit products, including payday loans, vehicle title loans, refund application loans, deposit advance loans, installment loans and unsecured open-end lines of credit. The cap additionally applies to fees tacked on for credit-related ancillary products including finance charges and certain application and participation fees.
The amended rule covers credit offered or extended to active-duty service members and their dependents, if the credit is subject to a finance charge or is payable by written agreement in more than four installments.
And finally, one of the most important additions is that creditors must verify active-duty and dependents at origination. Right now, this can be accomplished by either working with a bureau, like Experian, or by vetting lists directly with the Department of Defense’s (DOD) own database. To continue to help with client need, the bureaus are working with the DOD and financial institutions to ensure alignment in delivery of military member and dependent data for a consistent, immediate and accurate MLA verification process.
While much has been introduced over the past year to strengthen protections, there is still more to come. The compliance date for credit cards is Oct. 3, 2017.
To date, the MLA status of millions upon millions of consumer credit applications have been verified, ensuring our military members and their dependents receive the financial protections they are entitled to under law.
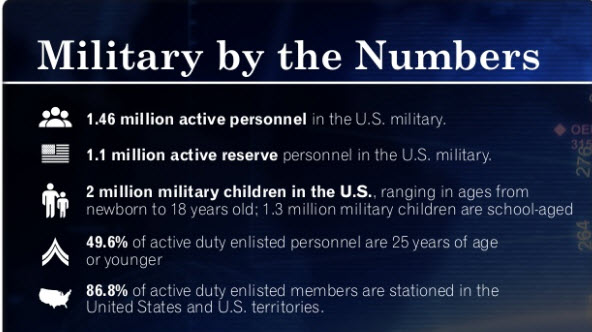
There are roughly 3.4 million military members and dependents in the MLA database, and this is an audience who sacrifices a great deal for our country. Thankfully, protections are finally being enforced to ensure they are taken care of too.