Exploring Affordability for First-time Homebuyers in the Florida Market

by Scott Hamlin 5 min read August 29, 2024

Housing affordability is a pressing concern across the United States, and Florida is no exception. The affordability issue can be particularly crucial for renters looking to become first-time homebuyers (FTHBs).

The desire to live in a sunny location must be measured against the cost of living, particularly housing costs. Experts at Experian Housing carefully examined data from the top 15 Florida cities (by population) to gain insights into the state of housing affordability in Florida.1 Experian examined factors such as mortgage payments, rent prices, income levels, and sales prices to assess affordability.

Overview of the Florida FTHB market

Experian Housing’s recent report on first-time homebuyers ranked Florida the state with the third highest percentage of FTHBs nationwide, at nearly 7.7% of FTHBs.2 It outranked New York, falling behind Texas and California.

In Florida, the younger populations of Generation Y and Z account for 60% of all first-time homebuyers. Nationwide, roughly 70% of FTHBs belong to these populations.

Among younger buyers, affordability is often the deciding factor in whether they continue to rent or become homeowners as they balance housing costs with student loan debt and other expenses.

Let’s look at some key metrics

Comparative monthly mortgage payments and rent prices

How this affects affordability:

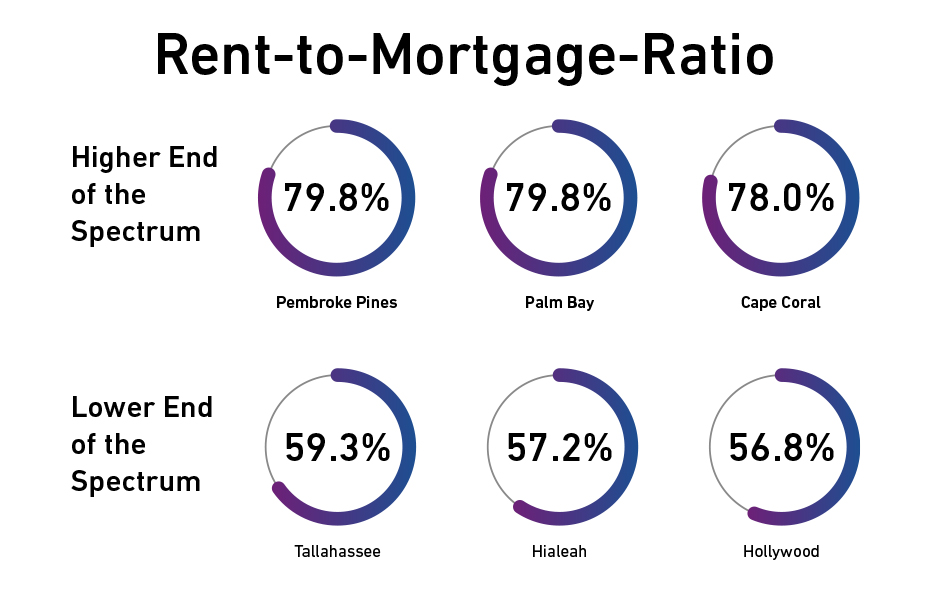
The bottom line for prospective homebuyers often comes down to whether it’s more affordable to continue to rent or purchase a home. While the metrics discussed all contribute to the picture of affordability, for this study, Experian Housing defined affordability by calculating the rent-to-mortgage ratio, a comparison of monthly rental payments to monthly mortgage payments. Homebuying becomes more attractive to renters when the rent-to-mortgage ratio is higher because mortgage payments are more economically practical.
What we observed:

Experian Housing found that Pembroke Pines, Palm Bay, and Cape Coral have the highest rent-to-mortgage ratio in Florida, at nearly 80%. In other words, for example, if the average mortgage payment is $1,000, the average rental payment is ~$800. Compare this to Tallahassee, Hialeah, and Hollywood, where the rent-to-mortgage ratio is <60%.

These numbers illustrate the varying home purchase and rental market trends across the state.

Debt-to-income

How this affects affordability:

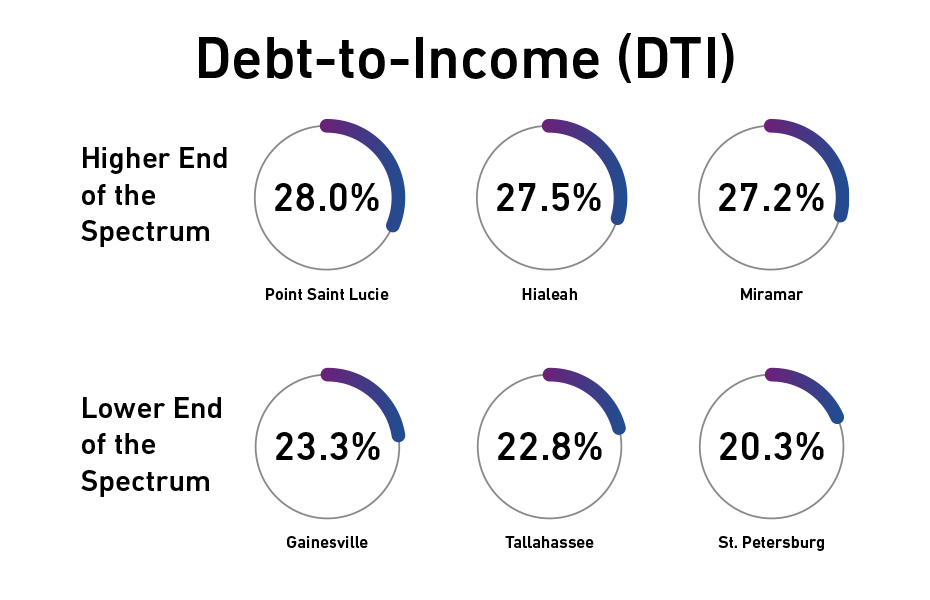
This metric compares monthly debt responsibilities, including mortgages, car loans, student loans, and minimum credit card payments, to monthly income. A high debt-to-income ratio indicates a significant portion of income is dedicated to paying debt, leaving little room for other essential living costs and discretionary spending.

What we observed:
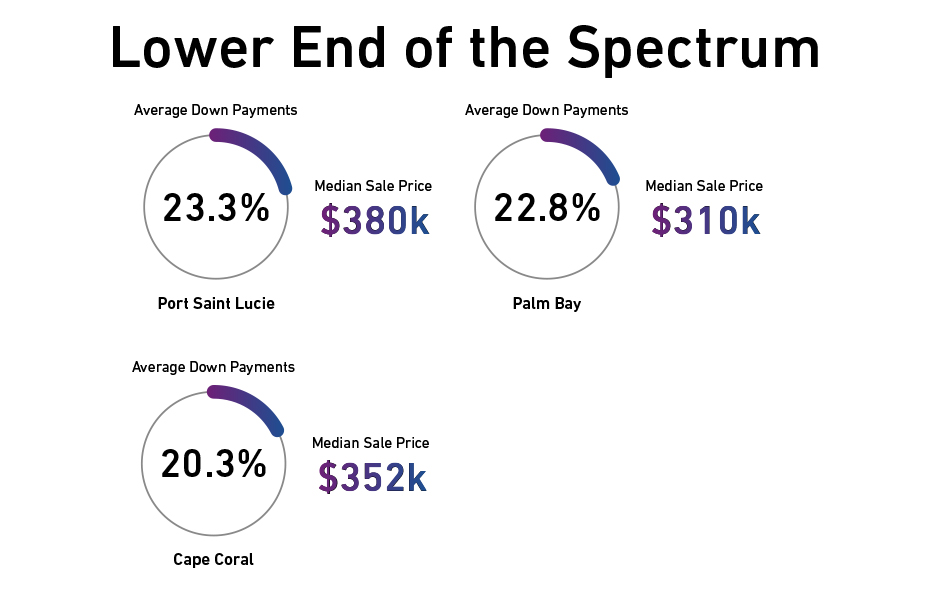
Down payments

How this affects affordability:

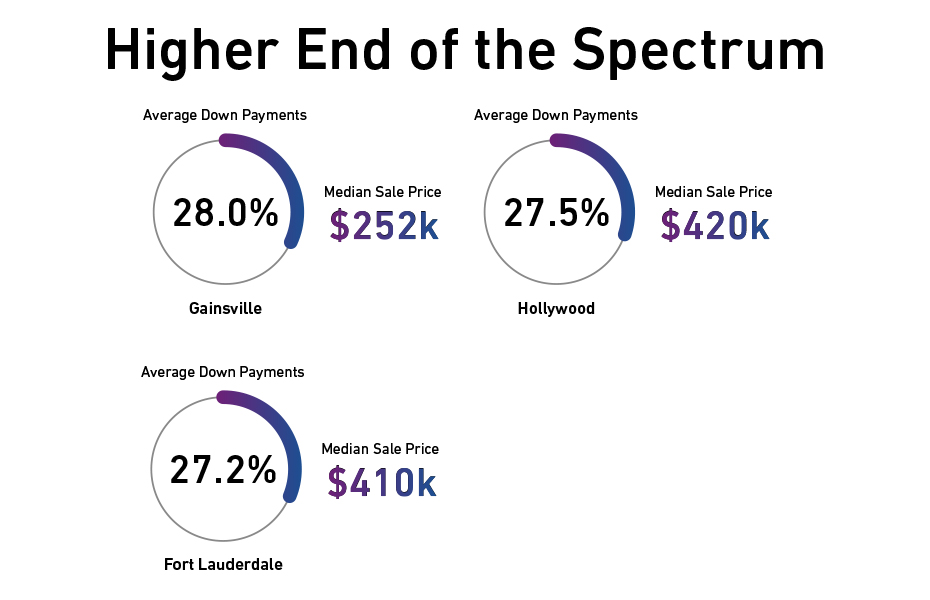
A higher down payment can also assist buyers, especially first-time buyers, by increasing attractive financing options. Importantly, a down payment of 20% avoids the need for private mortgage insurance (PMI), which is insurance for the lender, protecting the lender against loss should a foreclosure occur. PMI typically costs between 0.5% and 2% of the loan amount, annually.

What we observed:
Sale prices and financial hurdles

How this affects affordability:

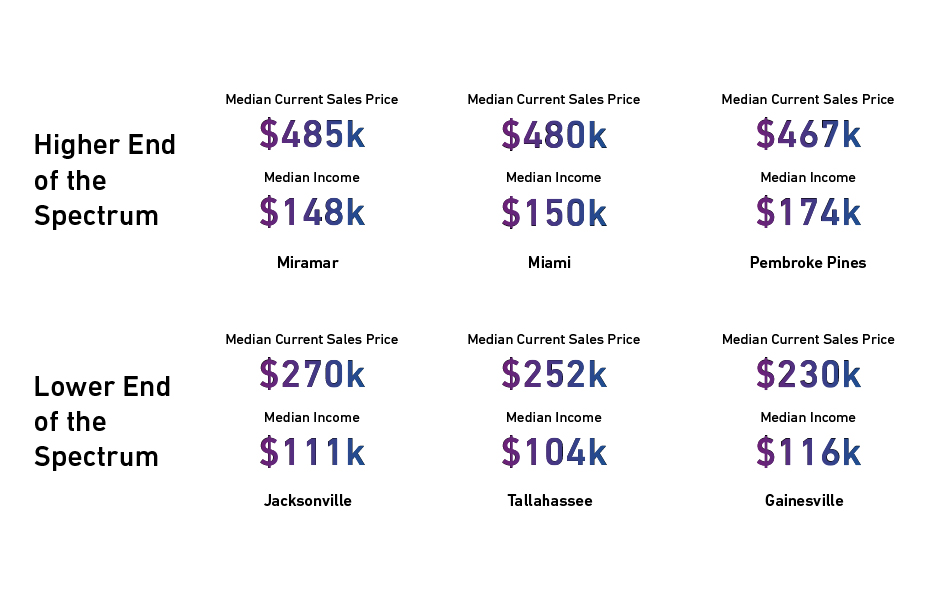
In comparing home affordability across Florida, first-time homebuyers should consider home prices in relation to income. While other considerations, including an individual’s debt level and other expenses, contribute to the bottom line, this gives an indication of how much income will be consumed by the home purchase.

What we observed:

Experian Housing examined the median sales prices and median. Comparison is essential because sales prices may be higher in a given area, but correlation with income helps determine affordability.
A Florida housing opportunity, up close: Miami metropolitan area

The Miami metropolitan area is an example of an area where mortgage lenders who understand their clients and the area they seek to live may well attract first-time homebuyers, loyal clients, and more word-of-mouth business.
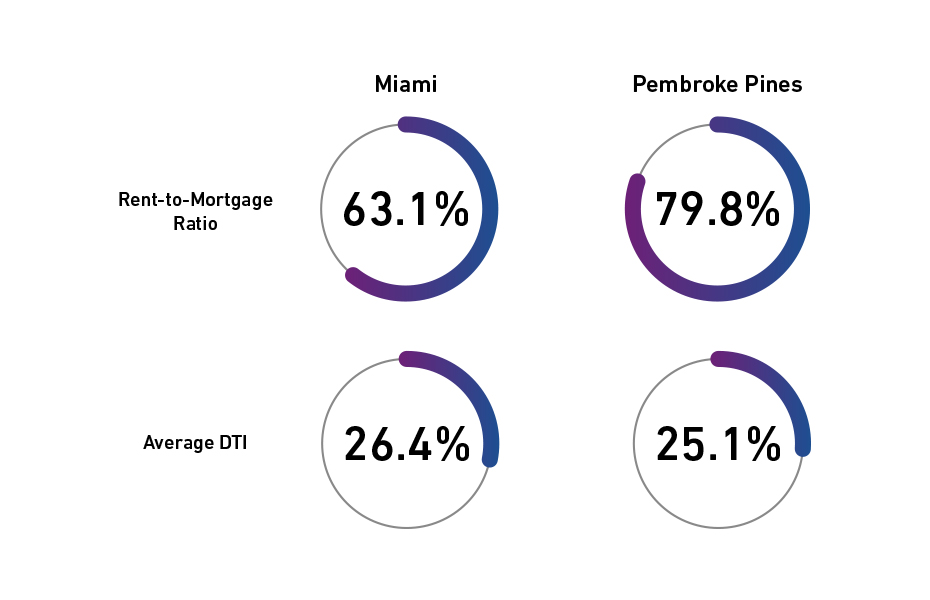
The Miami suburb of Pembroke Pines, roughly 20 miles from Miami, offers a more affordable housing market. With Florida sunshine, nearby beaches, and access to three main highways, mortgage lenders whose knowledge base is not limited to the Miami city center may have an opportunity to turn a renter into a homeowner.

Florida residents navigate the cost of living in the Sunshine State

Analysis from Experian Housing highlights the diversity in housing markets and the opportunities to enhance financial well-being for residents in Florida. These insights are crucial for lenders to identify affordable opportunities for all residents.

Experian’s data system offers unique value to lenders given the ability to take a more comprehensive look at a borrower’s financial behavior. Experian uses credit, property, rental, and other alternative data sources to capture the borrower profile. Access to such data also gives Experian a unique ability to conduct research for reports like this one and the recent Texas affordability study.

For more information about the lending possibilities for first-time homebuyers, download our white paper and visit us online.

Download white paper Learn more

1 The analysis is based on the trade and rental data reported to Experian and considered first-time homebuyers during the period between November 2022 and January 2024.

2 Based on those getting a mortgage.

Related Posts

Who’s Driving What? How Fuel Loyalty and Generational Preferences are Shaping the Vehicle Market

Take a look around at any road, parking lot, or highway, and you’ll see just how diverse today’s vehicle landscape has become. Within that evolving mix, electric vehicles (EVs) have seen years of rapid growth, and while the market is seemingly entering a new phase, interest remains. So, with several vehicles and fuel types to choose from, what keeps drivers coming back to electrified vehicles? Experian Automotive’s Automotive Market Trends Report: Q2 2026 found that among EV owners who returned to the market in the last 12 months, majority (72.2%) replaced their EV with another EV, while 18.5% switched to a gasoline vehicle. Hybrid buyers also showed considerable loyalty to electrification, with 55.7% of gas-hybrid owners staying with the same fuel type when replacing their vehicle, and 32.7% swapping for a gasoline vehicle. Consumers are seemingly remaining loyal to EVs and hybrids because they are attracted to the benefits that fit their everyday lifestyle, such as lower fuel or charging costs amid the elevated gas prices. For some, it could also be tied to convenience, as drivers who have found a reliable charging routine or appreciate the efficiency of a hybrid may have little reason to switch back to a traditional gasoline vehicle. Generations are taking different paths to electrification Generational differences also influence hybrid and EV loyalty, with younger consumers generally showing greater openness to alternative fuel types. While older generations tend to have greater familiarity with traditional gasoline vehicles, hybrid and EV adoption is increasing across all age groups as these options become more accessible and mainstream. Millennials, in particular, showed the strongest inclination toward electrified vehicles. Through Q2 2026, they accounted for the highest EV share at 8.2%, compared with Gen X at 5.5%, Gen Z (4.7%), and Baby Boomers (4.7%). The difference becomes even more pronounced when hybrids are in the mix, as 23.1% of Millennial registrations were gas-electric hybrids or plug-in hybrids, versus 16.7% for Gen X, 16.8% for Gen Z, and 18.0% for Baby Boomers. For automotive professionals, these differences make understanding who is driving what, and what they may choose next, increasingly important. The future of the automotive market may be less about consumers choosing one vehicle type over the other and more about understanding the distinct patterns and preferences of each generation. As the market continues to evolve, those insights can help automotive professionals better meet consumers where they are. To learn more about vehicle market trends, view the full Automotive Market Trends Report: Q2 2026 presentation on demand.

September 24, 2026 by John Howard
New Data Available for MBS Investors: Current Credit Score 

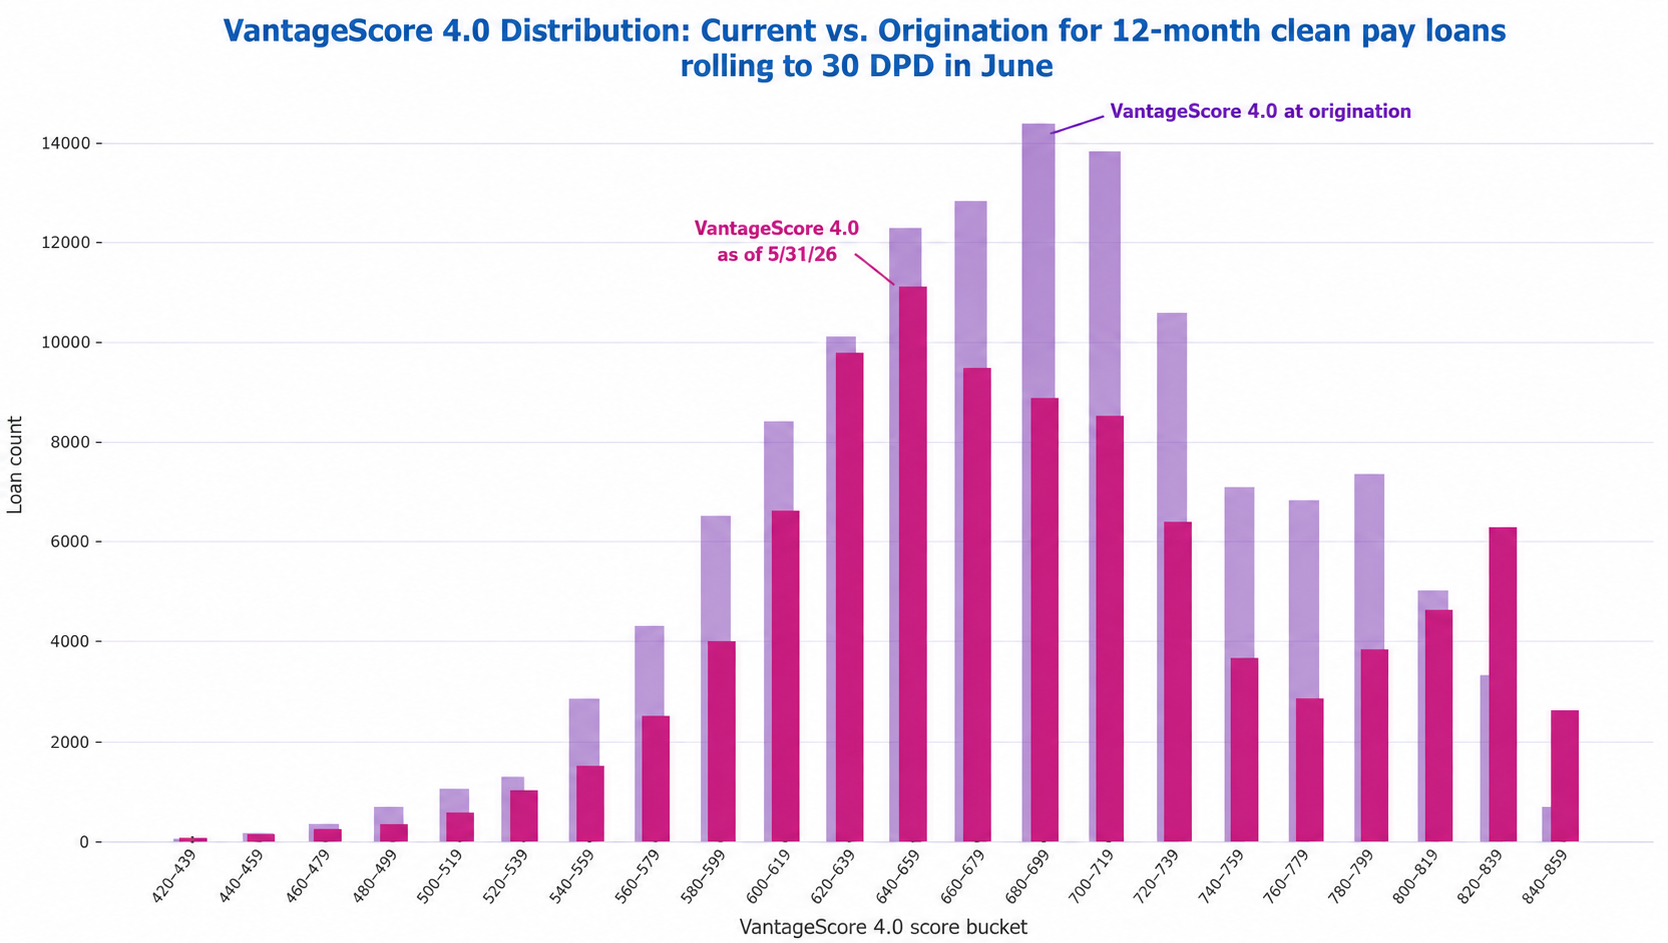
In a previous post, we described how every mortgage borrower’s financial situation and credit profile evolve over time.  After a borrower opens a loan, their financial status evolves—jobs are gained and lost; incomes can rise or fall, and financially stressful situations or windfalls can occur. These effects are often reflected in the consumer’s evolving credit score, which changes with the consumer’s payment behavior on open loans, credit inquiry activity, credit card utilization, and other revolving lines, among other things.    Even though MBS, whole loan, and MSR investors ultimately bear borrower credit risk, they may have access to less current borrower credit information than other participants in the mortgage ecosystem.   In securitized markets (both agency MBS and private-label MBS), updated scores are not provided in disclosure to bondholders, even as loans age year over year.  In whole loan and MSR markets, a single origination credit score is often provided at the time of bid, and after a successful bid, the investor may have a permissible purpose to pull individual scores on an owned portfolio. But until recently, there was no single loan-level dataset that included continuously refreshed credit scores across the U.S. mortgage market—the type of foundational dataset needed to build and tune credit and prepayment models.  A monthly-refreshed Current Credit Score field meets our three-pronged materiality standard for new data delivery to MBS markets:  New: Provides information not available in existing datasets (i.e., orthogonal to currently available data). Neither private-label MBS nor agency MBS standard market data includes a monthly-refreshed borrower credit score.  Material: Impacts a sizeable portion of the MBS universe. For the vast majority of loans in MBS, borrowers credit scores are available.  Significant: Differentiates collateral performance by a large enough margin to influence trading and risk management decisions.  A current credit score wraps all of a borrower’s credit-related behaviors into a single numerical value and has historically been associated with a borrower’s likelihood of becoming 60+ days past due on any obligation within the subsequent 24 months.    In fact, a current credit score is among the most informative indicators of near-term mortgage default risk, as shown in the image below, which depicts 30+ DPD rates by current credit score bands for the entire U.S. mortgage market, controlling for origination score <=650.    Without access to current credit scores, investors are limited to the score at origination—causing the four distinct performance trends shown here to appear as a single averaged line. In reality, score migration since origination reveals significant divergence in credit risk, with the lowest current-score bucket exhibiting a nearly 10 times higher 30+ DPD rate than the highest-score bucket in the latest period shown.  Source:  Experian Mortgage Loan Performance (MLP) dataset hosted on IVolatility DataDriven Platform  In this article, we’ll take a quick look at how score migration acts as an early predictor of a performing loan’s first roll into 30-day delinquent status.    MBS Investors’ Current Credit Score Blindspot: Solved   An MBS investor relying on standard market data and securitization remittance reports sees no sign of borrower stress until the subject mortgage loan in the securitization misses a payment and is reported at 30 days delinquent. Of course, in the vast majority of cases, a borrower begins struggling financially well before missing a mortgage payment:  The borrower may miss payments on other types of loans (credit card, auto loan, personal unsecured, or payday loans) as they prioritize their home and mortgage.  Outstanding balances on credit cards may grow as the borrower begins to make only minimum payments on revolvers.  The borrower may apply for additional credit cards, personal or payday loans   The borrower may apply to increase limits on existing credit cards as outstanding balance nears spending limit  All these stress-indicative behaviors result in a decreasing credit score, many months before the borrower misses their first mortgage payment. An MBS investor with access to each borrower’s current credit score, refreshed each month, can predict increased likelihood of default many months before the first missed mortgage payment—and is therefore at a major information advantage relative to the market generally.  Experian’s Mortgage Loan Performance (MLP) dataset contains thousands of fields describing mortgage performance from each borrower, loan, and property perspective, all refreshed monthly (including, amongst other things, new credit scores and refinance inquiry activity, loan performance on all types of debt, filed junior liens, and AVM values).   MLP is much more comprehensive than loan-level data provided by Freddie Mac, Fannie Mae, Ginnie Mae, and PLS data vendors in several ways:   Standard market datasets may not contain certain data elements that some market participants consider useful when evaluating mortgage prepayment or credit performance. Basic, critical fields such as the borrower’s current credit score and the current junior lien balance on the property are missing.    MLP contains borrower, loan, and property data fields spanning a broad portion of the mortgage universe, including Agency, Non-Agency, and Esoteric mortgage products (CES, HELOC, Reverse), including both securitized and non-securitized loans.   MLP enables full three-dimensional (borrower + loan + property) tracking with persistent keys for borrower (before and after refinancing), loan (in securities/deals even after exit due to payoffs or buyouts, including before and after MSR sales), and property.  This enables end-to-end analysis of each borrower’s (and property’s) mortgage experience throughout their credit lifecycle.  Is Downward-Trending Credit Score a Signal for Impending Delinquency?  MLP contains thousands of fields describing each loan, borrower, and property across all U.S. mortgages.  It allows for virtually unlimited segmentation and granular analysis.   For purposes of this illustrative article, we’ll take a high-level look at the entire U.S. mortgage market and perform a quick analysis to confirm intuition that a declining credit score provides a signal for higher likelihood of near-term mortgage delinquency.  Figure 1 illustrates the current pay status (as of 6/30) for the entire U.S. mortgage market, as contained in the MLP dataset, along with count, UPB and UPB-weighted Vantage 4.0 credit score for each bucket.  Figure 1  Source:  Experian Mortgage Loan Performance dataset  As illustrated in Figure 1, approximately 772,000 individual mortgage loans were reported to Experian as 30 days delinquent as of 6/30/2026.  Of the 772,000 30d delinquent loans in the June snapshot, approximately 426,000 were current in the prior (May) snapshot.  Some of these 426,000 loans were reperformers which had been bouncing from 30 DPD to current over the prior few snapshots. To remove reperformance score noise, we further parsed out the population which: 1) had rolled from current to 30 DPD from May to June; and 2) was consistently current for a full year prior to the 6/30 missed payment.  The population meeting both conditions totaled approximately 123,000 loans.  Figure 2 below shows, for this population of 123,000 “clean current” loans, the UPB-weighted average Vantage4 credit score for each of the 12 months leading up to the June missed payment, as well as the impact of the missed payment on the 6/30 score.  Figure 2  Source:  Experian Mortgage Loan Performance Dataset  Figure 2 reveals a rather slow and steady ~20-point deterioration of score in the 12 months prior to first missed payment – as well as the 80-point drop once the missed payment hits.  When we compare this cohort’s Vantage 4.0 score trend to the broader Current population across the entire dataset in Figure 3, we see a marked difference in both absolute value and trend:  Figure 3  Source:  Experian Mortgage Loan Performance Dataset  Not only is the cohort’s starting Vantage 4.0 score lower than the broader current population, but it also displays a dropping trend (with a notable 2 to 3x acceleration in monthly score drop the month before the first missed mortgage payment) while the broader Current population’s score (of which the isolated cohort is a subset) remains rock steady.  Lastly, we present Figure 4, a histogram comparing the distribution of at-origination and as-of 5/30 (i.e., the period just before the missed June mortgage payment) credit scores for the clean current population. The distribution appears to shift toward lower credit scores. To the extent credit scores are correlated with credit risk, this shift may indicate elevated credit risk relative to origination. Since this degradation occurs during a period of perfect mortgage pay performance, it is invisible to MBS investors who lack access to current borrower credit scores. Experian MLP provides monthly refreshed credit scores for mortgage borrowers contained within the MLP database.  Figure 4  Source:  Experian Mortgage Loan Performance Dataset 

September 22, 2026 by Michael Pyatski, Perry DeFelice
Ask the Expert: The Future of Lending Starts With Identity With Shawn Rife and Brian Cardona

Identity intelligence and alternative data can help lenders validate consumers and support more informed decisions across the customer lifecycle.

September 16, 2026 by Julie Lee

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe