Consumer behavior is constantly evolving — from the channels they prefer to the economic trends spurring varying interest and activity. It’s no surprise that businesses find it challenging to know what their customers want today or tomorrow. But knowing and understanding this information is essential to growing your bottom line. Through years of working with businesses across every vertical, we’ve found that a solid approach to growing your business revolves around your customers. The better you know your customers, the better you can achieve your goals.
Seeing the future.
How well can you identify and rank your current customer population? Are you leveraging that insight to acquire new customers, manage current customers and prioritize collections efforts? If so, you’re probably using custom models in your business strategy. But if your organization is like many businesses, you may use a more traditional approach. In our highly competitive market, strategy and decisions must be based on the right data and insights. No excuses. The data is there, and we can help you turn it into actionable insights. Implementing a custom model can maximize your return on investment and help you make more profitable business decisions — now and in the future.
No palm reading required.
Without visiting your local fortuneteller, you still can predict the future. You need a model, but not the “runway” type. What constitutes a highly predictive and effective model? Many factors. A highly predictive custom model should incorporate robust data, advanced modeling methodologies, analytical expertise and attributes. Having these foundational components is essential to knowing your customers and making confident decisions.
Models aren’t one-size-fits-all. When you take an innovative approach to model development, the model is targeted to support your specific business goals while providing the documentation required for regulatory reviews. Consider these items as you develop your custom model:
- Data — It all starts with the right data. Combining multiple data assets — your master-file data, our credit data and any additional data sources — is key to developing a robust model development sample. In other words, a model development sample should represent your future through-the-door population.
- Model design — To ensure the custom model is designed to help you achieve your specific goals, you’ll want to incorporate the latest analytics and modeling methodologies. An experienced analytics team will be essential here.
- Segmentation — With the right model development and segmentation strategies, you can identify optimal segments that will result in a more predictive custom model. This way, each consumer is scored on a scorecard developed using a credit profile similar to theirs.
- Validation — To ensure the model’s predictive ability and longevity, validate each custom model on a holdout sample and compare it with other scores to ensure it accounts for the current and future (through-the-door) consumer populations, as well as policy rule and behavioral changes.
- Regulatory review — Don’t forget about the documentation needed for compliance. While audits are unpleasant , fines and extensive scrutiny can significantly impact your business.
Take your fortunetelling to the next level.
Machine learning is all the rage. This cutting-edge technology can be embedded in your predictive models to help uncover patterns in data that may not be apparent otherwise. This can be done by comparing the performance of the machine learning model with your existing models. Once you know that machine learning can add the lift you’re looking for, you can apply that methodology to develop a custom model focused on stability, cost-efficiency, transparency and predictive performance.
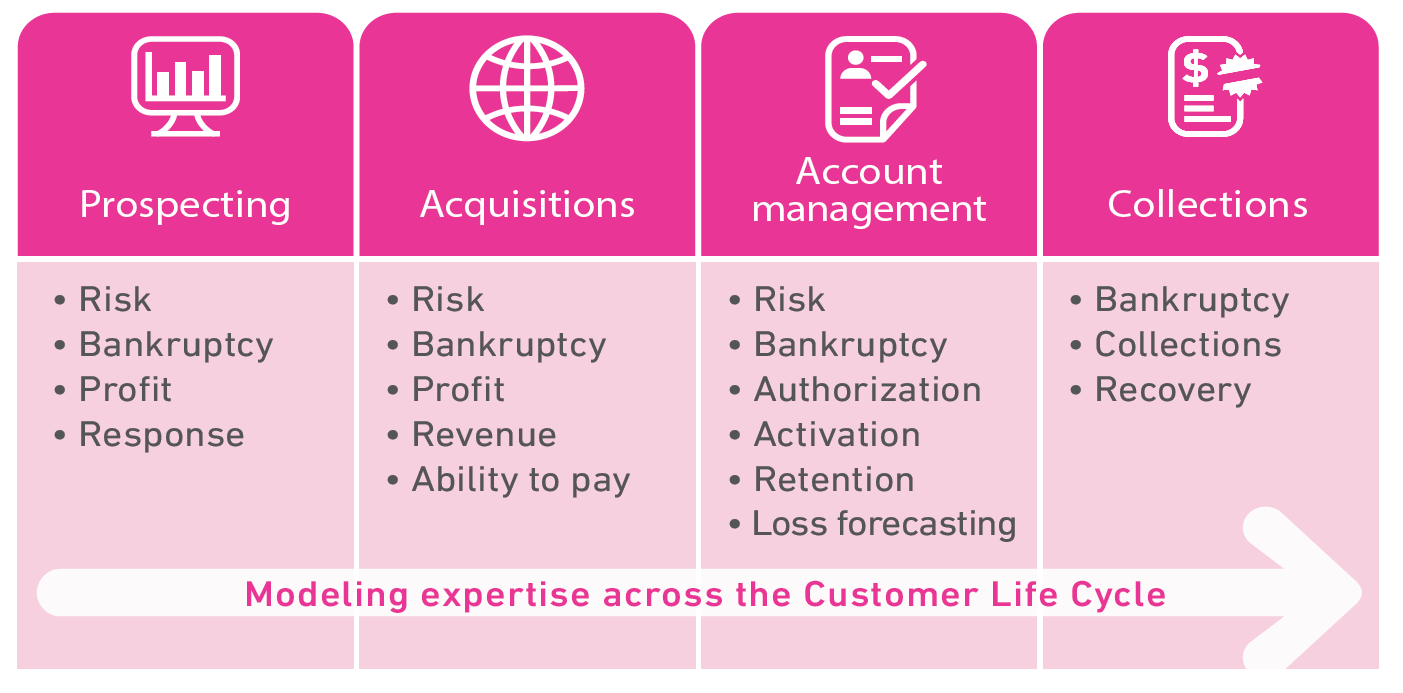
Predicting behavior across the Customer Life Cycle.
How can a custom model benefit you? From improving baseline performance and increasing profitability by approving more good accounts to uncovering opportunities within your target market, custom models can provide the confidence needed to grow your business. Which one of these models can help you achieve your business goals?
When it comes to accurately predicting customer behavior, you don’t need a crystal ball. You need a well-built, highly predictive custom model. Use the data that’s available to gain insight into your customers and grow your bottom line. If you need help, we’re here. We have the data, analytics and expertise to help you get started.


