Trended Attributes: Key to Segmentation Strategy Development

Updated: July 14, 2026 by Guest Contributor 3 min read February 19, 2018

Today’s consumer lending environment is more dynamic and competitive than ever, with renewed focus on personal loans, marketplace lending and the ever-challenging credit card market. One of the significant learnings from the economic crisis is how digging deeper into consumer credit data can help provide insights into trending behavior and not just point-in-time credit evaluation. For example, I’ve found consumer trending behavior to be very powerful when evaluating risks of credit card revolvers versus transactors. However, trended data can come with its own challenges when the data isn’t interpreted uniformly across multiple data sources.

To address these challenges, Experian® has developed trended attributes, which can provide significant lift in the development of segmentation strategies and custom models. These Trended 3DTM attributes are used effectively across the life cycle to drive balance transfers, mitigate high-risk exposure and fine-tune strategies for customers near score cutoffs.
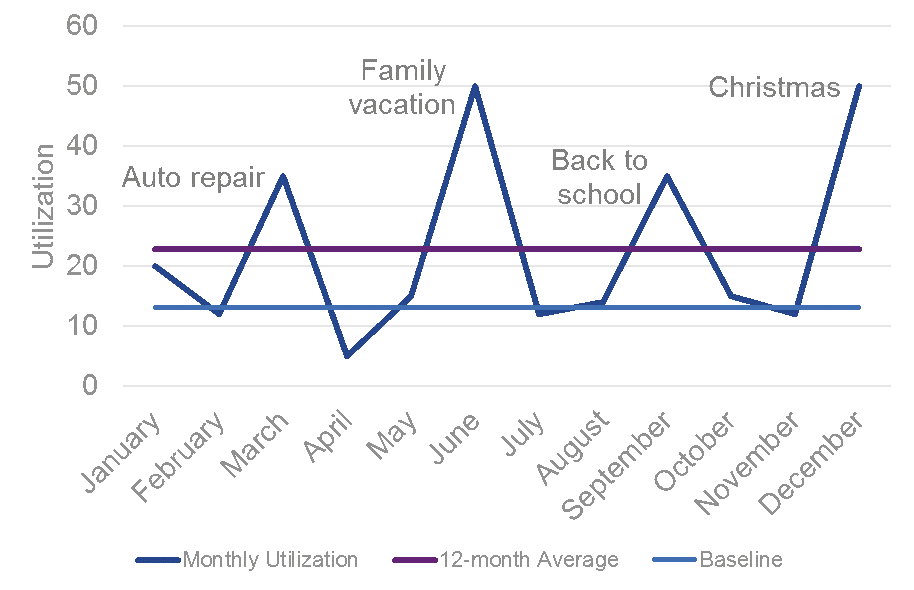
One of the things I look for when exploring new trended data is the ability to further understand payment velocity. These characteristics go far beyond revolver and transactor flags, and into the details of consumer usage and trajectory. As illustrated in the chart, a consumer isn’t easily classified into one borrowing persona (revolver, transactor, etc.) or another — it’s a spectrum of use trends. Experian’s Trended 3D provides details needed to understand payment rates, slope of balance growth and even trends in delinquency. These trends provide strong lift across all decisioning strategies to improve your business performance.

In recent engagements with lenders, new segmentation tools and data for the development of custom models is at the forefront of the conversation. Risk managers are looking for help leveraging new modeling techniques such as machine learning, but often have challenges moving from prior practices. In addition, attribute governance has been a key area of focus that is addressed with Trended 3D, as it was developed using machine learning techniques and is delivered with the necessary documentation for regulatory conformance. This provides an impressive foundation, allowing you to integrate the most advanced analytics into your credit decisioning.

Alternative data isn’t the only source for new consumer insights. Looking at the traditional credit report can still provide so much insight; we simply need to take advantage of new techniques in analytics development. Trended attributes provide a high-definition lens that opens a world of opportunity.


Related Posts

What Is a Third-Party Breach? How to Prepare for and Respond to Vendor Incidents

Learn what a third-party breach is and steps to prepare, contain risk, and support affected customers. Read more!

November 9, 2026 by Laura Burrows
Mortgage Underwriting Moves from Modernization Talk to Action 

Mortgage underwriting is entering a new phase. In a recent conversation with HousingWire’s Allison LaForgia, Michele Bodda, Group President of Experian Housing, Verification Solutions, and Employer Services, discussed how modern credit scores, alternative data and verification tools are changing how lenders evaluate borrowers.  Lenders can now judge modernization by its results, Bodda said. “Now we’re actually letting more modern scores get into underwriting to help price loans and go all the way through to securitization,” she told HousingWire. “We’re letting the scores and the data actually speak for itself instead of just talking about it.”  The Right Data at the Right Time  Modernizing underwriting means providing useful information at the right stage, rather than giving lenders everything at once. “You don’t need everything all at once. You don’t need everything on initial pull,” Bodda said.  Alternative data, such as rental payments and buy now, pay later activity, can help show how consumers manage obligations, especially those with thinner credit files. A thin credit file does not necessarily mean someone has a thin financial life.  “It’s our responsibility as one of the primary data providers to make sure we can make all of that available, so that we’re best representing the consumer,” Bodda said. A fuller view of data may help lenders identify creditworthy applicants who might otherwise be difficult to assess.  Simplifying Verification and Reducing Friction  Bodda also shared how Experian is making credit information more easily accessible and reducing unnecessary costs during the originations process, explaining that new enhancements to Experian’s Power Profile Plus allow lenders to pull credit data at the start of underwriting and request another score later without repurchasing the data.  “You can pull it later and not pay for the credit data again,” Bodda said.   Experian is also investing in income and employment verification, including through a new partnership with Workday. Bodda explained that Experian will continue to focus on process improvement, competition and innovation across the mortgage ecosystem.  A Broader Path to Homeownership  As consumer expectations and underwriting capabilities evolve, borrowers want a process that reflects their financial lives, while lenders seek greater efficiency. Modern scores, relevant data, and streamlined verification can help lenders assess applications with more context—and may help more people pursue homeownership.  “If we as an industry can open this up and bring more people into the process, then we’re going to thrive,” Bodda said in the interview.   Watch the interview and hear all of Michele’s insights, and more here.  

November 6, 2026 by Caroline Basile
How to Deliver Data-Driven Customer Experiences

A data-driven credit customer experience offers personalization and low friction — it's a win-win for consumers and businesses.

November 5, 2026 by Zohreen Ismail

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe
