According to the June 23rd, 2026 Commercial Pulse Report, the U.S. Leisure & Hospitality sector is posting some of the strongest demand numbers in recent memory. For Chief Risk Officers, that headline warrants a closer look — because the same conditions driving growth are also concentrating risk in ways that deserve careful portfolio attention.
Watch the Commercial Pulse Update
Travel Demand Is Elevated — and Event-Dependent
Consumer travel activity is running at record levels. AAA projects 72.2 million Americans will travel during the Independence Day holiday period in 2026, and much of the sector’s current momentum is receiving a significant lift from two non-recurring catalysts: the 2026 FIFA World Cup and America’s 250th anniversary celebrations.
This distinction matters for risk modeling. Demand supported by one-time events is not the same as structural demand growth. CROs should consider how their Leisure & Hospitality exposures are positioned for the period after these tailwinds dissipate — particularly for operators whose expansion or renovation financing was underwritten against current booking volumes.
Employment Recovery Masks Underlying Labor Volatility
Leisure & Hospitality employment has surpassed its pre-pandemic peak, with more than 17 million Americans now working in the sector. On the surface, this signals a full recovery. The unemployment rate tells a different story.
The sector’s unemployment rate stands at 5.8%, compared to the national rate of 4.3%, a 135 basis point gap that reflects structural labor volatility rather than isolated disruption. Elevated turnover, persistent hiring challenges, and wage pressures during peak periods are ongoing operational realities for most businesses in this space. For lenders assessing borrower capacity, workforce stability is a meaningful underwriting variable that headline employment figures alone do not capture.
Cost Pressures Are Compressing Margins Across the Sector
Rising operating costs represent the most immediate risk to credit performance within the sector.
The Travel Price Index increased 9.8% year over year — more than double the broader Consumer Price Index — with fuel costs rising more than 40% compared to a year ago. These increases affect every segment: airlines absorbing higher fuel expenses, hotels managing increased labor and food costs, and transportation operators facing dual pressure from both.
For portfolio managers, the practical implication is margin compression. Businesses that were underwritten at prior cost structures may be operating with meaningfully less financial cushion than their original credit profiles reflected. This is particularly relevant for borrowers carrying variable-rate debt or those in capital-intensive subsectors where operating leverage amplifies the impact of cost increases.
Rising Credit Inquiries: Confidence or Pressure?
Experian data shows average commercial credit inquiries per business within Leisure & Hospitality increased from 0.07 to 0.21 between January 2023 and early 2026 — a 181% increase.
This figure requires careful interpretation. Rising inquiry activity can signal business confidence and investment-driven borrowing. It can equally reflect businesses seeking liquidity to manage elevated operating costs. Without visibility into the composition of that inquiry volume, both readings are plausible.
What the data does confirm is that businesses in this sector are accessing credit markets at a significantly higher rate than three years ago. For lenders with concentrated Leisure & Hospitality exposure, this trend warrants monitoring — particularly if inquiry growth is outpacing revenue growth at the borrower level.
A significant portion of current inquiry activity appears tied to hotel development and renovation projects, which carry longer payback periods and greater sensitivity to demand normalization post-event cycle.
Credit Performance Is Stable — With an Important Caveat
Overall commercial credit performance across Leisure & Hospitality subsectors remains stable, and commercial credit scores have held relatively steady despite the cost environment. This is a genuine positive signal.
The caveat is one CROs will recognize: this sector’s delinquency rates are structurally more volatile than those of less cyclical industries. Stability in the current environment does not mean insensitivity to deterioration. Leisure & Hospitality borrowers tend to move faster in both directions — and the combination of event-driven demand, margin compression, and elevated inquiry activity creates conditions where credit quality could shift more abruptly than current scores suggest.
Periodic portfolio stress-testing against a demand normalization scenario — particularly for hotel and transportation-sector exposures — is a reasonable precaution given current conditions.
The Broader Environment Adds Context
Business bankruptcies reached 25,960 in Q1 2026, the highest quarterly level in more than a decade, while more than 524,000 new businesses launched in May alone. The co-existence of elevated bankruptcies and strong new business formation reflects a bifurcated economy: well-capitalized operators are expanding while undercapitalized ones are exiting.
This dynamic is likely playing out within Leisure & Hospitality as well. Concentration in stronger credits may be masking deterioration at the tail of the portfolio. CROs should ensure their monitoring frameworks are sensitive to borrower-level performance, not just sector-level aggregates.
The Risk Management Takeaway
The Leisure & Hospitality sector is genuinely performing well by most measures, and the demand environment is real. But several features of the current picture — event-dependent volume, structural labor volatility, significant cost inflation, and a sharp rise in credit inquiry activity — warrant active rather than passive portfolio management.
The questions worth asking now:
How much of your Leisure & Hospitality exposure was underwritten against demand levels that include non-recurring event tailwinds?
Which borrowers in the portfolio carry the most sensitivity to continued fuel and labor cost increases?
Does your current monitoring cadence reflect the higher delinquency velocity this sector historically exhibits?
Strong demand conditions are the right time to stress-test assumptions — not after conditions change.
Learn more
- ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis.
- ✔ Subscribe to our YouTube channel for regular updates on small business trends.
- ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow.
Related Posts
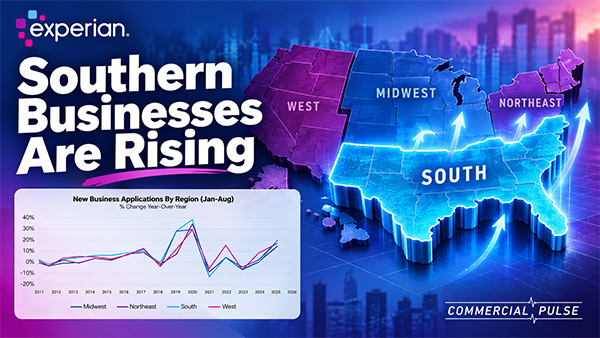
Small business formation remains one of the more notable trends in the U.S. economy. In August 532,000 new businesses launched across the country. While that was down from July, it remained well above historical averages. Since July 2020, an average of 455,000 new businesses have opened each month—56% higher than the pre-pandemic monthly average in 2018 and 2019. But the national numbers only tell part of the story. Watch The Commercial Pulse Update Experian’s latest Commercial Pulse report analysis examines where this growth is occurring and what it means for the commercial credit market. The data show that the South has emerged as an important center of small-business growth. And the businesses driving that expansion tend to have a different profile from their counterparts in other regions. For commercial lenders, understanding those differences can provide valuable context when evaluating new opportunities, credit demand and portfolio risk. Business growth is shifting geographically New business formation has increased across all U.S. regions, but the pace has not been uniform. Prior to 2018, regional differences in growth were relatively modest. During the pandemic years of 2020 and 2021, the South led the country in new business application growth. Since 2022, the West has posted the strongest growth, while the South continues to account for the greatest volume of new business openings. One factor providing context for that growth is population. The population of the South has grown more than 7% since 2019. Since 2020 alone, the region has added more than 3.6 million residents, outpacing every other U.S. region. Meanwhile, populations in other parts of the country declined between 2020 and 2022 before beginning to recover. Business formation and population movement do not necessarily have a simple cause-and-effect relationship. But their parallel growth highlights how the geographic makeup of both consumers and businesses has been changing. Credit-active businesses are growing even faster in the South The shift becomes even clearer when looking at businesses using commercial credit. Experian data shows the number of credit-active businesses in the United States has increased 55% since 2018. Every region participated in that expansion, but the South experienced the greatest growth at 70%, followed by the North at 52%, West at 50% and Midwest at 36%. The South now represents approximately 39% of U.S. credit-active businesses. It also accounted for more than 40% of newly opened commercial accounts in 2026, compared with 37% in 2019. For commercial credit organizations, that means the South represents not just a growing population of businesses, but an increasingly significant share of businesses participating in the commercial credit ecosystem. Southern businesses tend to be smaller and younger The composition of this growth is just as important as its scale. Credit-active businesses in the South and West tend to skew smaller and younger than those in the North and Midwest. In the South, 53% of businesses generate less than $500,000 in annual revenue, while 59% have fewer than five employees. Only 36% have been operating for more than 10 years, compared with 43% in the Midwest. Those characteristics can influence how businesses interact with credit. A younger business, for example, may have had less time to establish multiple commercial credit relationships. That pattern appears in Experian’s data. Across the United States, the average number of commercial credit accounts per business has declined from approximately 1.8 in 2018 to 1.5 in 2026. The South experienced the steepest decline and currently has the fewest accounts per business. At the same time, commercial credit inquiries have increased since 2023, most recently peaking in early 2026. Inquiry rates have typically been higher in the Midwest and South. The combination of fewer existing accounts and elevated inquiry activity provides useful context for lenders seeking to understand the credit needs of a growing population of younger businesses. Credit utilization tells another part of the story Regional differences also appear after businesses establish credit relationships. Businesses in the Midwest and North opening new commercial accounts tend to receive higher lines than businesses in the South and West. At the same time, businesses in the South show higher commercial card utilization despite carrying somewhat lower average balances. Experian’s analysis points to lower credit lines as an important factor behind that relationship. These trends reinforce why looking beyond a single credit metric can be important. Higher utilization, for example, can take on additional context when considered alongside credit-line size, business age, balances and regional business formation. Growth brings opportunities—and risk factors to monitor Despite significant growth and changes in business composition, regional credit performance has remained relatively steady. Commercial delinquencies across all regions are near pre-pandemic levels, while commercial credit risk scores have been relatively stable. There are regional differences worth monitoring, however. Businesses in the South have lower average commercial credit scores than businesses in the other regions analyzed, and delinquency rates tend to be higher in the North and South than in the Midwest and West. The broader takeaway is not simply that there are more small businesses in the South. It is that the composition of the commercial market is evolving alongside that growth. The South represents a growing share of credit-active businesses and new commercial accounts. Many of those businesses are younger, smaller and have fewer established commercial credit relationships. Their credit needs and behaviors may therefore differ from those of more mature businesses in other parts of the country. For commercial lenders and risk leaders, understanding those distinctions can help provide greater context around acquisition, underwriting and portfolio management decisions. As small business formation continues, Experian will continue monitoring where that growth is occurring—and how the changing business landscape is showing up in commercial credit behavior. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Where are small businesses growing in the U.S.? Experian data points to significant growth in the South. While new business formation has increased across the country, the South has consistently recorded the highest volume of new business openings and has seen the number of credit-active businesses grow 70% since 2018—compared with 55% nationally. Where are small businesses growing the most? The South has consistently had the largest volume of new business openings. The South led application growth during 2020–2021, while the West has posted the strongest growth rates since 2022. That distinction is important because it prevents the SEO headline from overstating what the data shows. Why has small business growth been so strong in the southern U.S.? The South has added more than 3.6 million residents since 2020, substantially outpacing other regions. Our report establishes a correlation rather than causation. Related Posts
Explore Experian insights on U.S. manufacturing investment, AI and automation adoption, employment trends, and commercial credit performance.
Experian’s latest Commercial Pulse analysis examines these trends using retail spending data alongside Experian commercial credit data.