There is a large and largely overlooked segment of small business borrowers sitting inside every commercial lender’s consumer portfolio right now. They are carrying balances that rival commercial card averages, they are running active businesses, and they have never been offered a commercial credit product. Experian’s latest research puts a number on the opportunity: $195 billion in outstanding consumer card balances held by business owners who carry no business card at all.
That figure is not a market estimate or a projection. It is a direct measurement from Experian’s consumer and commercial credit bureaus. And it represents one of the most actionable conversion opportunities in commercial lending today.
Watch the Commercial Pulse Update
Personal Financing Is the Default — Not the Exception
Before a small business owner ever walks through the door of a commercial lender, the data shows they have already been funding their operations for some time — on their own terms and from their own pockets.
A recent survey of 1,000 business owners conducted by Hometap.com found that more than 87% report using some form of personal funds to finance their business. The breakdown is instructive. Personal savings account for 67% of initial financing. Loans from friends and family represent 13.4%. Home equity products — HELOCs, refinancing, and home equity investments — account for 6.9%. Together, these three sources tell a consistent story: small business owners are drawing on personal assets and personal relationships long before they access the commercial credit system.
This is not simply a behavioral preference. For many small business owners — particularly sole proprietors and early-stage firms — the commercial credit system has not been structured to reach them. In early 2026, 93% of new business formations are sole proprietors, up from 85% in 2018. New business formations reached 524,000 in May alone, continuing a post-pandemic surge that has averaged 451,000 new businesses per month since July 2020 — 54% above the pre-pandemic pace. The volume of new, small, and often unbanked commercial borrowers entering the market is accelerating. The commercial credit infrastructure serving them has not kept pace.
The Consumer Card as a Commercial Instrument
The $195 billion figure deserves closer examination because it reveals something important about borrower behavior. Business owners who carry only consumer cards — no business card of any kind — have average outstanding balances of $8,996. That is approximately 62% higher than the average balance of a consumer without a business. These borrowers are not using their personal cards for personal spending at typical consumer levels. They are using them to run their businesses.
Their credit behavior mirrors that of commercial borrowers. Their balance levels are comparable to commercial card averages. What distinguishes them is not their creditworthiness or their intent — it is simply that no commercial product has been extended to them.
For commercial lenders, this population represents a clearly defined and data-identifiable target segment. Experian’s combined consumer and commercial data infrastructure makes it possible to identify business owners carrying consumer balances at commercial scale — and to assess their creditworthiness for a transition to business credit products. The conversion pathway exists. The data to execute it exists. The question is whether lenders are prioritizing it.
How the Commercial Credit Mix Is Shifting
For business owners who have crossed over into commercial credit, the product mix follows a predictable and well-documented pattern — one that has important implications for lender strategy.
Commercial credit cards dominate, accounting for more than 78% of monthly originations. Small business card spend is growing at an estimated 9.5% compound annual growth rate and is projected to surpass $1.06 trillion by year-end 2026. Cards are the entry product, and for the smallest and youngest businesses, they often remain the primary product indefinitely.
Higher-limit products — term loans, lines of credit, and business leases — account for roughly 18% of originations, and that share is growing. Average outstanding balances have expanded across every product category since 2023. Commercial card balances are up 19%. Lines of credit are 31% above 2023 levels. Business leases are the standout, with 2026 average outstanding balances running 83% higher than 2023. Equipment and asset-backed financing is accelerating, particularly among more mature businesses in capital-intensive industries such as Public Administration, Mining, and Educational Services.
Fintech lenders are capturing meaningful share in term loans and lines of credit, driven by faster decisioning, digital-first applications, and broader qualification criteria. The trade-off for borrowers is real — fintech products typically carry higher rates — but speed and accessibility are winning business that traditional lenders are not competing for effectively.
The Risk Picture and the Strategic Imperative
The commercial credit portfolio is performing well in aggregate, but the nuances matter. Term loans carry the highest 91-plus days past due rates across product types, though those rates have been improving. Commercial cards show the lowest delinquency levels but the highest charge-off rates — a combination that warrants ongoing monitoring. Business bankruptcies reached 25,960 in Q1 2026, the highest quarterly total since 2016, underscoring the importance of disciplined underwriting even as origination appetite grows.
The strategic imperative for commercial lenders is clear. Tightening credit standards is appropriate in this environment. But overly restrictive policies can carry their own cost: they push creditworthy small business owners further into personal credit products, deepen their reliance on consumer cards, and widen the gap between what borrowers need and what commercial lenders offer.
The $195 billion sitting in consumer card balances is not simply a market opportunity. It is a signal about where the commercial credit system is falling short — and where data-driven lenders have the greatest room to grow.
Go Deeper with Experian
The Commercial Pulse Report from Experian covers the full landscape of small business financing — including origination trends, balance growth, product segmentation by industry and business age, delinquency and charge-off data, and the macroeconomic context shaping commercial credit demand.
Learn more
- ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis.
- ✔ Subscribe to our YouTube channel for regular updates on small business trends.
- ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow.
Related Posts
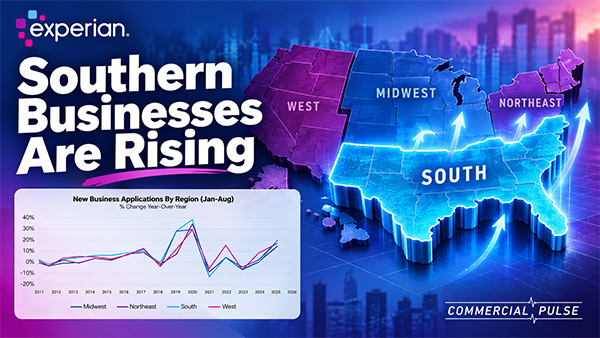
Small business formation remains one of the more notable trends in the U.S. economy. In August 532,000 new businesses launched across the country. While that was down from July, it remained well above historical averages. Since July 2020, an average of 455,000 new businesses have opened each month—56% higher than the pre-pandemic monthly average in 2018 and 2019. But the national numbers only tell part of the story. Watch The Commercial Pulse Update Experian’s latest Commercial Pulse report analysis examines where this growth is occurring and what it means for the commercial credit market. The data show that the South has emerged as an important center of small-business growth. And the businesses driving that expansion tend to have a different profile from their counterparts in other regions. For commercial lenders, understanding those differences can provide valuable context when evaluating new opportunities, credit demand and portfolio risk. Business growth is shifting geographically New business formation has increased across all U.S. regions, but the pace has not been uniform. Prior to 2018, regional differences in growth were relatively modest. During the pandemic years of 2020 and 2021, the South led the country in new business application growth. Since 2022, the West has posted the strongest growth, while the South continues to account for the greatest volume of new business openings. One factor providing context for that growth is population. The population of the South has grown more than 7% since 2019. Since 2020 alone, the region has added more than 3.6 million residents, outpacing every other U.S. region. Meanwhile, populations in other parts of the country declined between 2020 and 2022 before beginning to recover. Business formation and population movement do not necessarily have a simple cause-and-effect relationship. But their parallel growth highlights how the geographic makeup of both consumers and businesses has been changing. Credit-active businesses are growing even faster in the South The shift becomes even clearer when looking at businesses using commercial credit. Experian data shows the number of credit-active businesses in the United States has increased 55% since 2018. Every region participated in that expansion, but the South experienced the greatest growth at 70%, followed by the North at 52%, West at 50% and Midwest at 36%. The South now represents approximately 39% of U.S. credit-active businesses. It also accounted for more than 40% of newly opened commercial accounts in 2026, compared with 37% in 2019. For commercial credit organizations, that means the South represents not just a growing population of businesses, but an increasingly significant share of businesses participating in the commercial credit ecosystem. Southern businesses tend to be smaller and younger The composition of this growth is just as important as its scale. Credit-active businesses in the South and West tend to skew smaller and younger than those in the North and Midwest. In the South, 53% of businesses generate less than $500,000 in annual revenue, while 59% have fewer than five employees. Only 36% have been operating for more than 10 years, compared with 43% in the Midwest. Those characteristics can influence how businesses interact with credit. A younger business, for example, may have had less time to establish multiple commercial credit relationships. That pattern appears in Experian’s data. Across the United States, the average number of commercial credit accounts per business has declined from approximately 1.8 in 2018 to 1.5 in 2026. The South experienced the steepest decline and currently has the fewest accounts per business. At the same time, commercial credit inquiries have increased since 2023, most recently peaking in early 2026. Inquiry rates have typically been higher in the Midwest and South. The combination of fewer existing accounts and elevated inquiry activity provides useful context for lenders seeking to understand the credit needs of a growing population of younger businesses. Credit utilization tells another part of the story Regional differences also appear after businesses establish credit relationships. Businesses in the Midwest and North opening new commercial accounts tend to receive higher lines than businesses in the South and West. At the same time, businesses in the South show higher commercial card utilization despite carrying somewhat lower average balances. Experian’s analysis points to lower credit lines as an important factor behind that relationship. These trends reinforce why looking beyond a single credit metric can be important. Higher utilization, for example, can take on additional context when considered alongside credit-line size, business age, balances and regional business formation. Growth brings opportunities—and risk factors to monitor Despite significant growth and changes in business composition, regional credit performance has remained relatively steady. Commercial delinquencies across all regions are near pre-pandemic levels, while commercial credit risk scores have been relatively stable. There are regional differences worth monitoring, however. Businesses in the South have lower average commercial credit scores than businesses in the other regions analyzed, and delinquency rates tend to be higher in the North and South than in the Midwest and West. The broader takeaway is not simply that there are more small businesses in the South. It is that the composition of the commercial market is evolving alongside that growth. The South represents a growing share of credit-active businesses and new commercial accounts. Many of those businesses are younger, smaller and have fewer established commercial credit relationships. Their credit needs and behaviors may therefore differ from those of more mature businesses in other parts of the country. For commercial lenders and risk leaders, understanding those distinctions can help provide greater context around acquisition, underwriting and portfolio management decisions. As small business formation continues, Experian will continue monitoring where that growth is occurring—and how the changing business landscape is showing up in commercial credit behavior. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Where are small businesses growing in the U.S.? Experian data points to significant growth in the South. While new business formation has increased across the country, the South has consistently recorded the highest volume of new business openings and has seen the number of credit-active businesses grow 70% since 2018—compared with 55% nationally. Where are small businesses growing the most? The South has consistently had the largest volume of new business openings. The South led application growth during 2020–2021, while the West has posted the strongest growth rates since 2022. That distinction is important because it prevents the SEO headline from overstating what the data shows. Why has small business growth been so strong in the southern U.S.? The South has added more than 3.6 million residents since 2020, substantially outpacing other regions. Our report establishes a correlation rather than causation. Related Posts
Explore Experian insights on U.S. manufacturing investment, AI and automation adoption, employment trends, and commercial credit performance.
Experian’s latest Commercial Pulse analysis examines these trends using retail spending data alongside Experian commercial credit data.