Experian Commercial Pulse Report reveals compelling growth trends for the telecommunications industry.
The telecommunications industry is undergoing one of the most significant transformations in its history. While employment has steadily declined over the past two decades, demand for digital connectivity continues to accelerate, creating a unique combination of revenue growth, operational efficiency, and evolving commercial credit behavior.
For lenders, suppliers, and businesses serving the telecommunications sector, understanding these structural changes is becoming increasingly important.
Experian’s latest Commercial Pulse Report finds an industry that is borrowing more frequently, investing aggressively in next-generation infrastructure, and demonstrating improving credit performance despite ongoing consolidation.
Watch the Commercial Pulse Update
An Industry Powering the Digital Economy
The broader Information sector, which includes telecommunications, contributes approximately 5.6% of U.S. Gross Domestic Product, making it one of the nation’s largest economic sectors.
Telecommunications extends well beyond traditional wireless carriers. The industry includes:
- Wired communications providers
- Wireless carriers
- Satellite communications companies
- Cable and broadband providers
- Telecommunications resellers
- Specialized communications businesses
Together, these businesses provide the digital infrastructure that supports nearly every industry in today’s economy.
As cloud computing, artificial intelligence, streaming services, connected devices, and enterprise digital transformation continue expanding, virtually every major technology trend depends on reliable communications infrastructure.
That demand is creating a long runway for future growth.
Revenue Growth Is Being Driven by Data
The telecommunications business model has changed dramatically.
Rather than relying on traditional voice services, revenue growth is increasingly driven by fixed and mobile data usage as consumers and businesses consume more bandwidth than ever before.
According to the Ericsson Mobility Report, mobile data traffic per smartphone has nearly doubled during the past five years and is expected to double again over the next five years.
Today’s telecommunications providers are shifting their focus from simply building 5G networks to maximizing the value of those investments through enterprise services, network automation, premium connectivity offerings, and artificial intelligence.
Revenue Is Growing While Employment Declines
One of the industry’s most interesting characteristics is the disconnect between revenue growth and employment.
Historically, growing industries added workers as revenue increased. Telecommunications has followed a different path. Employment has steadily declined from roughly 1.25 million workers around 2000 to fewer than 600,000 today, even as industry revenues continue to expand. This apparent contradiction reflects structural transformation rather than industry weakness.
Several long-term trends are driving this shift:
- Industry consolidation has reduced the number of communications providers.
- Automation has streamlined network operations.
- Cloud-based infrastructure has improved efficiency.
- Software-defined networking has reduced operational complexity.
- Artificial intelligence is increasingly supporting network management and maintenance.
Today’s providers require fewer employees overall, but a larger share of highly specialized technical talent.
The result is an industry becoming operationally leaner while continuing to invest heavily in digital infrastructure.
Commercial Credit Demand Reflects Continued Investment
Those investment priorities are clearly reflected in Experian’s commercial credit data.
Telecommunications businesses continue to seek commercial financing more aggressively than businesses in most other industries. Experian’s research shows commercial credit inquiries among telecom businesses run approximately 12% higher than comparable businesses outside the telecommunications sector. Not only are telecom businesses borrowing more frequently, they’re also borrowing larger amounts.Over the past several years, newly originated commercial lines and loans have averaged approximately 30% higher than those originated by businesses in other industries.
These borrowing patterns align with continued investment in:
- Network modernization
- Artificial intelligence
- Edge computing
- Cybersecurity
- Satellite communications
- Next-generation connectivity technologies
Although telecommunications companies have become more operationally efficient, they remain highly capital intensive.
Investment Is Shifting Across the Industry
Experian’s data also highlights where investment is occurring.
One notable trend is the recent increase in commercial originations within the satellite telecommunications subsector. As providers expand rural broadband coverage, develop direct-to-device communications, and integrate satellite capabilities with traditional wireless networks, satellite communications are becoming a growing share of newly originated telecom accounts.
This reflects the broader evolution taking place across the industry as providers diversify beyond traditional network services and pursue new revenue opportunities.
Credit Performance Continues to Improve
Perhaps the most encouraging finding from Experian’s research is the improving stability of telecom credit performance.
Historically, delinquency rates within telecommunications tended to be more volatile than those in many other industries. That trend has changed significantly.
Over the past four years:
- 90+ day delinquency volatility declined approximately 70%.
- Overall late-stage delinquency rates declined approximately 40%.
- Commercial card utilization has remained closely aligned with businesses in other industries.
Several additional commercial credit metrics also show telecommunications businesses behaving more similarly to the broader commercial market than they have historically.
While additional observation is needed before concluding this represents a permanent structural shift, the convergence is an encouraging signal for lenders monitoring industry risk.
What This Means for Commercial Lenders
Telecommunications presents an unusual combination of characteristics rarely found together. The industry continues investing aggressively despite workforce reductions. Businesses are seeking larger commercial credit facilities while demonstrating improving repayment stability. Demand for connectivity continues to expand even as providers become increasingly efficient.
For commercial lenders, suppliers, and risk professionals, these trends suggest telecommunications businesses should be evaluated within the context of the industry’s ongoing transformation rather than historical assumptions alone. The sector’s commercial credit profile increasingly reflects strategic investment in long-term infrastructure rather than financial stress.
As artificial intelligence, 5G monetization, satellite communications, and enterprise connectivity continue reshaping the marketplace, telecommunications is likely to remain one of the most closely watched sectors within commercial lending.
Stay Informed with Commercial Pulse
Experian’s Commercial Pulse Report combines macroeconomic trends with proprietary commercial credit data to help lenders, suppliers, and business leaders better understand emerging risks and opportunities across industries.
As telecommunications continues to evolve, Experian will continue monitoring how industry transformation influences commercial credit behavior and what it means for lending, portfolio management, and business growth.
Learn more
- ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis.
- ✔ Subscribe to our YouTube channel for regular updates on small business trends.
- ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow.
Related Posts
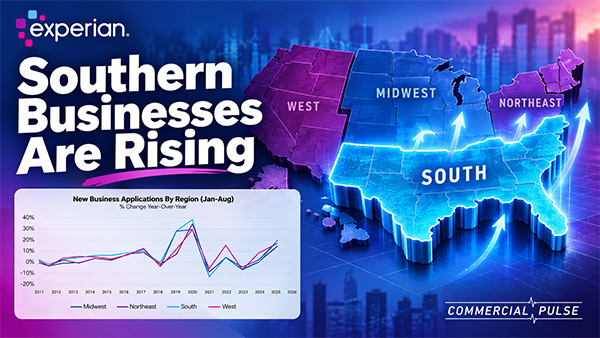
Small business formation remains one of the more notable trends in the U.S. economy. In August 532,000 new businesses launched across the country. While that was down from July, it remained well above historical averages. Since July 2020, an average of 455,000 new businesses have opened each month—56% higher than the pre-pandemic monthly average in 2018 and 2019. But the national numbers only tell part of the story. Watch The Commercial Pulse Update Experian’s latest Commercial Pulse report analysis examines where this growth is occurring and what it means for the commercial credit market. The data show that the South has emerged as an important center of small-business growth. And the businesses driving that expansion tend to have a different profile from their counterparts in other regions. For commercial lenders, understanding those differences can provide valuable context when evaluating new opportunities, credit demand and portfolio risk. Business growth is shifting geographically New business formation has increased across all U.S. regions, but the pace has not been uniform. Prior to 2018, regional differences in growth were relatively modest. During the pandemic years of 2020 and 2021, the South led the country in new business application growth. Since 2022, the West has posted the strongest growth, while the South continues to account for the greatest volume of new business openings. One factor providing context for that growth is population. The population of the South has grown more than 7% since 2019. Since 2020 alone, the region has added more than 3.6 million residents, outpacing every other U.S. region. Meanwhile, populations in other parts of the country declined between 2020 and 2022 before beginning to recover. Business formation and population movement do not necessarily have a simple cause-and-effect relationship. But their parallel growth highlights how the geographic makeup of both consumers and businesses has been changing. Credit-active businesses are growing even faster in the South The shift becomes even clearer when looking at businesses using commercial credit. Experian data shows the number of credit-active businesses in the United States has increased 55% since 2018. Every region participated in that expansion, but the South experienced the greatest growth at 70%, followed by the North at 52%, West at 50% and Midwest at 36%. The South now represents approximately 39% of U.S. credit-active businesses. It also accounted for more than 40% of newly opened commercial accounts in 2026, compared with 37% in 2019. For commercial credit organizations, that means the South represents not just a growing population of businesses, but an increasingly significant share of businesses participating in the commercial credit ecosystem. Southern businesses tend to be smaller and younger The composition of this growth is just as important as its scale. Credit-active businesses in the South and West tend to skew smaller and younger than those in the North and Midwest. In the South, 53% of businesses generate less than $500,000 in annual revenue, while 59% have fewer than five employees. Only 36% have been operating for more than 10 years, compared with 43% in the Midwest. Those characteristics can influence how businesses interact with credit. A younger business, for example, may have had less time to establish multiple commercial credit relationships. That pattern appears in Experian’s data. Across the United States, the average number of commercial credit accounts per business has declined from approximately 1.8 in 2018 to 1.5 in 2026. The South experienced the steepest decline and currently has the fewest accounts per business. At the same time, commercial credit inquiries have increased since 2023, most recently peaking in early 2026. Inquiry rates have typically been higher in the Midwest and South. The combination of fewer existing accounts and elevated inquiry activity provides useful context for lenders seeking to understand the credit needs of a growing population of younger businesses. Credit utilization tells another part of the story Regional differences also appear after businesses establish credit relationships. Businesses in the Midwest and North opening new commercial accounts tend to receive higher lines than businesses in the South and West. At the same time, businesses in the South show higher commercial card utilization despite carrying somewhat lower average balances. Experian’s analysis points to lower credit lines as an important factor behind that relationship. These trends reinforce why looking beyond a single credit metric can be important. Higher utilization, for example, can take on additional context when considered alongside credit-line size, business age, balances and regional business formation. Growth brings opportunities—and risk factors to monitor Despite significant growth and changes in business composition, regional credit performance has remained relatively steady. Commercial delinquencies across all regions are near pre-pandemic levels, while commercial credit risk scores have been relatively stable. There are regional differences worth monitoring, however. Businesses in the South have lower average commercial credit scores than businesses in the other regions analyzed, and delinquency rates tend to be higher in the North and South than in the Midwest and West. The broader takeaway is not simply that there are more small businesses in the South. It is that the composition of the commercial market is evolving alongside that growth. The South represents a growing share of credit-active businesses and new commercial accounts. Many of those businesses are younger, smaller and have fewer established commercial credit relationships. Their credit needs and behaviors may therefore differ from those of more mature businesses in other parts of the country. For commercial lenders and risk leaders, understanding those distinctions can help provide greater context around acquisition, underwriting and portfolio management decisions. As small business formation continues, Experian will continue monitoring where that growth is occurring—and how the changing business landscape is showing up in commercial credit behavior. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Where are small businesses growing in the U.S.? Experian data points to significant growth in the South. While new business formation has increased across the country, the South has consistently recorded the highest volume of new business openings and has seen the number of credit-active businesses grow 70% since 2018—compared with 55% nationally. Where are small businesses growing the most? The South has consistently had the largest volume of new business openings. The South led application growth during 2020–2021, while the West has posted the strongest growth rates since 2022. That distinction is important because it prevents the SEO headline from overstating what the data shows. Why has small business growth been so strong in the southern U.S.? The South has added more than 3.6 million residents since 2020, substantially outpacing other regions. Our report establishes a correlation rather than causation. Related Posts
Explore Experian insights on U.S. manufacturing investment, AI and automation adoption, employment trends, and commercial credit performance.
Experian’s latest Commercial Pulse analysis examines these trends using retail spending data alongside Experian commercial credit data.