Addressable TV and why financial services companies should embrace it

by Kerry Rivera 7 min read February 28, 2017

consumer-tv

Direct mail is not dead, but it’s 2017. Financial services companies need to acknowledge there might be other ways to deliver credit offers and capture consumer eyeballs. There are multiple screens competing for our attention, including one of the originals – TV. Advertising and TV have been married forever, but addressable TV allows marketers to target on a much more sophisticated level. Welcome to credit marketing in the digital age.

To help financial services companies understand the addressable TV channel, Experian marketing expert Brienna Pinnow answered the following questions in a short interview.

What is addressable TV?

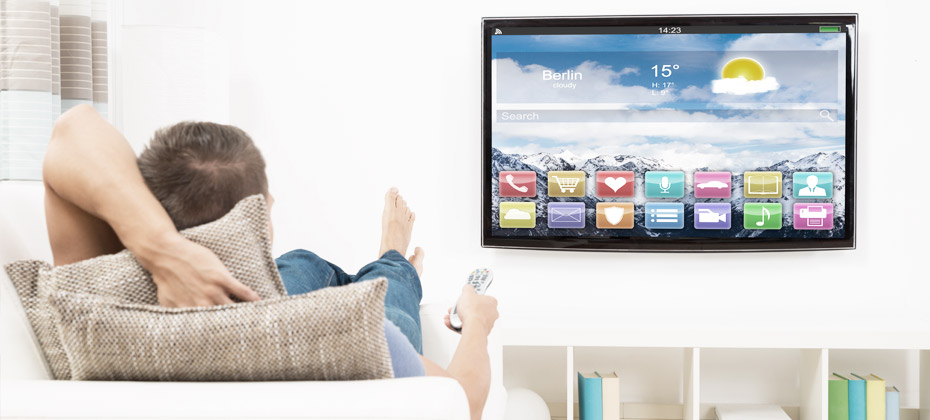
Addressable TV is an amazing 1-to-1 direct marketing capability. To put it simply, addressable TV is the ability for an advertiser to deliver a TV ad to a specific household. From a consumer perspective, that means even if you and your next door neighbor are watching the latest episode of The Voice, you may see an ad for a mini-van while your neighbor sees an ad for upcoming one-day sale from their favorite retailer. With addressable TV, brands can define their target audience based on 1st, 2nd or 3rd party data (like Experian’s). With the help of satellite and cable companies, they can deliver a personalized, measurable experience. This is an exciting departure from the way that TV advertising has been planned and targeted for nearly 70 years. Instead of focusing on the program, marketers can now focus on the person. Addressable TV makes reaching a precise audience – the same way you would with a direct mail piece or an email – a marketing reality.

 How long have marketers been leveraging addressable TV?

Experian has been an pivotal player in the development of the addressable TV space. Since the first addressable TV trials back in 2004, nearly 13 years ago, Experian has provided the audience targeting data and privacy-compliant matching capabilities that make addressable TV possible. The past 3 years, however, have demonstrated unprecedented, hockey-stick growth in addressable TV. In 2016 alone, the volume of addressable campaigns doubled from the previous year accounting for nearly $300 million spend.  That trajectory remains the same in 2017 and beyond. So why are we seeing this growth now? Here are a few reasons addressable TV is continuing to grow…

  • Scale: Millions of households can now be targeted using addressable technology, and the footprint continues to grow with smart TVs and additional cable operators.
  • Data: As organizations put data at the heart of their business, addressable TV enables them to infuse their most important customer information into the targeting.
  • Education: Agencies, data providers, and TV providers have invested time educating brands on the process and power of addressable TV. And now, advertisers are becoming more experienced at making this a consistent part of their marketing plan.
  • Accountability: You’ll be hard pressed to find a marketer that doesn’t have to demonstrate ROI on their marketing campaigns. The measurement capabilities that addressable TV provides adds a layer of accountability and insight that was not previously possible.
  • Technology: Experian has developed an audience management platform, the Audience Engine, which makes addressable TV possible in a matter of clicks. In the past year alone, our platform has distributed over 1,800 audiences for addressable advertising campaigns.

What types of companies have been utilizing addressable TV? Have you seen many financial services companies test this channel?

The early adopters of addressable TV were primarily automotive advertisers. Compared to other verticals, auto advertisers still spend the largest proportion of their budgets across TV. For that reason, they know it’s a necessity to see if their dollars are actually driving sales for their big-ticket items. Addressable TV solves that problem for auto advertisers. In a DIRECTV campaign leveraging Experian’s automotive data for audience targeting and post-campaign sales reporting, one major auto OEM saw a 26.2%  lift in sales for the advertised model compared to the control group. In the past few years, Experian has worked closely with advertisers across verticals – from retail to travel to finance – to launch addressable campaigns. Financial services clients particularly find Experian’s financial related segments, such as income or net worth, to be accurate and powerful in creating qualified target audiences that improve campaign performance.

I’ve read that millennials are abandoning cable and TV providers in favor of services like Hulu and Netflix. Does this mean the market for addressable TV will shrink in the coming years?

There is a segment of consumers who are abandoning traditional cable services. However, this doesn’t mean they are abandoning content. In fact, content consumption is at an all-time high with offerings from Roku, Hulu, Netflix, Sling TV, CBS, and beyond. All this shift in behavior means is that the definition of TV is becoming more fluid. “TV” doesn’t have to be a big screen sitting in your living room; it can be a laptop on a red-eye flight. And from a marketing perspective, the concept of addressable, 1-to-1 targeting is already moving into some of these products and services. The footprint of addressable TV will only continue to rise as consumers stay connected to the content they love.

How can companies measure the success of utilizing addressable TV as a channel?

Not only does addressable TV provide laser-targeted ad delivery, but it also opens up measurement capabilities that were never possible for TV advertisers in the past. Traditionally, TV audience measurement has focused simply on eyeballs and not revenue impact, with little insight into how TV advertising converts into sales. The primary source for audience measurement in the TV world has been program ratings and expensive brand studies. With addressable TV, that story is changing. With companies that collect second-by-second viewership data linked to households, marketers now have the ability to tie this data back to their online and offline sales. Experian is pivotal in making closed-loop TV reporting possible. As a data and matching safe-haven, we link together the viewing information from the target audience with the sales data provided by the advertiser. The end result is a privacy compliant report that clearly demonstrates the impact of the campaign on the target audience. Did the targeted audience visit a bank location? Email customer service? Sign up for a new account? Spend a certain amount? These are all questions our TV attribution reporting answers for clients.

If a company wants to begin marketing in addressable TV, what is required in terms of set-up?

Addressable TV may sound new, exciting or even complex. But it doesn’t have to be. Getting started is as simple as defining the target audience. Decide whether you would like to leverage your own CRM data, a custom model, third-party data or a combination of these data sources. If you’re still not sure where to start, ask yourself a very simple question, “Who am I sending a direct mail piece or email to in the next month?” There’s your audience. Better yet, you will be amplifying your message, reaching the customer with a consistent message and meeting them wherever they are. After you’ve determined who you want to target, a matching partner like Experian can work with you to show you the reach of your audience across TV providers. You’ll finalize your budget, creative and media plan while Experian distributes your audience to the selected media destinations. Before you know it, your campaign will be live, and reaching your target audience whether they’re watching Shark Tank or Sharknado. When the campaign wraps, you’ll be on your way to measuring results like never before.

Are there any additional trends you see emerging in the addressable TV space?

The future of addressable TV is related to both the targeting and measurement capabilities. More advertisers are working with Experian, for example, to launch coordinated campaigns. That doesn’t just mean launching a digital campaign and TV campaign at the same time. It really means targeting the same exact people for the digital and TV campaign. We like to consider this a “surround sound” approach where the customer or prospect experiences a consistent message across channels. As for measurement, Experian is working closely with advertisers to explore the power of mobile data. Recently, Experian partnered with Ninth Decimal and DIRECTV to incorporate mobile location data into the post-campaign measurement process for Toyota.  The results proved a 19% lift in dealership visits for those exposed to the campaign. This is an exciting development because this approach can translate well for any other advertiser who wants to measure metrics like location visitation.

If you’d like to learn more, check out our Addressable TV whitepaper.
Related Posts

Who’s Driving What? How Fuel Loyalty and Generational Preferences are Shaping the Vehicle Market

Take a look around at any road, parking lot, or highway, and you’ll see just how diverse today’s vehicle landscape has become. Within that evolving mix, electric vehicles (EVs) have seen years of rapid growth, and while the market is seemingly entering a new phase, interest remains. So, with several vehicles and fuel types to choose from, what keeps drivers coming back to electrified vehicles? Experian Automotive’s Automotive Market Trends Report: Q2 2026 found that among EV owners who returned to the market in the last 12 months, majority (72.2%) replaced their EV with another EV, while 18.5% switched to a gasoline vehicle. Hybrid buyers also showed considerable loyalty to electrification, with 55.7% of gas-hybrid owners staying with the same fuel type when replacing their vehicle, and 32.7% swapping for a gasoline vehicle. Consumers are seemingly remaining loyal to EVs and hybrids because they are attracted to the benefits that fit their everyday lifestyle, such as lower fuel or charging costs amid the elevated gas prices. For some, it could also be tied to convenience, as drivers who have found a reliable charging routine or appreciate the efficiency of a hybrid may have little reason to switch back to a traditional gasoline vehicle. Generations are taking different paths to electrification Generational differences also influence hybrid and EV loyalty, with younger consumers generally showing greater openness to alternative fuel types. While older generations tend to have greater familiarity with traditional gasoline vehicles, hybrid and EV adoption is increasing across all age groups as these options become more accessible and mainstream. Millennials, in particular, showed the strongest inclination toward electrified vehicles. Through Q2 2026, they accounted for the highest EV share at 8.2%, compared with Gen X at 5.5%, Gen Z (4.7%), and Baby Boomers (4.7%). The difference becomes even more pronounced when hybrids are in the mix, as 23.1% of Millennial registrations were gas-electric hybrids or plug-in hybrids, versus 16.7% for Gen X, 16.8% for Gen Z, and 18.0% for Baby Boomers. For automotive professionals, these differences make understanding who is driving what, and what they may choose next, increasingly important. The future of the automotive market may be less about consumers choosing one vehicle type over the other and more about understanding the distinct patterns and preferences of each generation. As the market continues to evolve, those insights can help automotive professionals better meet consumers where they are. To learn more about vehicle market trends, view the full Automotive Market Trends Report: Q2 2026 presentation on demand.

September 24, 2026 by John Howard
New Data Available for MBS Investors: Current Credit Score 

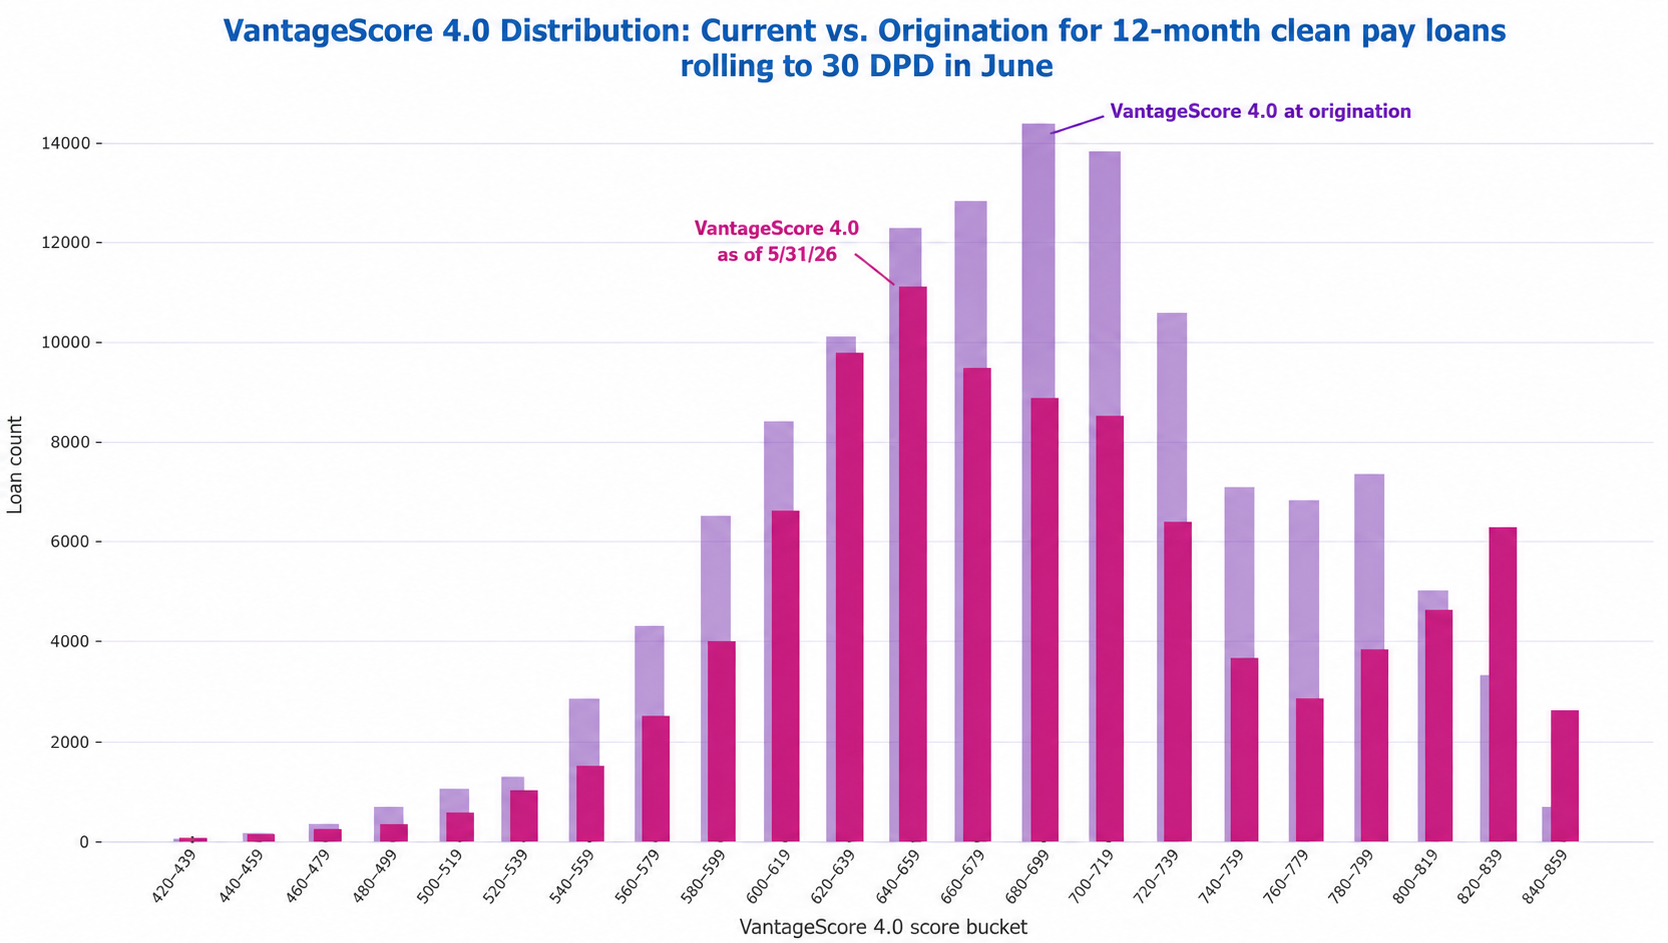
In a previous post, we described how every mortgage borrower’s financial situation and credit profile evolve over time.  After a borrower opens a loan, their financial status evolves—jobs are gained and lost; incomes can rise or fall, and financially stressful situations or windfalls can occur. These effects are often reflected in the consumer’s evolving credit score, which changes with the consumer’s payment behavior on open loans, credit inquiry activity, credit card utilization, and other revolving lines, among other things.    Even though MBS, whole loan, and MSR investors ultimately bear borrower credit risk, they may have access to less current borrower credit information than other participants in the mortgage ecosystem.   In securitized markets (both agency MBS and private-label MBS), updated scores are not provided in disclosure to bondholders, even as loans age year over year.  In whole loan and MSR markets, a single origination credit score is often provided at the time of bid, and after a successful bid, the investor may have a permissible purpose to pull individual scores on an owned portfolio. But until recently, there was no single loan-level dataset that included continuously refreshed credit scores across the U.S. mortgage market—the type of foundational dataset needed to build and tune credit and prepayment models.  A monthly-refreshed Current Credit Score field meets our three-pronged materiality standard for new data delivery to MBS markets:  New: Provides information not available in existing datasets (i.e., orthogonal to currently available data). Neither private-label MBS nor agency MBS standard market data includes a monthly-refreshed borrower credit score.  Material: Impacts a sizeable portion of the MBS universe. For the vast majority of loans in MBS, borrowers credit scores are available.  Significant: Differentiates collateral performance by a large enough margin to influence trading and risk management decisions.  A current credit score wraps all of a borrower’s credit-related behaviors into a single numerical value and has historically been associated with a borrower’s likelihood of becoming 60+ days past due on any obligation within the subsequent 24 months.    In fact, a current credit score is among the most informative indicators of near-term mortgage default risk, as shown in the image below, which depicts 30+ DPD rates by current credit score bands for the entire U.S. mortgage market, controlling for origination score <=650.    Without access to current credit scores, investors are limited to the score at origination—causing the four distinct performance trends shown here to appear as a single averaged line. In reality, score migration since origination reveals significant divergence in credit risk, with the lowest current-score bucket exhibiting a nearly 10 times higher 30+ DPD rate than the highest-score bucket in the latest period shown.  Source:  Experian Mortgage Loan Performance (MLP) dataset hosted on IVolatility DataDriven Platform  In this article, we’ll take a quick look at how score migration acts as an early predictor of a performing loan’s first roll into 30-day delinquent status.    MBS Investors’ Current Credit Score Blindspot: Solved   An MBS investor relying on standard market data and securitization remittance reports sees no sign of borrower stress until the subject mortgage loan in the securitization misses a payment and is reported at 30 days delinquent. Of course, in the vast majority of cases, a borrower begins struggling financially well before missing a mortgage payment:  The borrower may miss payments on other types of loans (credit card, auto loan, personal unsecured, or payday loans) as they prioritize their home and mortgage.  Outstanding balances on credit cards may grow as the borrower begins to make only minimum payments on revolvers.  The borrower may apply for additional credit cards, personal or payday loans   The borrower may apply to increase limits on existing credit cards as outstanding balance nears spending limit  All these stress-indicative behaviors result in a decreasing credit score, many months before the borrower misses their first mortgage payment. An MBS investor with access to each borrower’s current credit score, refreshed each month, can predict increased likelihood of default many months before the first missed mortgage payment—and is therefore at a major information advantage relative to the market generally.  Experian’s Mortgage Loan Performance (MLP) dataset contains thousands of fields describing mortgage performance from each borrower, loan, and property perspective, all refreshed monthly (including, amongst other things, new credit scores and refinance inquiry activity, loan performance on all types of debt, filed junior liens, and AVM values).   MLP is much more comprehensive than loan-level data provided by Freddie Mac, Fannie Mae, Ginnie Mae, and PLS data vendors in several ways:   Standard market datasets may not contain certain data elements that some market participants consider useful when evaluating mortgage prepayment or credit performance. Basic, critical fields such as the borrower’s current credit score and the current junior lien balance on the property are missing.    MLP contains borrower, loan, and property data fields spanning a broad portion of the mortgage universe, including Agency, Non-Agency, and Esoteric mortgage products (CES, HELOC, Reverse), including both securitized and non-securitized loans.   MLP enables full three-dimensional (borrower + loan + property) tracking with persistent keys for borrower (before and after refinancing), loan (in securities/deals even after exit due to payoffs or buyouts, including before and after MSR sales), and property.  This enables end-to-end analysis of each borrower’s (and property’s) mortgage experience throughout their credit lifecycle.  Is Downward-Trending Credit Score a Signal for Impending Delinquency?  MLP contains thousands of fields describing each loan, borrower, and property across all U.S. mortgages.  It allows for virtually unlimited segmentation and granular analysis.   For purposes of this illustrative article, we’ll take a high-level look at the entire U.S. mortgage market and perform a quick analysis to confirm intuition that a declining credit score provides a signal for higher likelihood of near-term mortgage delinquency.  Figure 1 illustrates the current pay status (as of 6/30) for the entire U.S. mortgage market, as contained in the MLP dataset, along with count, UPB and UPB-weighted Vantage 4.0 credit score for each bucket.  Figure 1  Source:  Experian Mortgage Loan Performance dataset  As illustrated in Figure 1, approximately 772,000 individual mortgage loans were reported to Experian as 30 days delinquent as of 6/30/2026.  Of the 772,000 30d delinquent loans in the June snapshot, approximately 426,000 were current in the prior (May) snapshot.  Some of these 426,000 loans were reperformers which had been bouncing from 30 DPD to current over the prior few snapshots. To remove reperformance score noise, we further parsed out the population which: 1) had rolled from current to 30 DPD from May to June; and 2) was consistently current for a full year prior to the 6/30 missed payment.  The population meeting both conditions totaled approximately 123,000 loans.  Figure 2 below shows, for this population of 123,000 “clean current” loans, the UPB-weighted average Vantage4 credit score for each of the 12 months leading up to the June missed payment, as well as the impact of the missed payment on the 6/30 score.  Figure 2  Source:  Experian Mortgage Loan Performance Dataset  Figure 2 reveals a rather slow and steady ~20-point deterioration of score in the 12 months prior to first missed payment – as well as the 80-point drop once the missed payment hits.  When we compare this cohort’s Vantage 4.0 score trend to the broader Current population across the entire dataset in Figure 3, we see a marked difference in both absolute value and trend:  Figure 3  Source:  Experian Mortgage Loan Performance Dataset  Not only is the cohort’s starting Vantage 4.0 score lower than the broader current population, but it also displays a dropping trend (with a notable 2 to 3x acceleration in monthly score drop the month before the first missed mortgage payment) while the broader Current population’s score (of which the isolated cohort is a subset) remains rock steady.  Lastly, we present Figure 4, a histogram comparing the distribution of at-origination and as-of 5/30 (i.e., the period just before the missed June mortgage payment) credit scores for the clean current population. The distribution appears to shift toward lower credit scores. To the extent credit scores are correlated with credit risk, this shift may indicate elevated credit risk relative to origination. Since this degradation occurs during a period of perfect mortgage pay performance, it is invisible to MBS investors who lack access to current borrower credit scores. Experian MLP provides monthly refreshed credit scores for mortgage borrowers contained within the MLP database.  Figure 4  Source:  Experian Mortgage Loan Performance Dataset 

September 22, 2026 by Michael Pyatski, Perry DeFelice
Ask the Expert: The Future of Lending Starts With Identity With Shawn Rife and Brian Cardona

Identity intelligence and alternative data can help lenders validate consumers and support more informed decisions across the customer lifecycle.

September 16, 2026 by Julie Lee

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe