As the world celebrates International Women’s Day on March 8, we want to shine a light on a few of the female leaders who shape, inspire and grow Experian. From sales to strategy, to people management, big data and beyond, women are a driving force in every industry – and their stories deserve to be told. Throughout the week, meet some of the “Women of Experian.”
Today, we feature Jennifer Leuer, president of Experian’s Partner Solutions division. Learn about her career journey, learnings and sources of inspiration as it pertains to leadership.
What do you do at Experian? 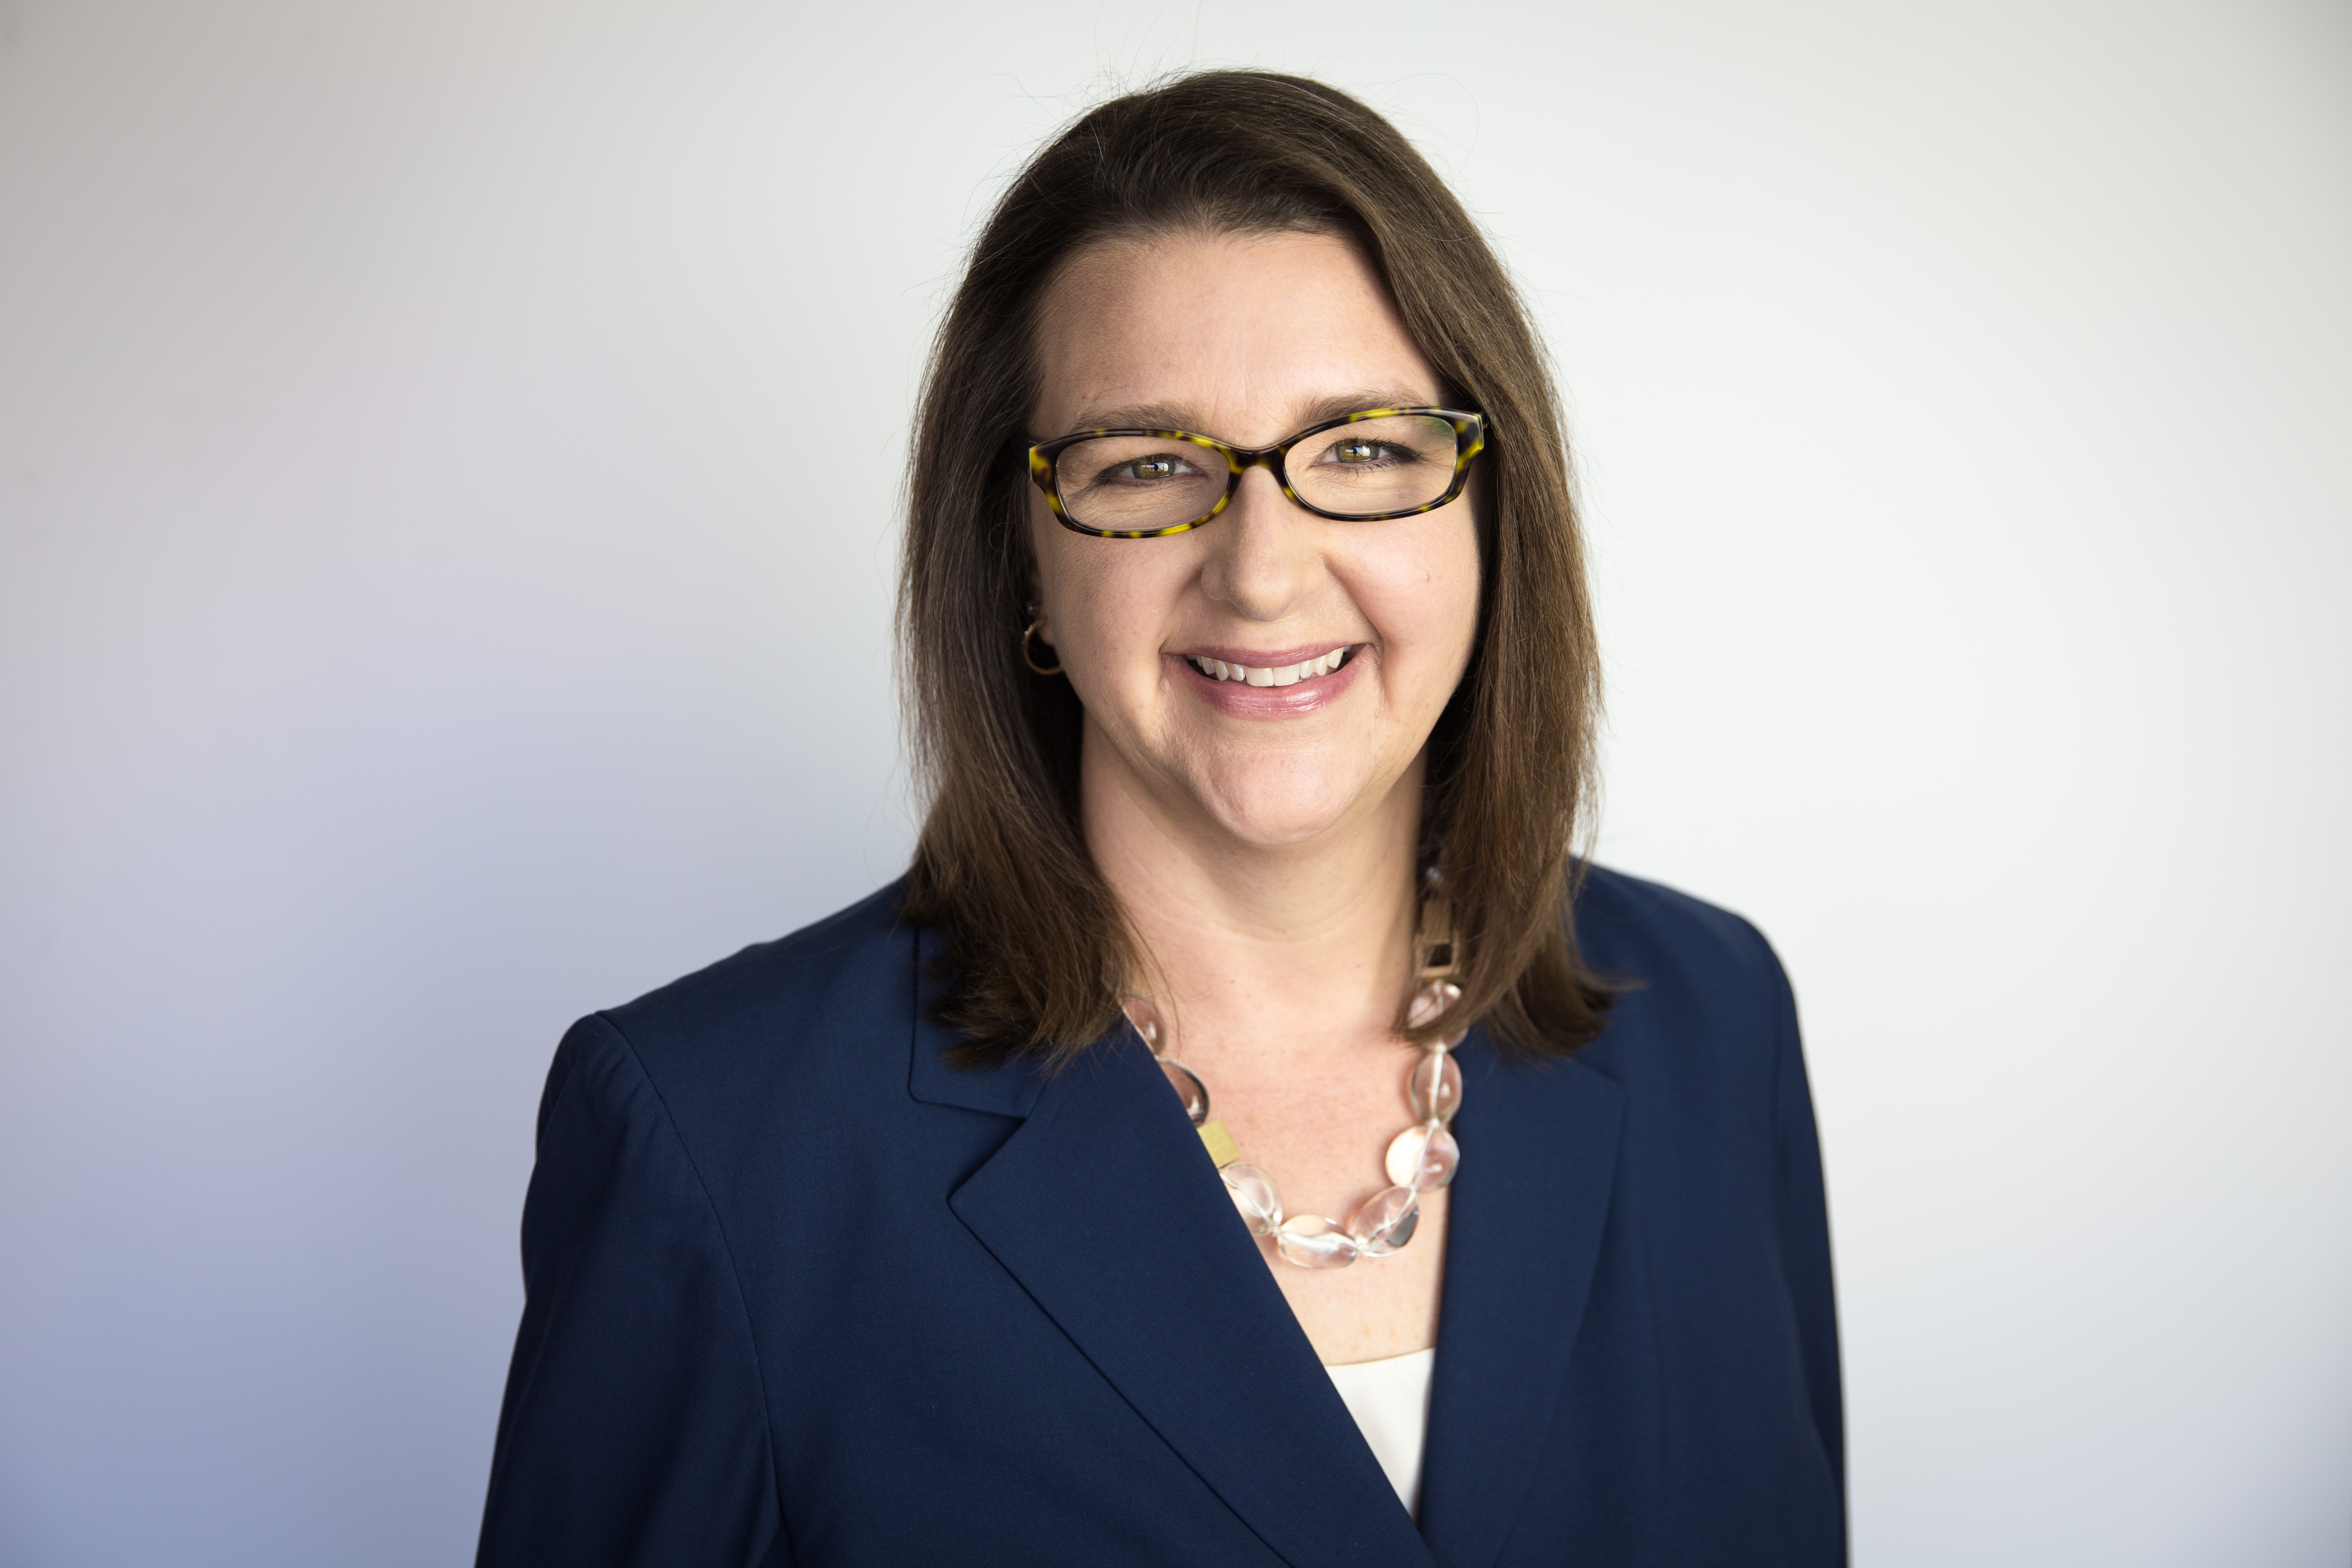
I lead our Partner Solutions business within Experian Consumer Services. As a B2B2C business, we serve consumer needs through strong partnerships with our clients, providing white label and cobranded solutions. Today, we provide consumers with credit education and identity protection products. In the future, we will go into adjacent services with business units throughout Experian. Those products allow our clients to reinforce their core value propositions with their consumers and better engage and retain them.
What’s a typical day like for you?
I don’t really have a typical day, which is one of the things I love about my role. Sometimes I’m out traveling to meet clients, talking with them about how we can grow together or about specific challenges they are facing. Other weeks I’m in our Costa Mesa or Austin offices discussing operations, financial performance, contract negotiations, business planning, progress against our vision and strategy, and most importantly our talented people and culture. I always love 1:1 meetings when we spend time on career development and two-way feedback. I enjoy hearing feedback from my colleagues throughout our organization and I think it’s essential to regularly provide it as well.
What are some patterns you’ve noticed over the years about women at work, and things they could be doing better to advance their careers?
While I don’t like to generalize, I’ve definitely seen a few commonalities observing female teammates across different functions and organizations.
- Women are often quite humble about their accomplishments and will emphasize the team’s contributions to a win. Ladies, get comfortable with talking about your individual wins and the role YOU played in broader initiatives. Brag a little! You can acknowledge the teamwork while also highlighting the unique role you played.
- I hear from many female colleagues that they don’t like speaking in meetings. I strongly believe that hearing different perspectives assists leaders with making better decisions. So, in your next meeting, add a data point to support the conversation, comment on the market context, or offer an alternative point of view. Also, one thing we can all do is open the door in meetings for our quieter colleagues to contribute. Saying something like, “Jen, we haven’t heard your point of view on this issue. What are your thoughts?” can create space in the conversation for a colleague to share their perspective.
- Finally, I’m currently reading a great book, “Own It,” which reinforces the leadership qualities that many women naturally bring to the workplace: Emotional intelligence, collaborative style, strong communication skills, orientation for win/win solutions. These are all powerful traits that drive significant value to teams and that women can really “own” with confidence.
What’s the most important business or other discovery you’ve made in the past year?
Does Amazon Fresh count? Being able to order groceries via wifi on an airplane is a game changer! Actually, it’s also a great example of what it took to make disruption in that space work—other companies tried and failed with grocery delivery because key pieces of the equation were missing. I love finding professional ah-ha’s as a consumer.
What is one characteristic that you believe every leader should possess?
I’m going to cheat and give a two-part answer on this one!
- I believe great leaders are inspired by their teams…and work for their teams. There are many takes on this philosophy, sometimes called servant leadership. Simon Sinek’s book “Leaders Eat Last” gave an updated view of this. When a leader is focused on assisting her team to grow, learn and thrive, the organization aligns around high performance and continuous improvement.
- One characteristic that I am currently working on is relentless curiosity: Asking more questions, really listening to the answers, then asking follow-up questions! Often we get into patterns where we opine more than listen, and the process of deep discovery unlocks creative solutions and new viewpoints.
What are your hobbies outside of work?
I feel like I have two families—at work and at home. Making sure I’m leading and serving both is an important part of my life. I used to think I should have more hobbies to force myself to have work/life balance! I’ve since learned it’s really about work/life integration. I know that setting aside time to relax and recharge is most important for me, so I spend free time on activities that give me joy and that I can do with my family. My husband and I enjoy completing 10K and half marathon runs, so we train together on the weekends. That gives us a chance to catch up while also forming a healthy habit. I love gardening and luckily my two sons can usually be persuaded to assist. And over the past couple years, we’ve enjoyed learning more about the world of comics together (Marvel, DC, etc.). Did you know Thor’s hammer (known as Mjolnir for the purists reading this!) actually passed to a woman last year? I think it’s pretty cool that there was a Goddess of a Thunder on comic book shelves!
Favorite authors/books?
I love to read! I enjoy books (printed and Audible versions), podcasts, and magazines. I will often check out a book summary before committing to a book (some examples are below). And magazines are my go-to for airplane reading. Here are a few I’d recommend for International Women’s Day:
- Harvard Business Review magazine is a great way to challenge your thinking and stay up to speed on a variety of new concepts and advancements
- Mindful magazine has great articles and practices
- “Rising Strong” by Brene Brown
- “The Confidence Code” by Katty Kay and Claire Shipman “Great Leaders Ask Great Questions” by John C Maxwell
- “Barking up the Wrong Tree—How to be awesome at life” by Eric Barker
- “The Pursuit of Perfection” by Tal Ben-Shahar
Check back to learn more about “Women of Experian” throughout the week.


