How lenders can use data to anticipate balance transfer activity

by Kyle Matthies 2 min read August 1, 2016

blog-post-credit-cards-image-930x420

Experian estimates card-to-card consumer balance transfer activity to be between $35 and $40 billion a year, representing a sizeable opportunity for proactive lenders seeking to grow their revolving product line.

This opportunity, however, is a threat for reactive lenders that only measure portfolio attrition instead of working to retain current customers. While billions of dollars are transferred every year, this activity represents only a small percentage of the total card population. And given the expense of direct marketing, lenders seeking to capitalize on and protect their portfolio from balance transfer activity must leverage data insights to make more informed decisions.

Predicting a consumer’s future propensity to engage in card-to-card balance transfers starts with trended data. A credit score is a snapshot in time, but doesn’t reveal deep insights about a consumer’s past balance transfer activity. Lenders that rely only on current utilization will group large populations of balance revolvers into one bucket – and many of these individuals will have no intention of transferring to another product in the near future.

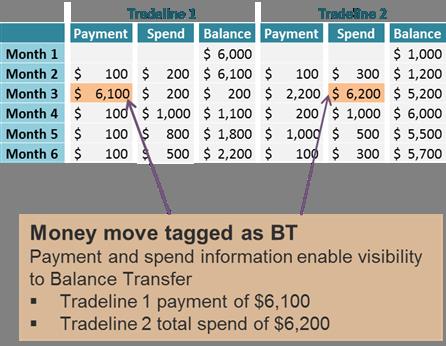
Still, balance transfer activity can be identified and predicted by utilizing trended data. By analyzing the spend and payment data over time to see when one (or multiple) trade’s payment approximately matches another trade’s spend, we have the logic that suggests there has been a card-to-card transfer.

What most people don’t realize is that trended data is difficult to work with. With 24 months of history on five fields, a single trade includes 120 data points. That’s 720 data points for a consumer with six trades on file and 72,000,000 for a file with 100,000 records, not to mention the other data fields in the file.

It’s easy to see why even the most sophisticated organizations become paralyzed working with trended data. While teams of analysts get buried in the data, projects drag, costs swell, and eventually the world changes as rates climb and fall. By the time the analysis is complete, it must be recalibrated.

But there is a solution.balance-transfer
Experian has developed powerful predictions tools that combine past balance transfer history, historical transfer amounts, current trades carried and utilized, payments, and spend. Combined, these data fields can help identify consumers who are most likely to transfer a balance in the future. With Experian’s Balance Transfer Index the highest scoring 10 percent of consumers capture nearly 70 percent of total balance transfer dollars. Imagine the impact on ROI of reducing 90 percent of the marketing cost of your next balance transfer campaign and still reaching 70 percent of the balance transfer activity.

Balance transfer activity represents a meaningful dollar opportunity for growth, but is concentrated in a small percentage of the population making predictive analytics key to success. Trended data is essential for identifying those opportunities, but financial institutions must assess their capabilities when it comes to managing the massive data attached.

The good news is that regardless of financial institution size, solutions now exist to capture the analytics and provide meaningful and actionable insights to lenders of all sizes.

Related Posts

Identity intelligence and alternative data can help lenders validate consumers and support more informed decisions across the customer lifecycle.

September 16, 2026 by Julie Lee
As Electric Vehicle Adoption Eases, Dealers Can Find New Opportunities To Reach Consumers

After years of rapid growth, new electric vehicle (EV) registrations have moderated, and the EV market has entered a new chapter. But slower growth shouldn’t be mistaken for disappearing demand, with data suggesting the reality is much more nuanced. According to Experian Automotive’s Automotive Consumer Trends Report: Q2 2026, battery EVs accounted for 8.21% of new retail registrations in the last 12 months, down from 9.23% a year earlier. However, consumers aren’t simply walking away from electrification. In fact, more than one million new EVs were registered during the past 12 months and the used EV market recorded more than 540,000 registrations over the same period. The opportunity may be less about waiting for the EV market to grow and more about understanding where EV demand is present, who is driving them, and how to reach those consumers more effectively. Who is likely to purchase an EV and what vehicle types are they interested in? Understanding who’s in the market for an EV can allow dealers to position themselves around consumers’ needs as they choose a vehicle that fits their everyday lifestyle. In the second quarter of 2026, Millennials and Gen X accounted for 67.83% of new EV registrations, nearly 10 percentage points above their combined share of all new, retail registrations. Millennials were also the largest generational audience across both new and used EV market share, coming in at 35.76% and 38.42%, respectively. It’s important to consider that the EV shopper isn’t necessarily looking for an unfamiliar or new type of vehicle. In many cases, they’re seemingly looking for an electric version of the practical vehicle they already know. For instance, SUVs accounted for 77.47% of new EV registrations in Q2 2026, which was similar to SUVs’ 63.49% share of all new retail registrations. For these shoppers, creating messaging around value, practicality, and available choices may resonate differently than premium technology messaging aimed at some new-EV prospects. The more precisely dealers can identify those audiences, the less they need to depend on broad EV market momentum to generate demand. To learn more about EV insights, view the full Automotive Consumer Trends Report: Q2 2026 presentation.

September 15, 2026 by Kirsten Von Busch
Infographic – The Mortgage Conversion Opportunity: How Finding the Right Borrowers Drives More Closings

With only one in three mortgage shoppers who submit a hard credit inquiry ultimately closing, lenders have an opportunity to rethink how they identify and engage prospective borrowers. This post explores why credit scores alone may not provide a complete picture of borrower readiness and how broader financial insights can help lenders identify consumers who may be more prepared to move forward, prioritize engagement, and improve mortgage conversion.

September 10, 2026 by Royce Chang

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe