At A Glance
Telecommunications industry disruption has reshaped media, telecom, and credit markets. From MTV to AI, explore what’s driving the next wave.Is AI about to disrupt the telecommunications industry?
In this week’s Commercial Pulse Report, we explore potential AI disruption in the Telecommunications industry as the transition from analog to digital plays out, and industry consolidation takes hold.
Watch The Commercial Pulse Update
In 1979, a British new wave band called The Buggles released a song that would become an unlikely cultural landmark. Video Killed The Radio Star wasn’t just catchy—it was prophetic. The lyrics mourned the decline of radio as television and music videos began to dominate how audiences consumed content. Just a few years later, MTV launched, and the shift from audio to visual media was complete. Radio didn’t disappear, but it was permanently changed.
One line from the song captures the unease of that moment perfectly
“In my mind and in my car, we can’t rewind, we’ve gone too far,
The Buggles, 1979
pictures came and broke your heart, put the blame on VCR.”
It’s a lament about progress—about technology moving faster than society can comfortably absorb. And it’s a reminder that once disruption takes hold, there’s no rewinding the tape.
Fast forward more than four decades, and the irony is hard to miss. MTV itself—once the symbol of disruption—has faded from cultural relevance, ending as it started by playing “Video Killed The Radio Star” on December 31st, 2025. That same cycle defines today’s telecommunications industry disruption, as AI, automation, and consolidation reshape how companies operate and compete.
A Familiar Pattern of Disruption
Telecommunications has lived through repeated waves of technological upheaval. The shift from analogue to digital fundamentally altered how networks were built, how services were delivered, and how companies competed. That transition drove efficiency, reduced headcount, and accelerated consolidation across the industry.
Now, artificial intelligence represents the next inflection point.
As highlighted in this week’s Commercial Pulse Report, AI is no longer a future concept for telecom—it’s a near-term operational reality. Industry research shows that a majority of telecom executives expect AI to materially reshape their organizations by automating core functions such as network management, customer service, and fraud detection.
Just as video once replaced radio as the dominant format, AI is poised to redefine how telecom companies operate—faster, leaner, and increasingly software-driven.
And as history has shown, efficiency gains often come with structural consequences.
Consolidation, Scale, and Survival
Disruption rarely happens in isolation. It tends to accelerate industry consolidation, and telecom is no exception.
Over the past decade, mergers and acquisitions have reshaped the competitive landscape. In wireless, consolidation has resulted in three dominant players controlling the majority of the market. At the same time, the total number of private telecom establishments in the U.S. has declined sharply from its historical peak.
This mirrors what happened in media. MTV consolidated attention, then streaming consolidated distribution, and now a handful of platforms dominate content delivery. Each wave reduced the number of viable players while raising the cost of participation.
In telecom, AI may lower operating costs—but it also raises the bar for capital investment, data sophistication, and technological capability. Smaller firms face increasing pressure to either specialize, scale, or exit.
What the Credit Data Is Telling Us
One of the most telling insights from this week’s Commercial Pulse Report comes from telecom credit behavior.
Telecom businesses tend to seek credit more frequently than companies in other industries, reflecting ongoing investment needs. However, the average size of credit lines has steadily declined, even as utilization rates have returned to pre-pandemic levels.
In other words, telecom firms are doing more with less.
This dynamic suggests that businesses may be turning to alternative funding sources, reallocating capital internally, or operating under tighter credit constraints—despite stable demand for connectivity and data services.
For risk leaders and growth strategists, this creates a more complex environment. Traditional indicators alone may not fully capture resilience or vulnerability. Understanding industry-specific behavior becomes critical.
We Can’t Rewind—But We Can Prepare
The line from “Video Killed The Radio Star” still resonates because it captures a universal truth about disruption:
We can’t rewind—we’ve gone too far.
AI will not undo itself. The telecom industry will not revert to its pre-digital or pre-automation state. Just as radio adapted rather than disappeared, and MTV faded as new platforms rose, telecom companies will continue to evolve—some faster and more successfully than others.
The question is not whether disruption will occur, but who is prepared for it.
This week’s Commercial Pulse Report explores that question through the lens of macroeconomic conditions, small business credit health, and telecom-specific insights. Together, they offer a clearer picture of how innovation, consolidation, and credit trends are intersecting in early 2026.
Because while technology may break hearts along the way, understanding the data helps businesses stay ahead of the next verse.
Learn more
- ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis.
- ✔ Subscribe to our YouTube channel for regular updates on small business trends.
- ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow.
Related Posts
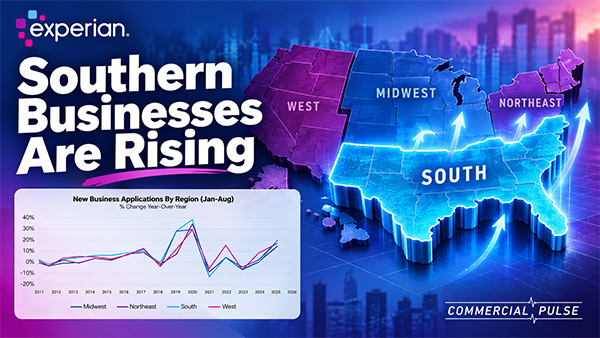
Small business formation remains one of the more notable trends in the U.S. economy. In August 532,000 new businesses launched across the country. While that was down from July, it remained well above historical averages. Since July 2020, an average of 455,000 new businesses have opened each month—56% higher than the pre-pandemic monthly average in 2018 and 2019. But the national numbers only tell part of the story. Watch The Commercial Pulse Update Experian’s latest Commercial Pulse report analysis examines where this growth is occurring and what it means for the commercial credit market. The data show that the South has emerged as an important center of small-business growth. And the businesses driving that expansion tend to have a different profile from their counterparts in other regions. For commercial lenders, understanding those differences can provide valuable context when evaluating new opportunities, credit demand and portfolio risk. Business growth is shifting geographically New business formation has increased across all U.S. regions, but the pace has not been uniform. Prior to 2018, regional differences in growth were relatively modest. During the pandemic years of 2020 and 2021, the South led the country in new business application growth. Since 2022, the West has posted the strongest growth, while the South continues to account for the greatest volume of new business openings. One factor providing context for that growth is population. The population of the South has grown more than 7% since 2019. Since 2020 alone, the region has added more than 3.6 million residents, outpacing every other U.S. region. Meanwhile, populations in other parts of the country declined between 2020 and 2022 before beginning to recover. Business formation and population movement do not necessarily have a simple cause-and-effect relationship. But their parallel growth highlights how the geographic makeup of both consumers and businesses has been changing. Credit-active businesses are growing even faster in the South The shift becomes even clearer when looking at businesses using commercial credit. Experian data shows the number of credit-active businesses in the United States has increased 55% since 2018. Every region participated in that expansion, but the South experienced the greatest growth at 70%, followed by the North at 52%, West at 50% and Midwest at 36%. The South now represents approximately 39% of U.S. credit-active businesses. It also accounted for more than 40% of newly opened commercial accounts in 2026, compared with 37% in 2019. For commercial credit organizations, that means the South represents not just a growing population of businesses, but an increasingly significant share of businesses participating in the commercial credit ecosystem. Southern businesses tend to be smaller and younger The composition of this growth is just as important as its scale. Credit-active businesses in the South and West tend to skew smaller and younger than those in the North and Midwest. In the South, 53% of businesses generate less than $500,000 in annual revenue, while 59% have fewer than five employees. Only 36% have been operating for more than 10 years, compared with 43% in the Midwest. Those characteristics can influence how businesses interact with credit. A younger business, for example, may have had less time to establish multiple commercial credit relationships. That pattern appears in Experian’s data. Across the United States, the average number of commercial credit accounts per business has declined from approximately 1.8 in 2018 to 1.5 in 2026. The South experienced the steepest decline and currently has the fewest accounts per business. At the same time, commercial credit inquiries have increased since 2023, most recently peaking in early 2026. Inquiry rates have typically been higher in the Midwest and South. The combination of fewer existing accounts and elevated inquiry activity provides useful context for lenders seeking to understand the credit needs of a growing population of younger businesses. Credit utilization tells another part of the story Regional differences also appear after businesses establish credit relationships. Businesses in the Midwest and North opening new commercial accounts tend to receive higher lines than businesses in the South and West. At the same time, businesses in the South show higher commercial card utilization despite carrying somewhat lower average balances. Experian’s analysis points to lower credit lines as an important factor behind that relationship. These trends reinforce why looking beyond a single credit metric can be important. Higher utilization, for example, can take on additional context when considered alongside credit-line size, business age, balances and regional business formation. Growth brings opportunities—and risk factors to monitor Despite significant growth and changes in business composition, regional credit performance has remained relatively steady. Commercial delinquencies across all regions are near pre-pandemic levels, while commercial credit risk scores have been relatively stable. There are regional differences worth monitoring, however. Businesses in the South have lower average commercial credit scores than businesses in the other regions analyzed, and delinquency rates tend to be higher in the North and South than in the Midwest and West. The broader takeaway is not simply that there are more small businesses in the South. It is that the composition of the commercial market is evolving alongside that growth. The South represents a growing share of credit-active businesses and new commercial accounts. Many of those businesses are younger, smaller and have fewer established commercial credit relationships. Their credit needs and behaviors may therefore differ from those of more mature businesses in other parts of the country. For commercial lenders and risk leaders, understanding those distinctions can help provide greater context around acquisition, underwriting and portfolio management decisions. As small business formation continues, Experian will continue monitoring where that growth is occurring—and how the changing business landscape is showing up in commercial credit behavior. Learn more ✔ Visit our Commercial Insights Hub for in-depth reports and expert analysis. ✔ Subscribe to our YouTube channel for regular updates on small business trends. ✔ Connect with your Experian account team to explore how data-driven insights can help your business grow. Download the Commercial Pulse Report Visit Commercial Insights Hub Where are small businesses growing in the U.S.? Experian data points to significant growth in the South. While new business formation has increased across the country, the South has consistently recorded the highest volume of new business openings and has seen the number of credit-active businesses grow 70% since 2018—compared with 55% nationally. Where are small businesses growing the most? The South has consistently had the largest volume of new business openings. The South led application growth during 2020–2021, while the West has posted the strongest growth rates since 2022. That distinction is important because it prevents the SEO headline from overstating what the data shows. Why has small business growth been so strong in the southern U.S.? The South has added more than 3.6 million residents since 2020, substantially outpacing other regions. Our report establishes a correlation rather than causation. Related Posts
Explore Experian insights on U.S. manufacturing investment, AI and automation adoption, employment trends, and commercial credit performance.
Experian’s latest Commercial Pulse analysis examines these trends using retail spending data alongside Experian commercial credit data.